Tandem Diabetes Care (TNDM -2.18%), a medical device company, has had a rough year. The company's shares are down by 43%. It might be tempting to consider the stock at current levels. If it can perform well over the next few years, initiating a position today would yield excellent returns in the medium term. However, several factors need to align for Tandem Diabetes Care to become an attractive investment. Let's discuss one of those.
Image source: Getty Images.
Can it record consistent top-line growth?
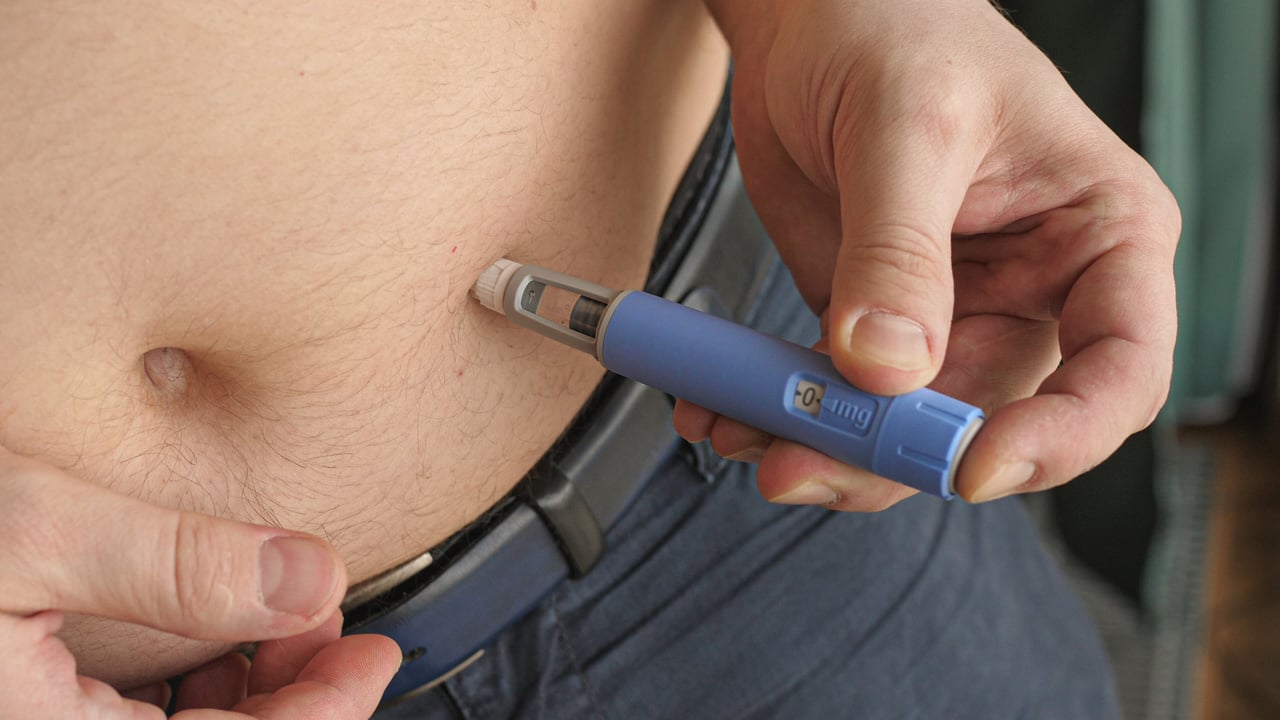
Here's one thing no one can take away from Tandem Diabetes Care: It is a highly innovative company whose insulin pumps are among the market leaders. The company's t:slim X2 has been its main growth driver for a long time. This device is user-friendly, can pair with continuous glucose monitoring devices to automate insulin delivery, is significantly smaller than most competing ones, and supports remote updates. Besides its best-known product, Tandem Diabetes Care also launched the Tandem Mobi in the U.S. last year.
The Mobi is even smaller and can be fully controlled via an app from a smartphone. Despite its innovative devices, Tandem Diabetes Care's revenue growth has been mostly southbound over the past five years, partly due to competition and lower demand for insulin pumps (as they can last for a long time, many longtime patients aren't too eager to renew).
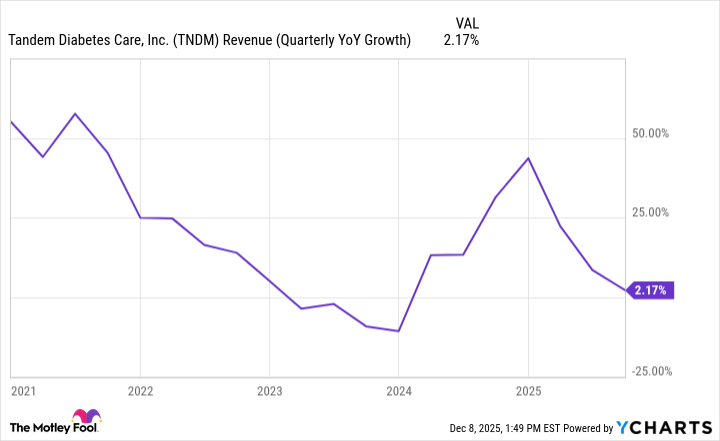
TNDM Revenue (Quarterly YoY Growth) data by YCharts.
Meanwhile, Tandem Diabetes remains unprofitable. The current uncertain and evolving global trade environment could further exacerbate Tandem Diabetes' financial situation. The company imports parts from various countries for manufacturing, including Mexico and China -- the latter of which has been one of President Donald Trump's favorite targets for steep tariffs.

NASDAQ: TNDM
Key Data Points
This could lead to increased costs and further squeeze the operating margin and the bottom line. Where does that leave Tandem Diabetes Care? It is sometimes wise to invest in a company that isn't consistently profitable yet. However, with inconsistent revenue growth, stiff competition, and industrywide challenges that could decrease profits (or, rather, increase losses), Tandem Diabetes Care doesn't fit the profile of a non-profitable stock worth investing in.
The company needs to increase top-line growth and maintain it in the mid-to-high teens, at least. It could do so by expanding its market share through attracting new customers and enticing current pump users to purchase new ones -- perhaps with updates or new launches -- thereby initiating a robust cycle of renewals. This would help increase margins and profits, even with tariffs.
Hold off on buying, for now
Will Tandem Diabetes Care be able to achieve that? The newer Tandem Mobi could be part of the solution, and the company has several other products in development. It will be interesting to monitor its progress in these areas. But for now, the stock isn't worth buying.