Shares of robotic-surgery pioneer Intuitive Surgical (ISRG +2.04%) have been pummeled in 2026, down about 26% and trading not too far from a 52-week low as of this writing. That has wiped nearly a third of the stock's value since it peaked above $600 in January, leaving it far behind the broader market this year.
Two worries appear to be driving the sell-off. One is competition out of China, where homegrown surgical robots are gaining ground quickly. The other is newer and louder: OpenAI's late-May move into building its own robots, which has stoked fears that the artificial intelligence (AI) giant could one day push into robotic surgery.
So, with the stock this beaten down, is it time to buy?

Image source: The Motley Fool.
The business keeps strengthening
It helps to first check whether anything has actually broken in the underlying business.
And rest assured, it hasn't.
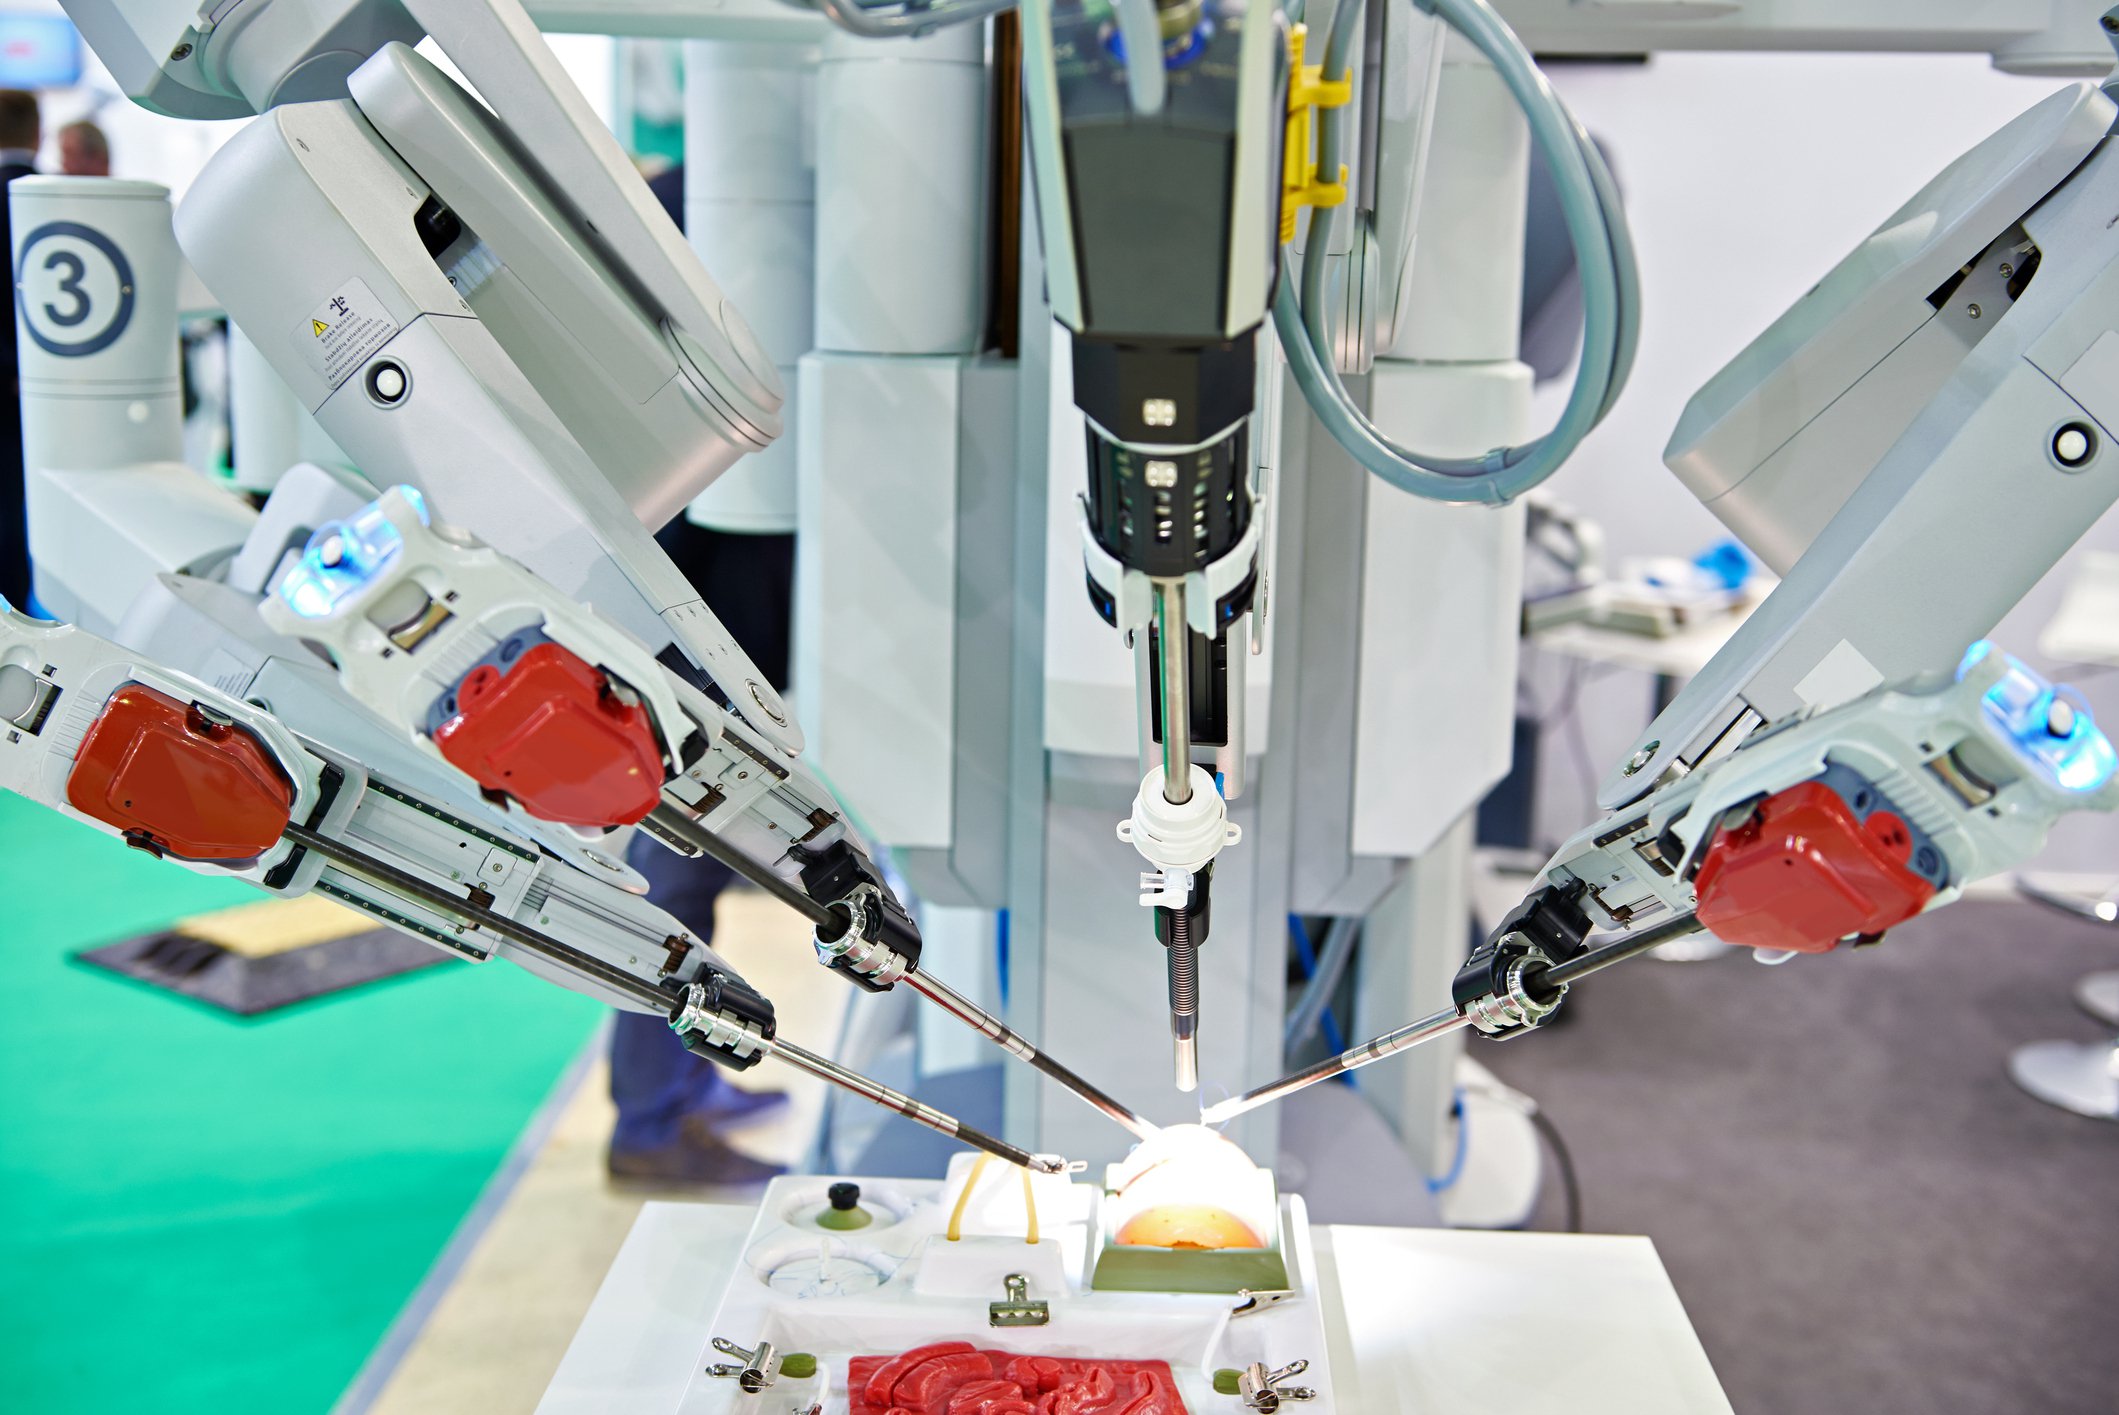
In the first quarter of 2026, Intuitive reported revenue of $2.77 billion, up 23% year over year. The telling detail is that revenue climbed faster than the 17% growth in worldwide procedures on the company's da Vinci and Ion systems.
As the newer da Vinci 5 -- now nearly 1,500 systems in use -- takes a larger share of placements, it commands higher prices, while instrument and accessory revenue per procedure climbed to about $1,880 versus roughly $1,780 a year earlier.
Also worth noting, recurring revenue now impressively accounts for 86% of Intuitive Surgical's total sales.
Placements held up as well.
Intuitive placed 431 da Vinci systems in the quarter, up from 367 a year earlier, and its installed base grew 12% to 11,395 systems.
Further, the company's non-GAAP (adjusted) operating margin reached 39%, and adjusted earnings per share jumped 38%.
Management even lifted its full-year outlook, now guiding for da Vinci procedure growth of 13.5% to 15.5%.
The competition picture
The China worry, however, is worth keeping an eye on. But it's not as big an issue as an investor new to the stock might assume.
Sure, Intuitive said its China procedure growth ran below the corporate average last quarter, held back by light tender activity and government-driven pricing pressure amid domestic rivals' share gains. And those rivals are advancing. In 2025, Chinese-made laparoscopic robots outsold imported ones in public tenders for the first time.
But China is a small piece of Intuitive's business. The company placed just 4 da Vinci systems there last quarter, against 226 in the U.S. and 117 in Europe, and total procedures outside the U.S. still grew 20%.
The OpenAI fear, on the other hand, may simply be overdone.
OpenAI's robotics effort, announced on May 31, targets general-purpose humanoid machines -- robots to help with construction and infrastructure now, and household tasks later. That is a different world from soft-tissue surgery, where Intuitive's moat rests on more than 11,000 installed systems and a two-decade head start in clinical evidence and regulatory clearances that an entrant would need years to match. OpenAI has no surgical product and has not even disclosed a hardware partner for its humanoid push. Intuitive Surgical CEO Dave Rosa has instead pointed to Intuitive's own surgical data -- the millions of procedures and force-feedback streams coming off da Vinci 5 -- as the foundation for its AI roadmap.
Of course, the real worry may be more subtle. Perhaps the fact that OpenAI is getting into robotics has some investors worried that AI will lower the barriers to entry for other healthcare companies to compete more directly with Intuitive Surgical in minimally invasive surgery. Still, there's no substance behind this potential threat yet.
With all of this said, there are still risks and legitimate concerns. Bariatric procedures, for instance, fell about 10% in the U.S. as GLP-1 weight-loss drugs cut into demand. And tariffs, along with higher memory and freight costs, are pressuring margins.

NASDAQ: ISRG
Key Data Points
The shares aren't cheap either. At a price-to-earnings ratio of about 51 as of this writing, this valuation leaves almost no room for slip-ups of any kind over the long haul.
Still, for investors who can tolerate the volatility associated with a highly valued growth stock, this could be a reasonable entry point for a small starter position into a dominant, fast-growing business, as businesses as high quality as Intuitive Surgical rarely trade at valuations that look attractive.