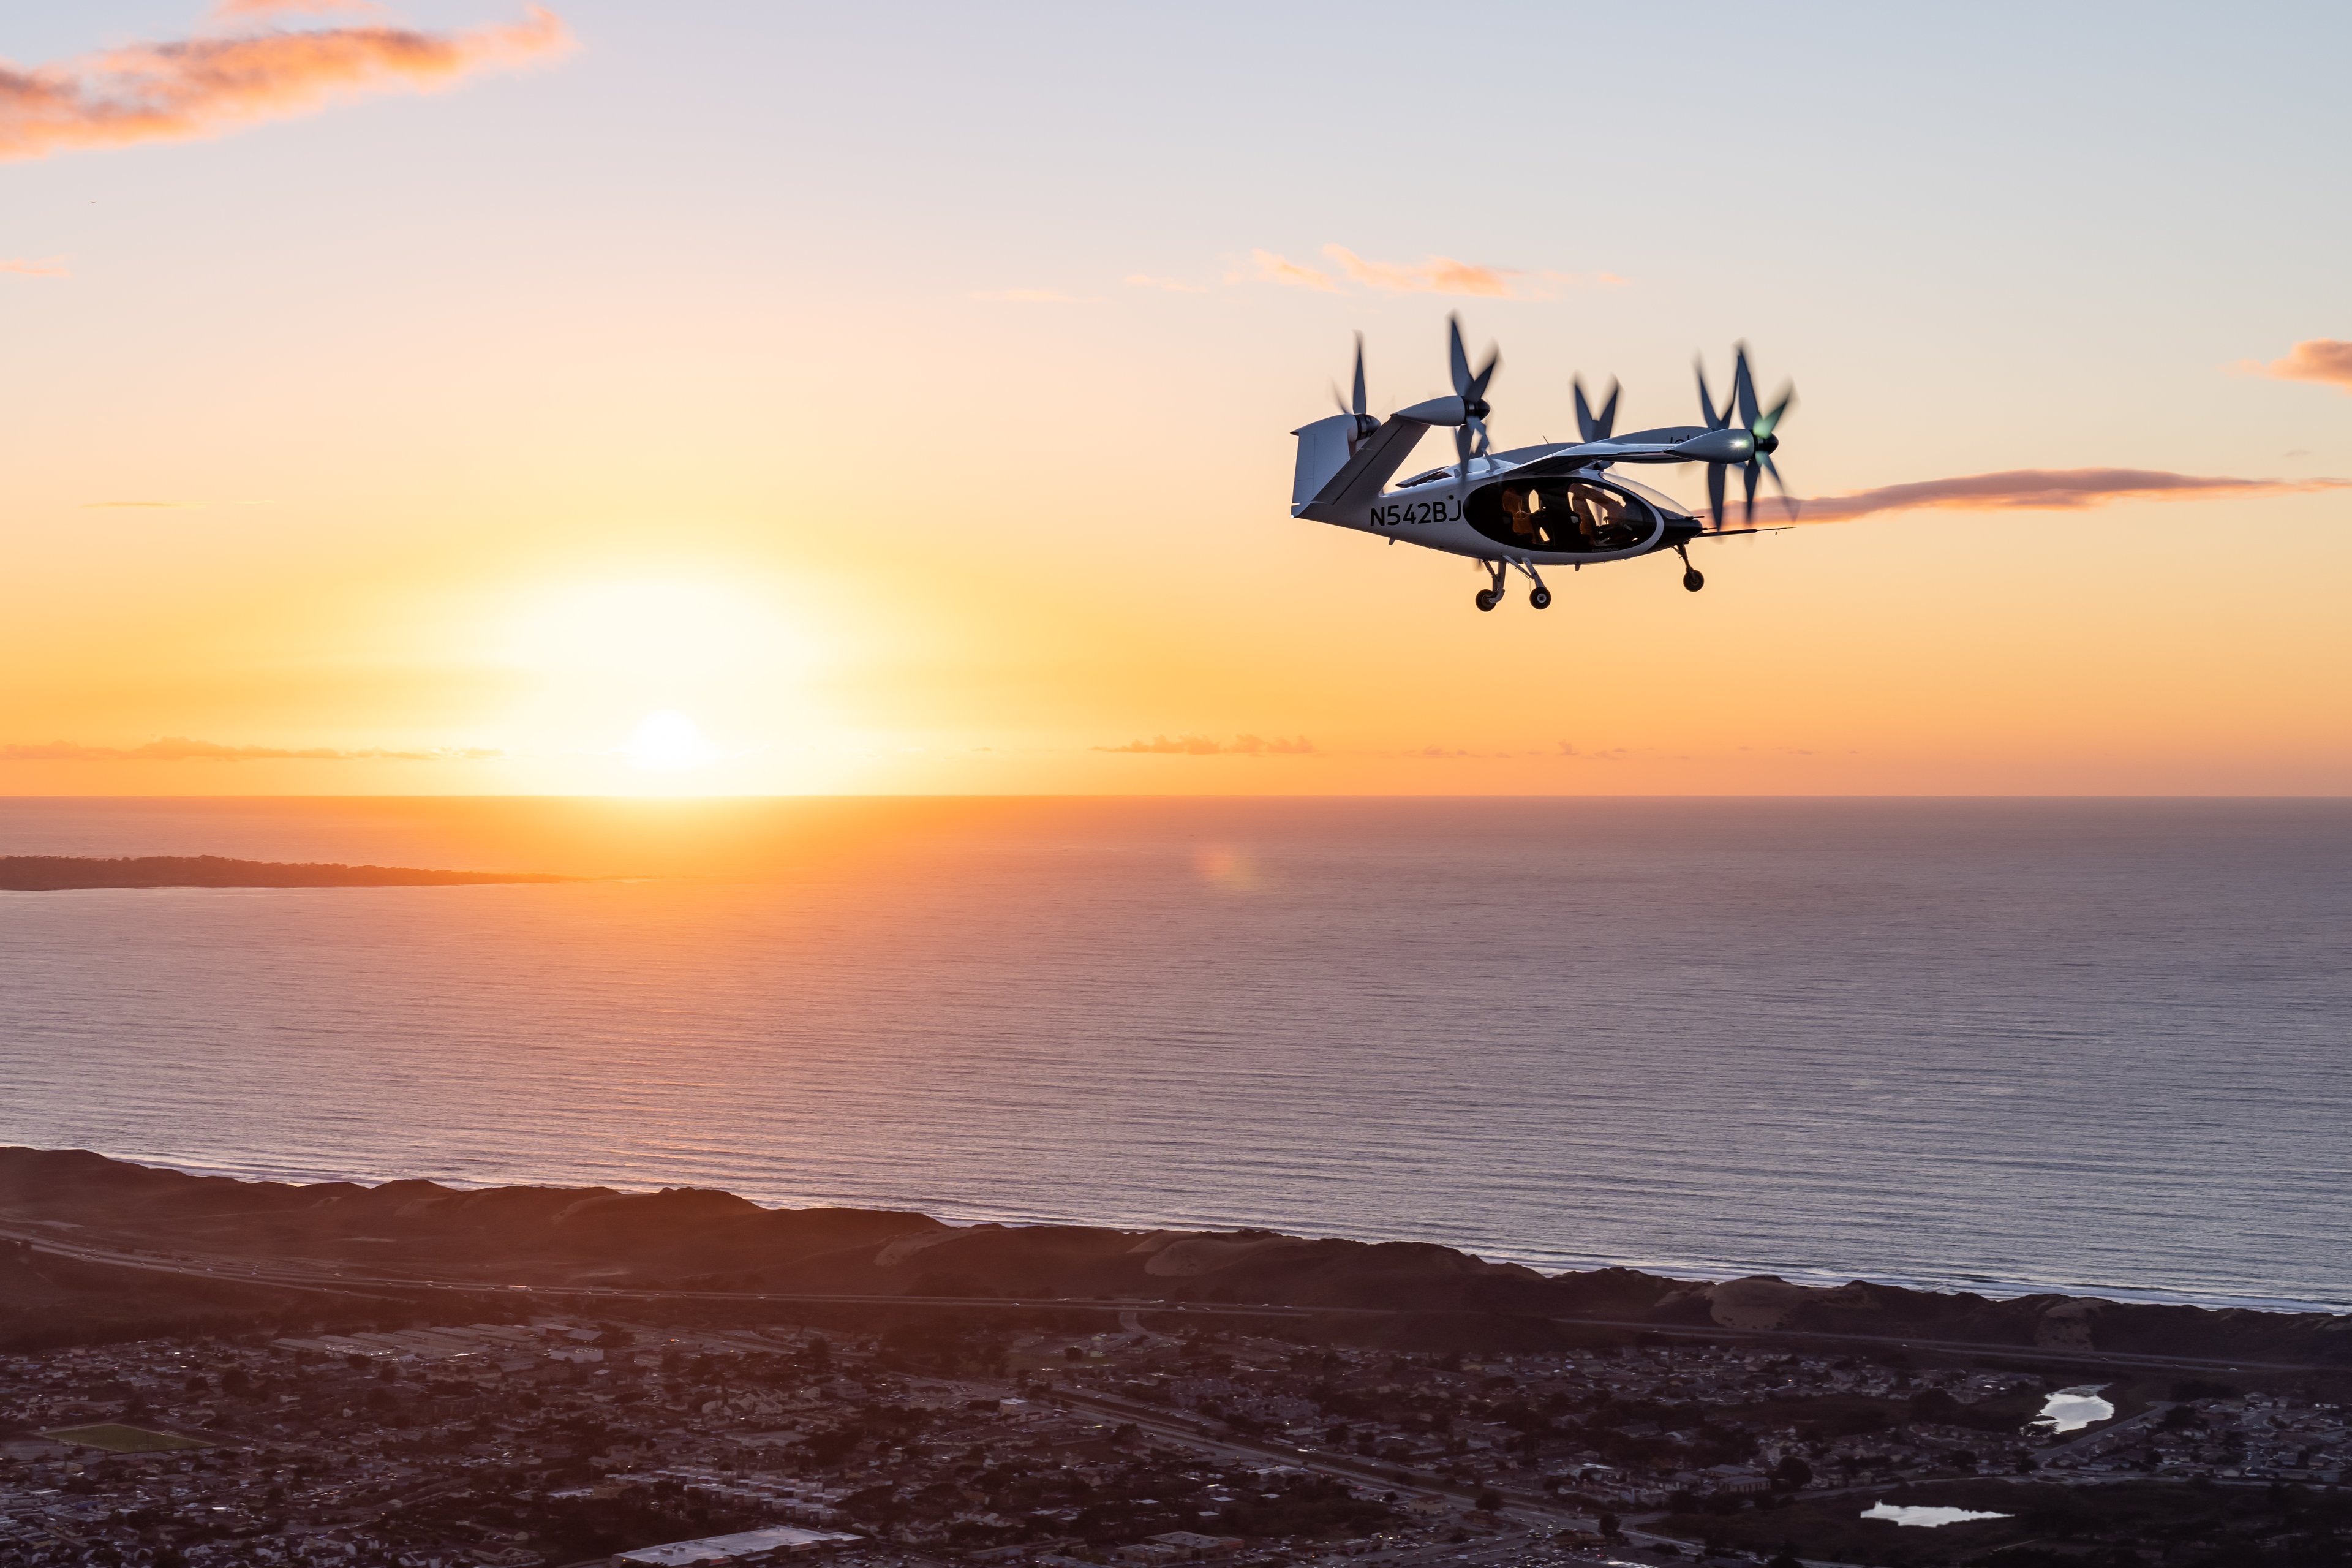
In 2009, NASA released a concept video of an electric vertical take-off and landing (eVTOL) aircraft, which could hover, take off, and land vertically. That video prompted many aerospace companies to develop their own eVTOLs, but many of those projects fizzled out.
Today, two of those early movers have risen to the top of the nascent market: Joby Aviation (JOBY -2.86%) and Archer Aviation (ACHR -3.48%). Both companies could soon be cleared by the Federal Aviation Administration (FAA) to launch their first commercial flights. However, I think it makes more sense to buy Joby instead of Archer as the top eVTOL play.
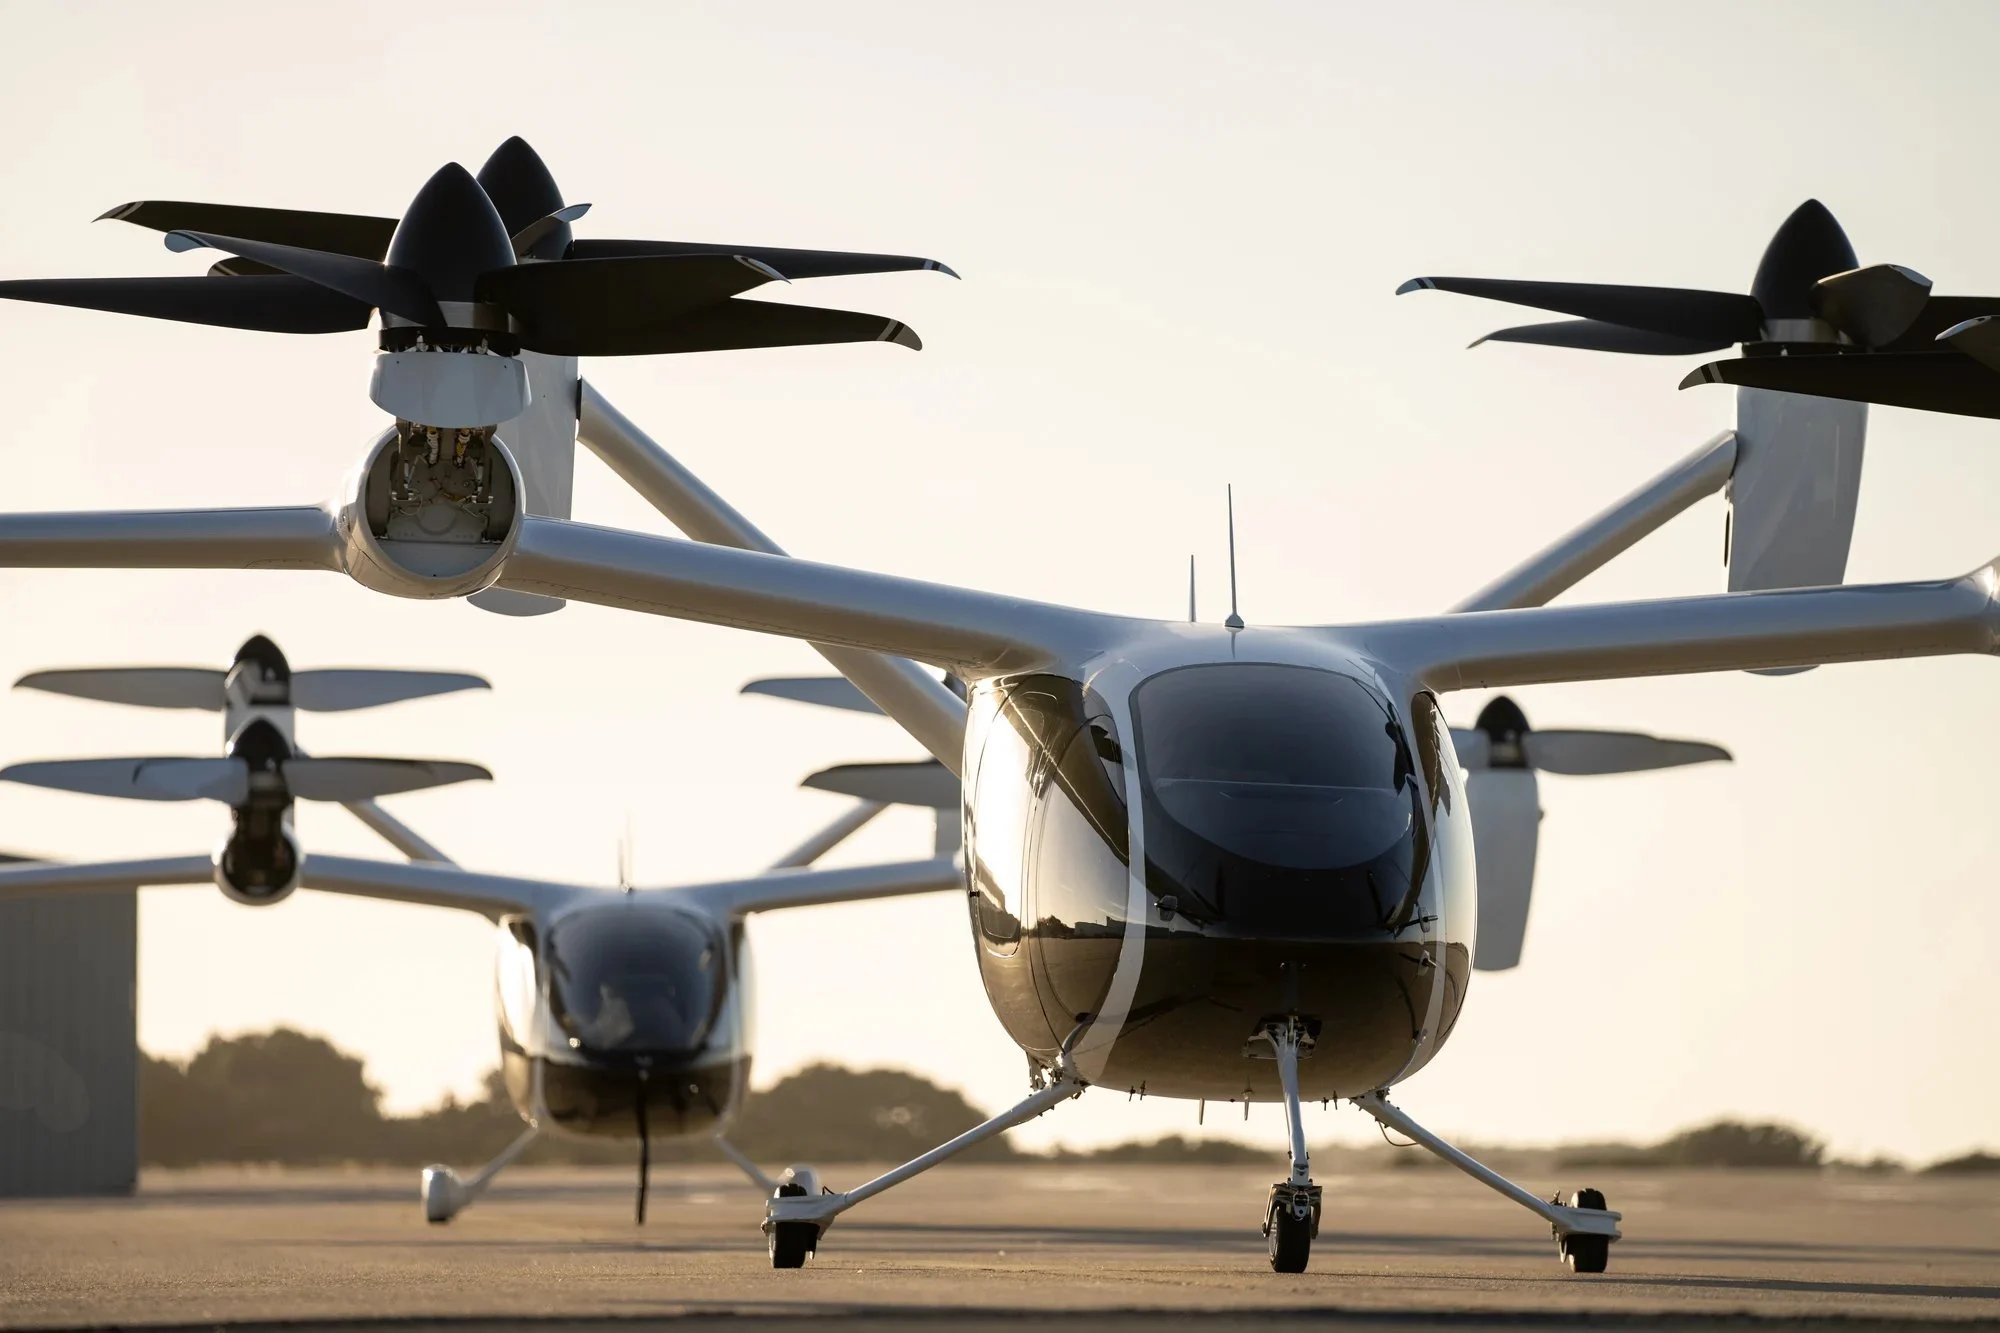
Image source: Getty Images.
Why is Joby a better buy than Archer?
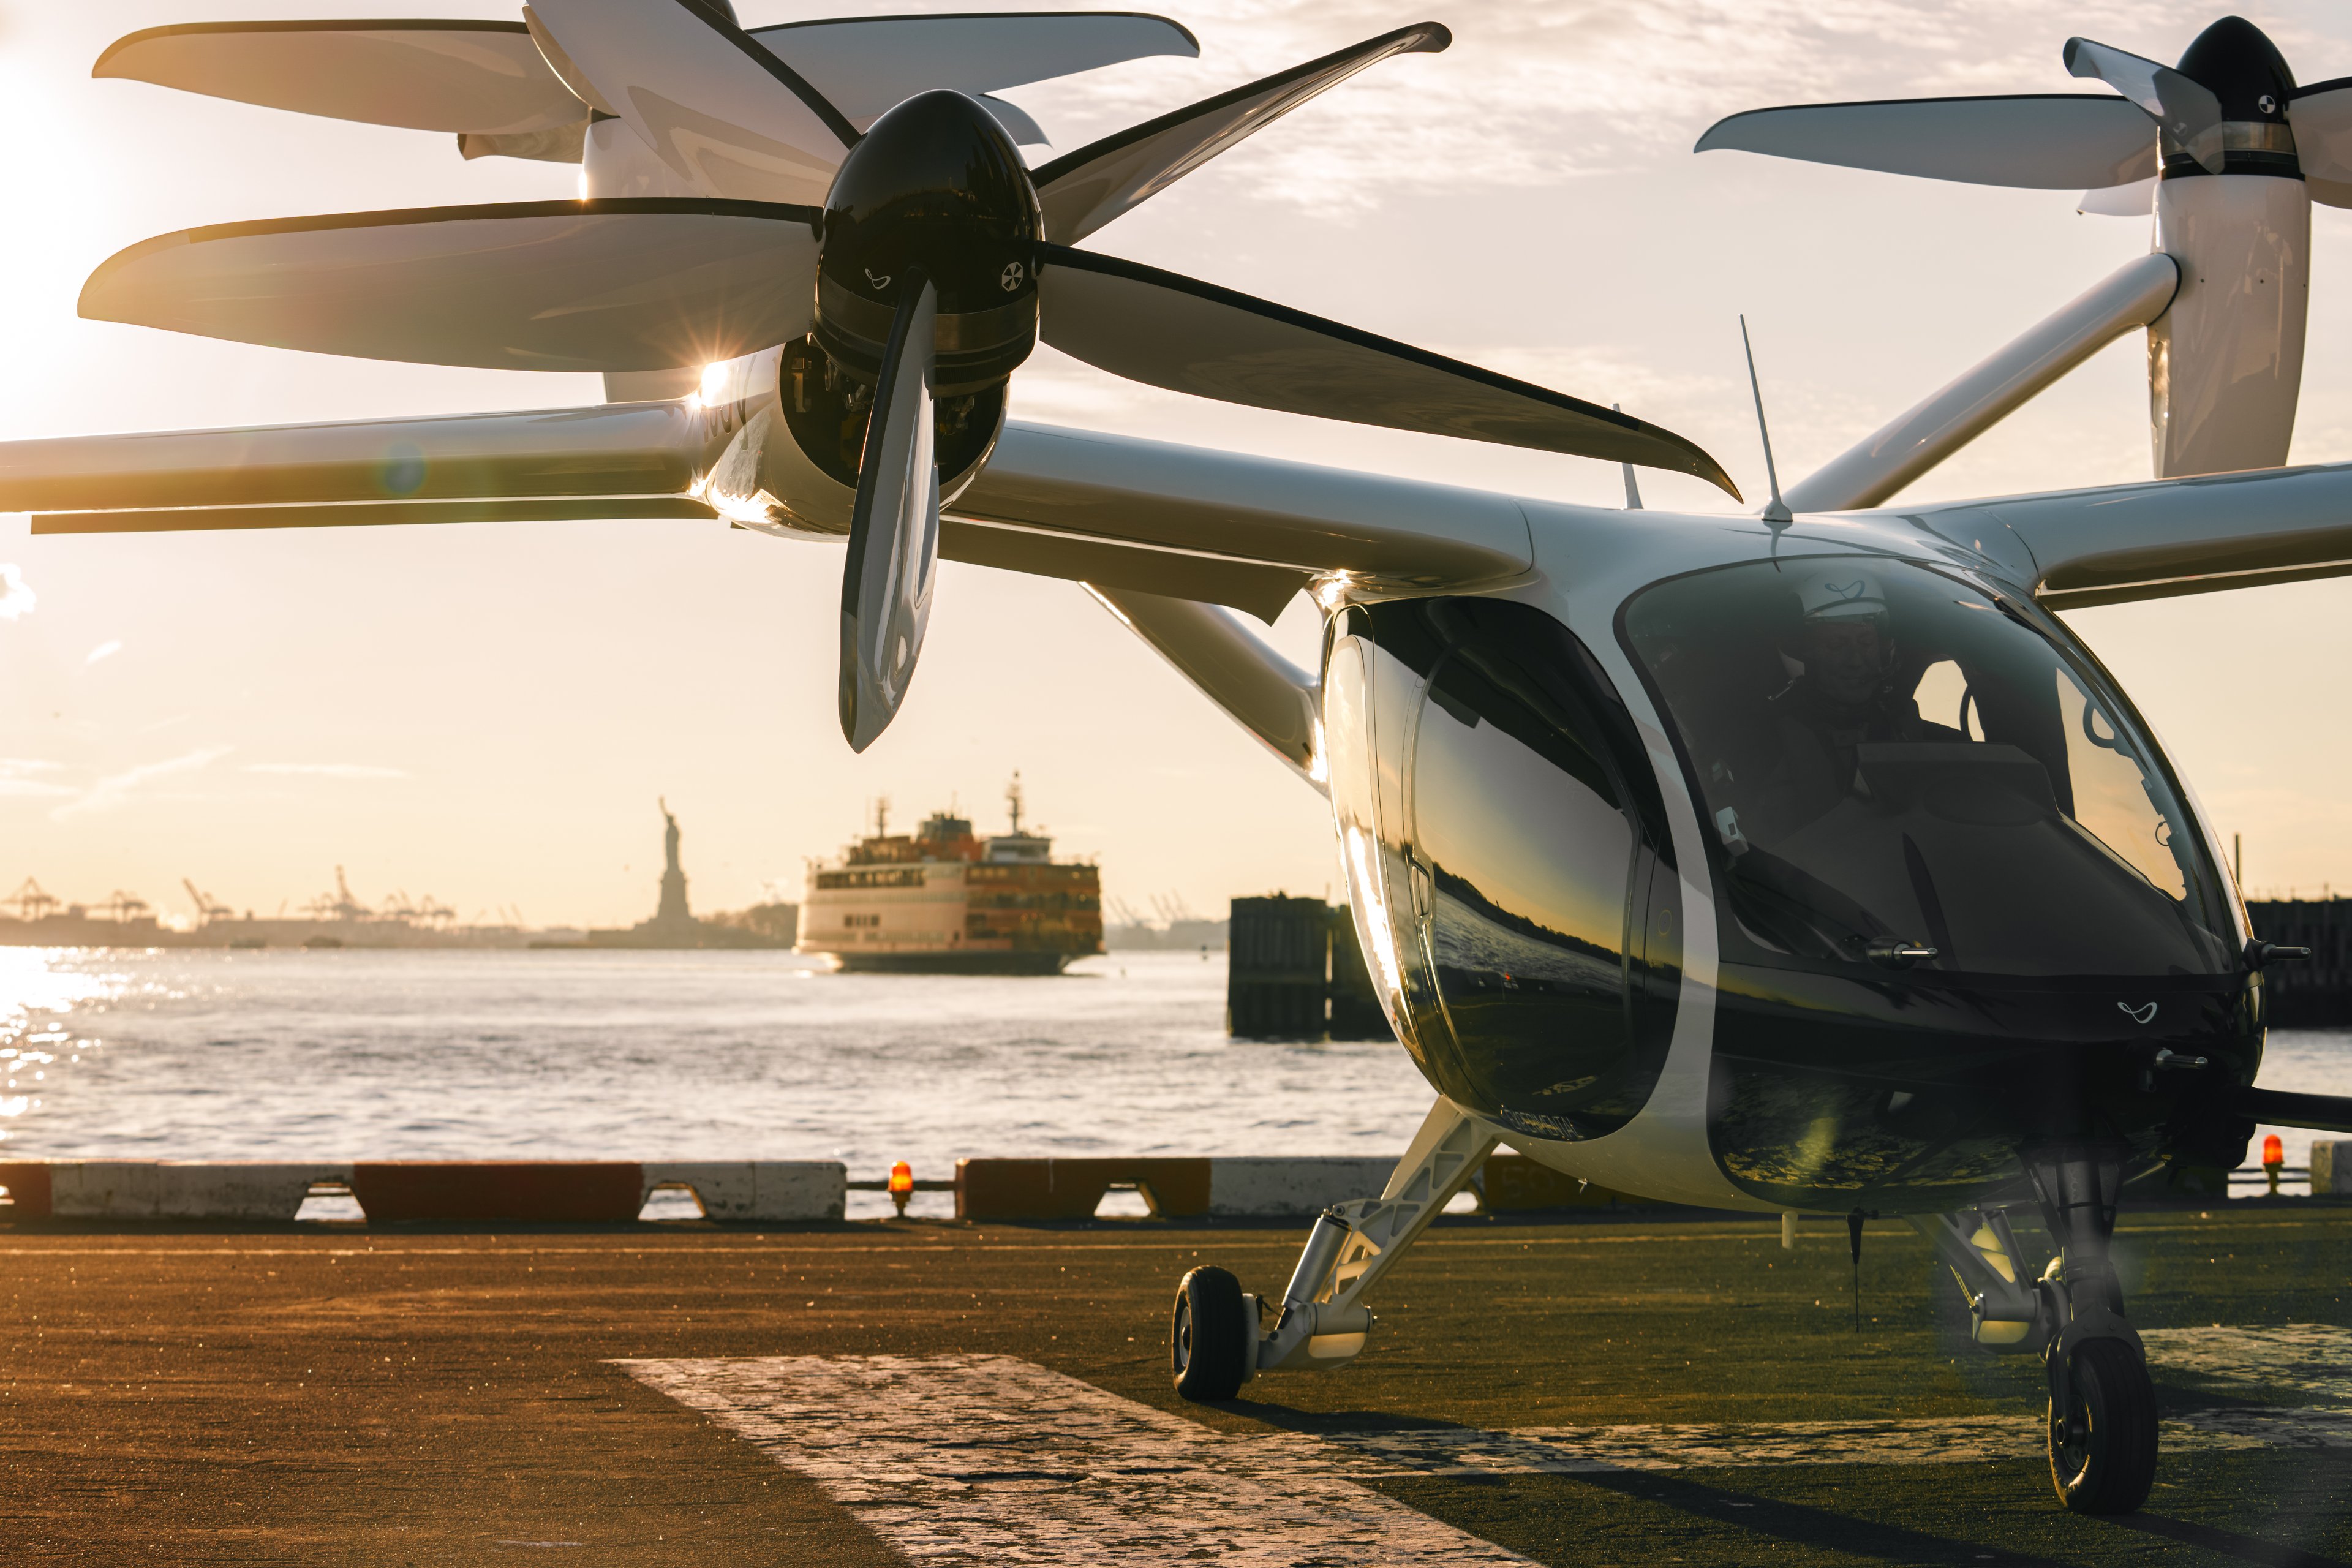
Joby's S4 and Archer's Midnight both carry a single pilot and four passengers. But the S4 travels up to 150 miles on a single charge at a maximum speed of 200 miles per hour, while the Midnight has a shorter range of 100 miles and a lower top speed of 150 miles per hour.
The S4 uses single-tilt-rotor propellers for lifting and cruising. That makes it lighter, faster, and more energy efficient than the Midnight, which uses separate propellers for both tasks. Joby is also developing a hydrogen-powered eVTOL, but Archer isn't.

NYSE: JOBY
Key Data Points
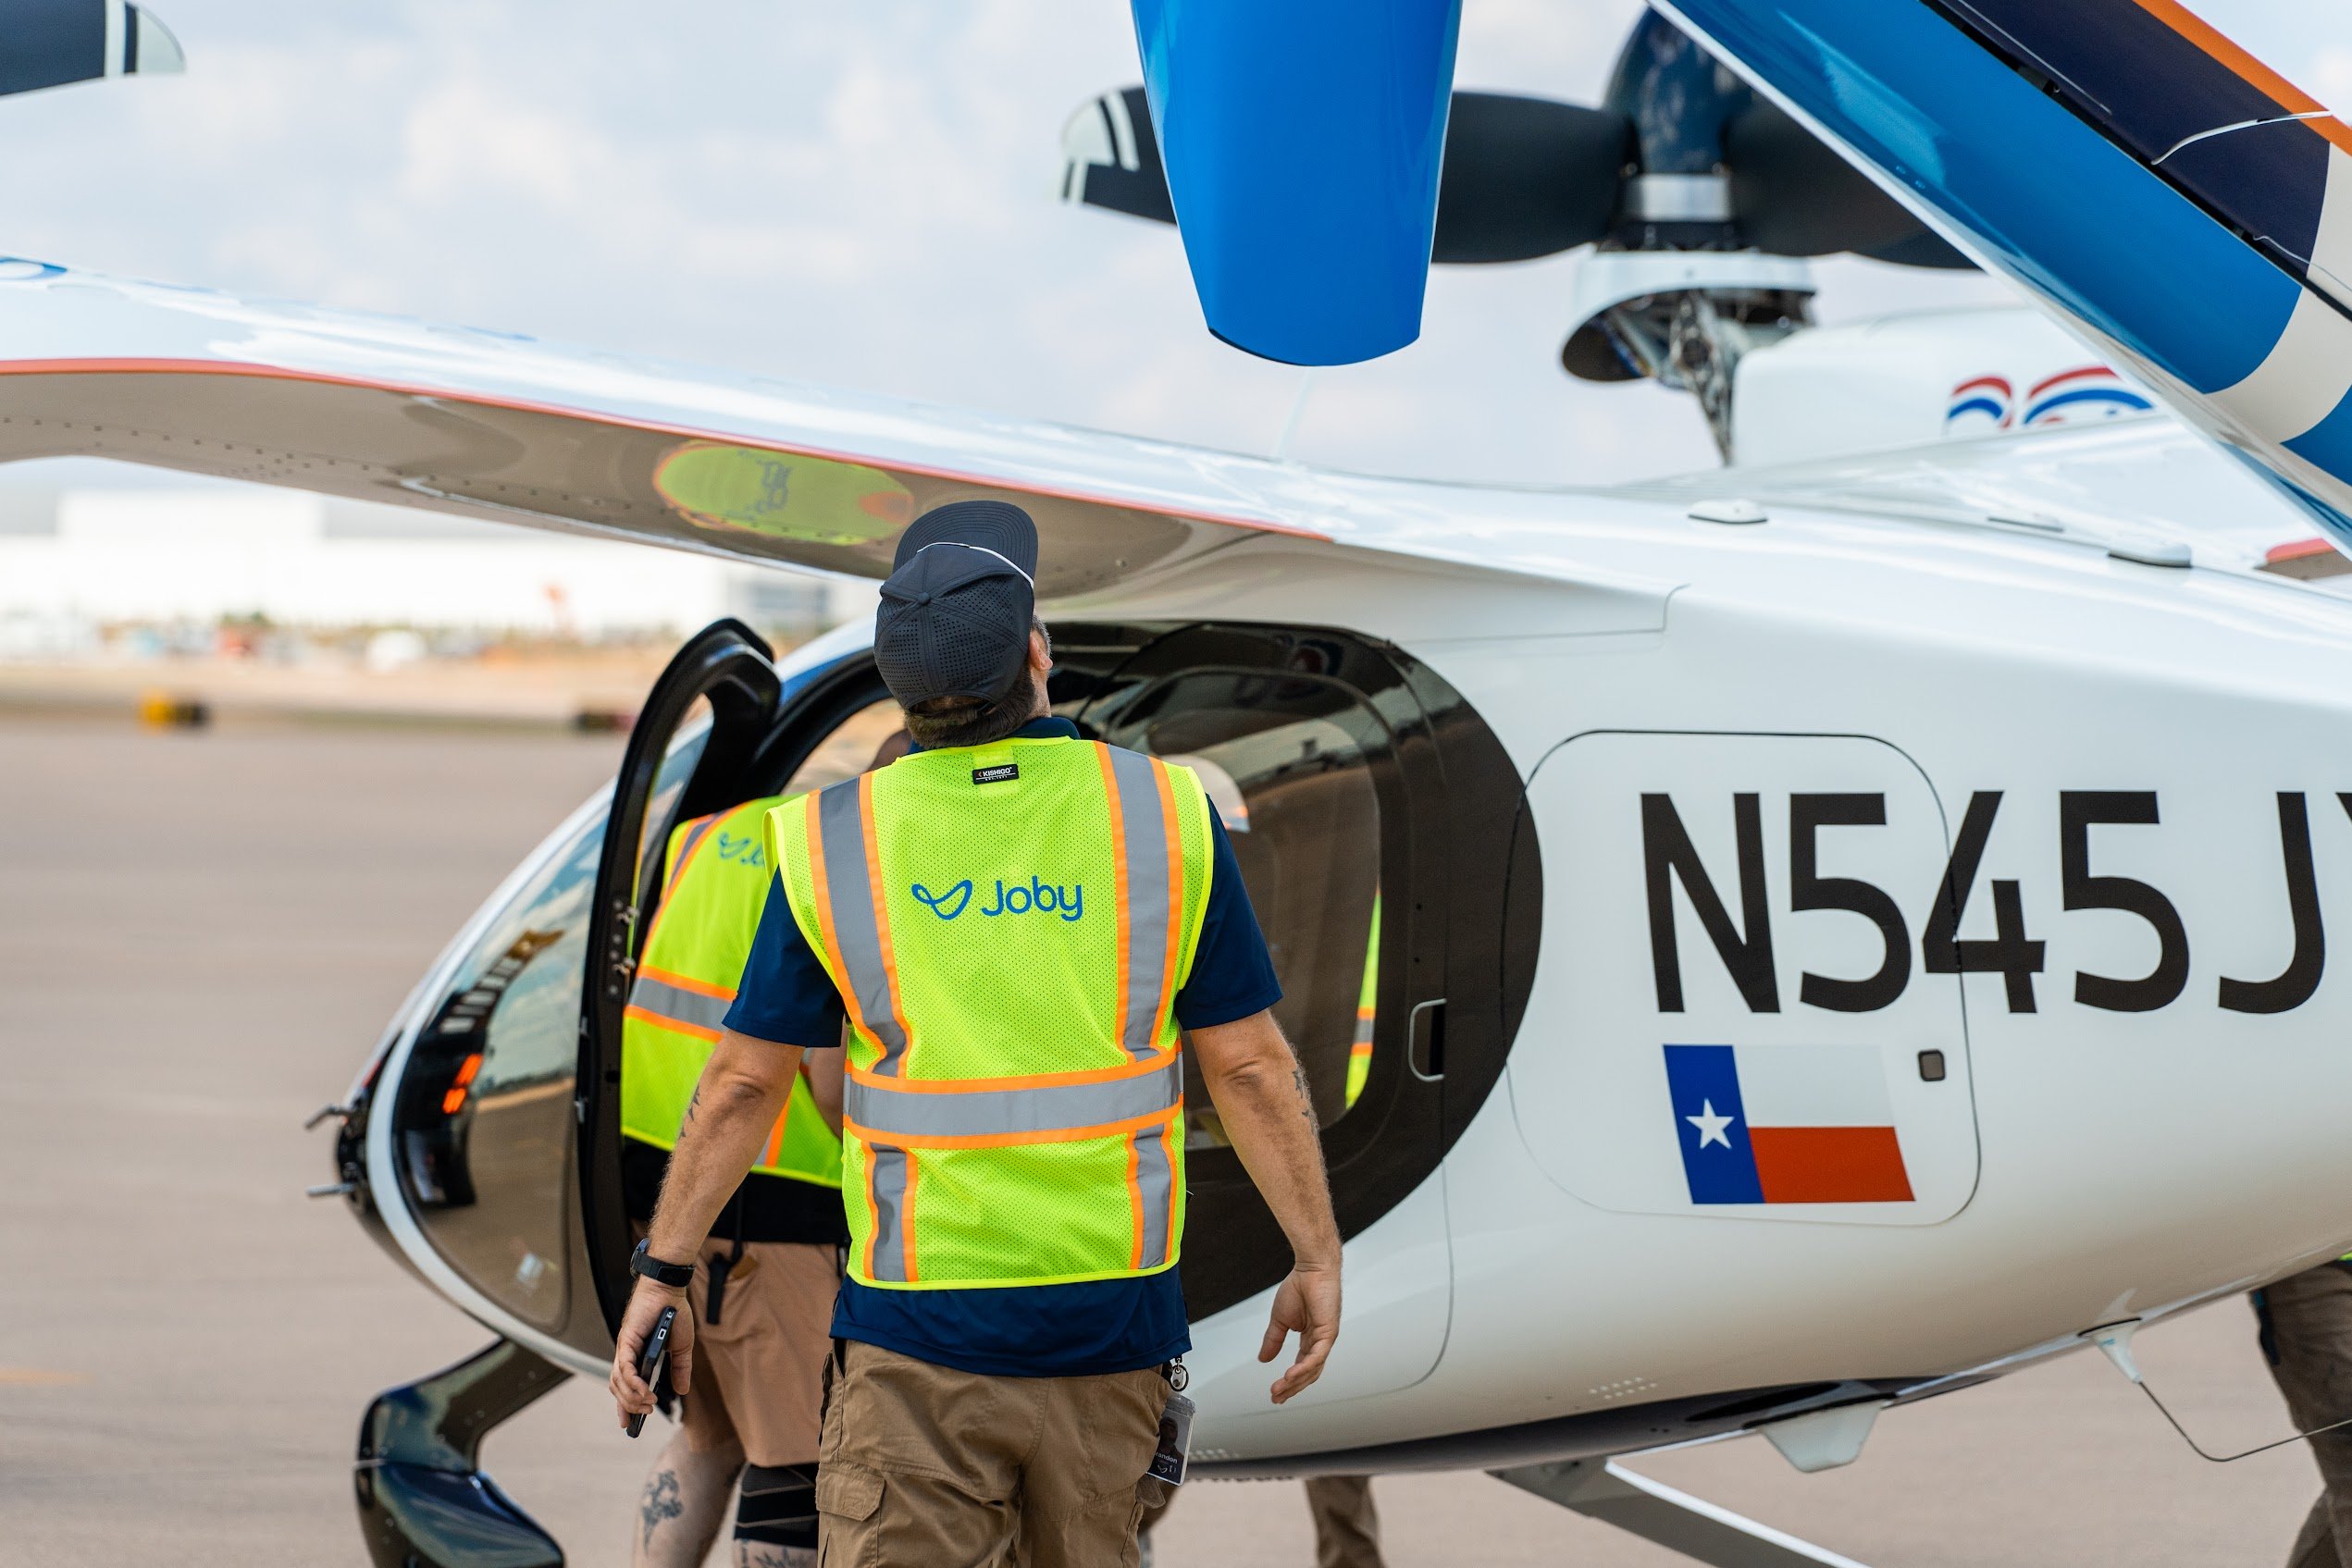
Joby aspires to become a vertically integrated "transportation as a service" provider that manufactures, owns, and operates its own fleet as a first-party air taxi network. To support that expansion and streamline its supply chain, it mainly uses first-party components. Archer plans to become an OEM for other aviation companies and relies heavily on third-party suppliers.
Joby and Archer have plenty of support from big investors and partners. Toyota, Delta, and Uber (UBER +2.01%) back Joby. Stellantis and United Airlines support Archer. Both eVTOL makers also plan to launch their first commercial flights in the U.S. and the UAE.

NYSE: ACHR
Key Data Points
However, Joby is farther along in the FAA's multi-stage certification process than Archer. With some help from Uber -- which plans to integrate Joby's S4 flights into its new Uber Air service -- Joby could expand its commercial flights at a much faster rate than Archer.
Why does Joby deserve a premium valuation?
From 2025 to 2028, analysts expect Joby's revenue to rise from $53 million to $435 million, and Archer's revenue to surge from less than $1 million to $512 million. Archer might generate more revenue than Joby by selling more eVTOLs to other companies. But as an OEM, Archer will naturally have less pricing power than Joby's vertically integrated operator business model.
Archer only trades at 8.5 times its 2028 sales, while Joby trades at 15.5 times that estimate. Archer might seem like the cheaper stock, but it's also a weaker eVTOL maker than Joby. That's why I believe investors should pay a premium for Joby but avoid Archer.