1. ASML’s Demand Problem: Too Much of It
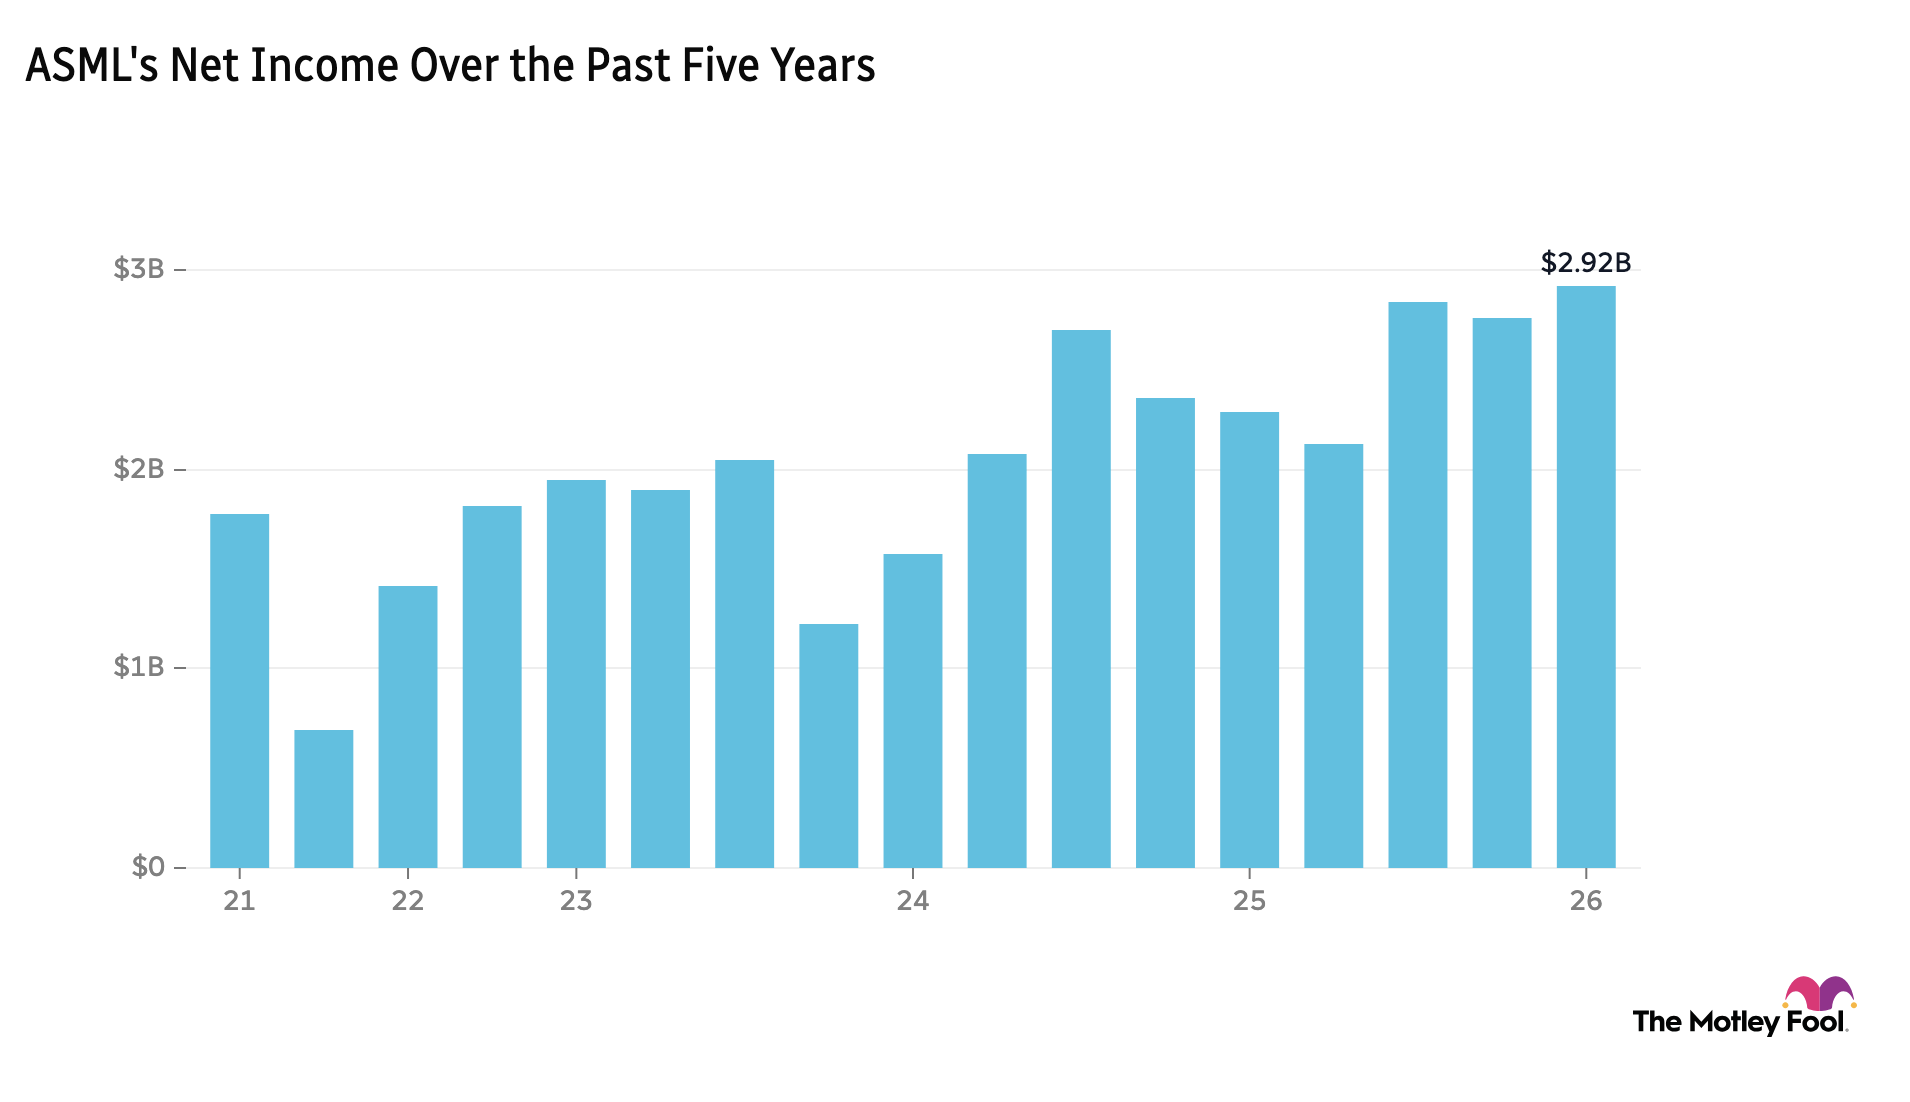
Some of ASML’s (ASML -1.86%) customers want to order machines today that won’t ship until 2029 or 2030. CEO Christophe Fouquet says so himself. ASML, recommended by Team Rule Breakers and Team Hidden Gems, just posted record third-quarter sales and profit. ASML edged down 0.6% in early trading. Team Hidden Gems has a five-year price prediction of $3,229.22.
- Valuations hurt where they shouldn’t: ASML’s shares are up 56% this year. When a stock has run that far, a record quarter with unchanged top-line guidance may disappoint. Yet management raised the lower end of its sales forecast from €43 billion to €44 billion, while keeping the top end at €45 billion.
- A moat with no rival: ASML is the only company that makes extreme ultraviolet machines that etch circuits onto leading-edge artificial intelligence (AI) chips. It has no real competition, and chipmakers have built their factories around its machines. Its previously planned 30% production increases in 2027 and 2028, each, still won’t fully meet demand. That’s a good problem to have for any business.
2. The Big Bank Roundup: Split Signals
Big banking season kicked off with a double dose of drama. Mega-cap lenders posted a mixed bag of third-quarter earnings just as Bank of America (BAC -1.14%) was fined $1.2 billion for compliance and sanctions-screening failures. It admittedly failed to report $5 billion in suspicious transactions.
- Same environment, diverging results: JPMorgan (JPM -0.86%), the largest U.S. bank by assets, posted a rare miss. Goldman Sachs (GS -0.23%), meanwhile, beat expectations on surging equity trading, and Wells Fargo (WFC -3.10%) joined the mix. Citigroup (C -5.60%) tumbled 5.6% after warning its Q4 trading revenue could drop about 20%.
- Ignore trading luck, focus on repeat revenue: Trading profits can swing from quarter to quarter, so they say little about a bank’s long-term worth. JPMorgan’s net interest income rose 13% year over year, and Citi’s services business, which moves cash for corporations and governments, grew 15%. Those are the numbers investors should look at: what’s driving repeatable business and demand.
Next up are Morgan Stanley (MS -1.78%) and Bank of America with their earnings reports today. The latter’s historic regulatory smackdown will wipe out 17 cents per share off its net income. Brace for it.
3. Two Things You Can’t Miss This Week
Two events could set the tone for markets this week. Inflation data arrives today. Earnings from Taiwan Semiconductor (TSM +0.17%), better known as TSMC, follow before tomorrow’s opening bell. Here’s why they matter.
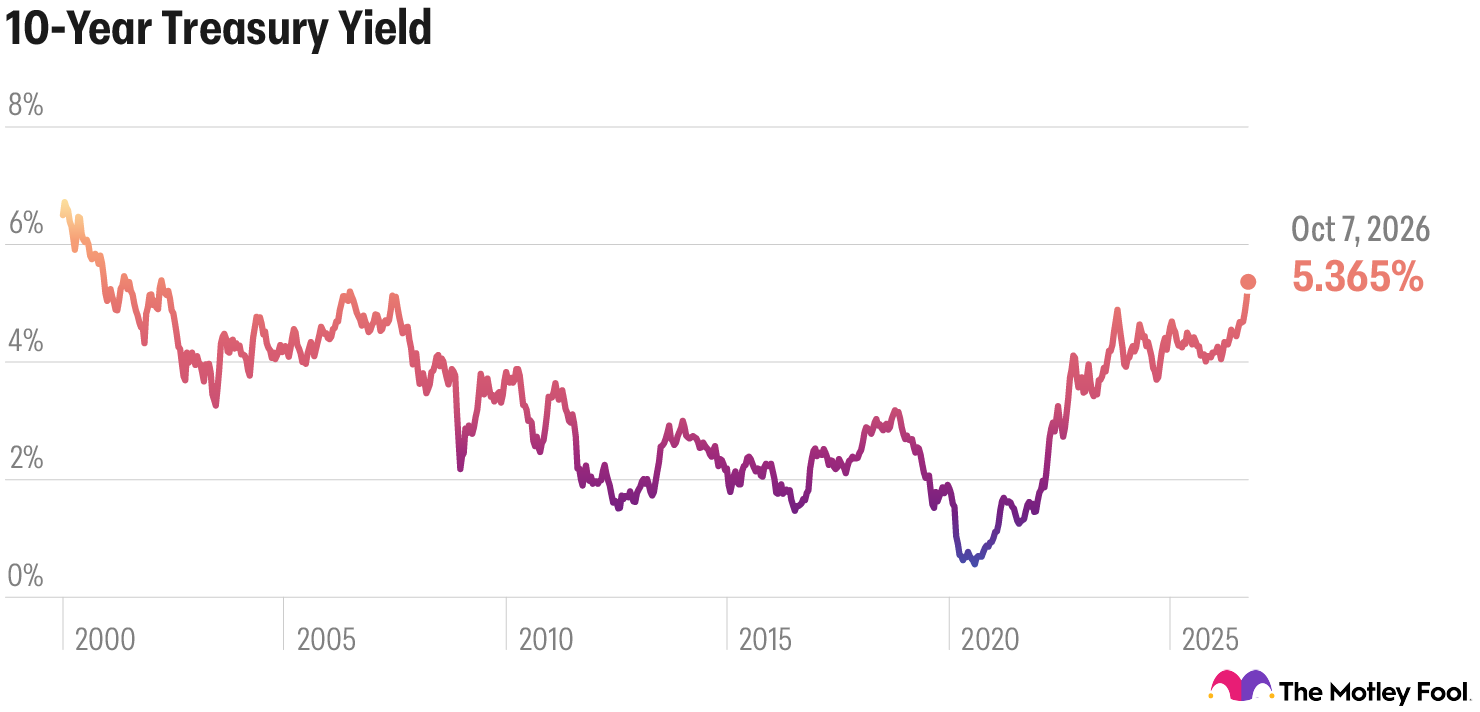
- Inflation may be heating up: Economists expect today’s September Consumer Price Index (CPI) to show a 0.6% monthly price increase and a 3.6% annual jump. That’s further from the Federal Reserve’s 2% goal. Blame the Iran war and energy costs. The Fed raised rates in September for the first time in three years and has said more hikes are likely. A hot inflation number today could hit rate-sensitive and growth stocks that rely on cheap borrowing.
- A sixth straight record? TSMC – the world’s largest contract chipmaker and a Team Hidden Gems rec – is expected to report third-quarter net profit up 65% to about $23.4 billion. AI infrastructure spending and CoWoS packaging technology continue to drive growth. TSMC is spending $265 billion in Arizona. In Texas, it could sublease part of the Terafab AI chip complex that Tesla (TSLA -0.74%) CEO Elon Musk says his companies will build.
4. Buy Now, Pay Later Grows Up
Team Hidden Gems
Team Hidden Gems sees Klarna Group (KLAR -3.46%) reaching $61.55 within five years, nearly five times today's price of about $13. That target may raise eyebrows, because the stock has lost more than two-thirds of its value from our first Team Hidden Gems recommendation at about $45 in September 2025. Klarna helped popularize buy now, pay later, which lets shoppers split purchases into smaller payments. We think the market misjudges this business, and misunderstood companies are our favorite hunting ground.
- Profit beats panic: In Q2 2026, Klarna grew revenue about 27% to roughly $1 billion and posted a $9 million profit, up from a $53 million loss a year earlier. Management did trim its full-year revenue forecast because German shoppers pulled back and its foreign sales converted into fewer dollars. That cut rattled investors, but we see a payments network that just proved it can make money as volume grows.
- Big network, small price: Klarna counted 120 million active consumers in Q2 2026, up about 8% from a year earlier, and J.P. Morgan Payments now offers Klarna at its merchants’ checkouts. Yet Klarna’s market value of about $4.7 billion sits barely above its 2026 revenue forecast of roughly $4.1 billion, so investors pay just over $1 for every $1 of expected sales, a fair price for a growing payments network. Insiders also own about 62% of the company, which gives leadership plenty of skin in the game.
If Klarna keeps turning its growing network into steady profits, we think today’s price will look like a bargain in hindsight.
5. Today’s Question!
A stock you own crashes more than 50%. What will convince you to hold on or even buy more?
Discuss with friends and family, or become a member to hear what your fellow Fools are saying!