Advertiser Disclosure
Many of the offers that appear on this site are from companies from which The Motley Fool receives compensation. This compensation may impact how and where products appear on this site (including, for example, the order in which they appear) and may influence which products we write about, but our product ratings are not influenced by compensation. We do not include all companies or offers available in the marketplace. Websites may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened.
Joel O’Leary is a full-time Personal Finance Writer at Motley Fool Money, covering credit cards, bank accounts, investing, mortgages, and other personal finance topics. Joel has been writing about personal finance since 2018, previously leading editorial content for the How To Money podcast and serving as a resident writer at Budgets Are Sexy. He bought his first rental property at age 18, funding the down payment with savings from his high school job at McDonald’s -- a testament to his lifelong passion for smart money decisions. His work aims to make personal finance accessible and actionable for everyday readers. When he’s not writing, Joel enjoys surfing and spending time with his family.
Many or all of the products here are from our partners that compensate us. It’s how we make money. But our editorial integrity ensures that our product ratings are not influenced by compensation.
Yes, a brand-new LLC can get a business credit card, even with zero revenue and no business credit history.
And I know this for a fact because I did it myself -- twice! About 10 years ago I created two brand-new LLCs for rental properties I was buying. Not only did I get approved for credit cards in the LLC names, but I also got mortgages approved for both.
Most issuers approve small business cards based on your personal credit, not your company's track record. So a business you registered last week can qualify, as long as your personal credit and income check out.
Here's how it works, what you'll need, and how to pick a good first card.
Why a brand-new LLC can still get approved
New companies have no credit history, so card issuers lean on your personal credit score and income to make the call.
You'll need to sign a personal guarantee, which is basically a promise to personally repay the debt if the business can't. That guarantee is what makes issuers comfortable approving a company with no track record.
It can also help to apply where you already bank. If you personally have accounts with Bank of America, for example, then that established relationship may improve your odds and make the process smoother. It's never a guarantee, though, and you'll still need to meet the credit and income requirements.
What you need to apply
It's not too hard to apply for a business credit card as a new LLC. Here's what to have ready:
Your business basics -- name, industry, and how long you've been operating.
Estimated annual revenue -- you can report $0 or a projected number.
A taxpayer ID -- your EIN, or your Social Security number if you're a single-member LLC.
Your personal info -- most new LLCs still enter an SSN so the issuer can run a personal credit check and set up the personal guarantee.
Formation documents -- keep your operating agreement and articles of organization handy, though you usually won't need to upload them.
When I formed my LLCs, I just printed out all my operating documents to show ownership and walked into a branch in person.
You can absolutely put in an application online. But I found it better to sit across from a banker who could answer all of my newbie questions.
Do you actually need a business credit card for your LLC?
A business credit card is worth getting the moment your LLC starts spending money. It keeps business and personal expenses cleanly separated, which makes tax time easier.
It also builds credit in your business's name, so financing gets easier down the road.
Business cards also let you earn rewards on spending you're doing anyway. You're not legally required to have one -- but running LLC expenses through your personal card may cause headaches when you file your tax returns.
What to look for in your first business card
The best first card for a new LLC is simple, costs little or nothing to carry, and rewards your everyday spending.
I recommend getting a card with no annual fee, a straightforward cash back structure, and 0% intro APR if you need to frontload business expenses.
Once your annual revenue and spending grow, you can bump up to premium cards with higher annual fees if it makes sense. But it's best to play it safe when you're starting out.
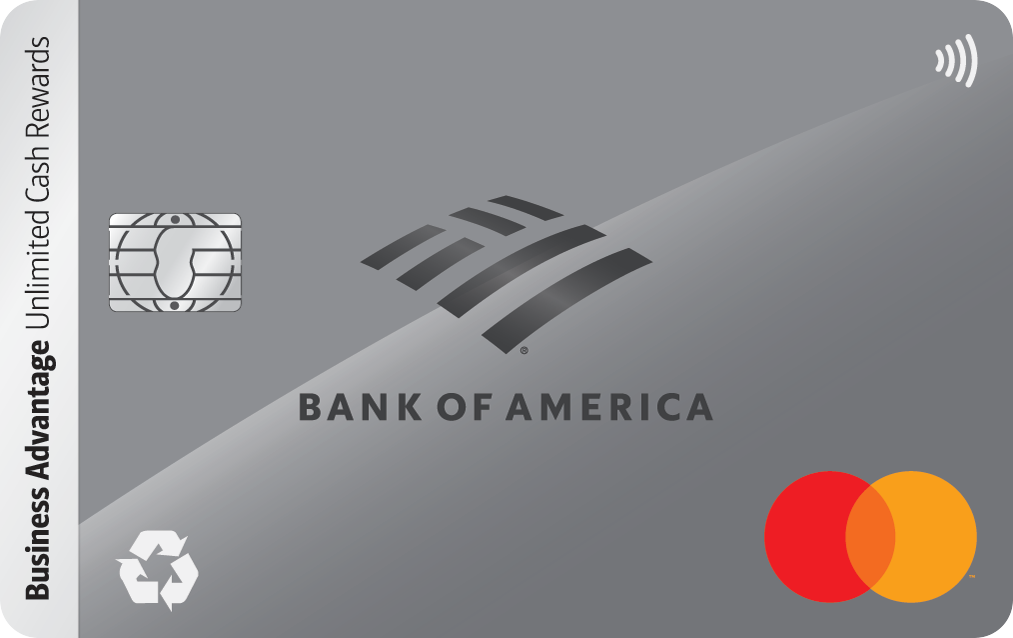
Bank of America® Business Advantage Unlimited Cash Rewards Mastercard® credit card: Best for simple, flat-rate cash back
An easy pick for your new LLC is the Bank of America® Business Advantage Unlimited Cash Rewards Mastercard® credit card.
It earns a flat cash back rate on every purchase, with no categories to track and no spending caps to watch. There's also no annual fee to worry about, which is nice for businesses just starting out and trying to keep costs low.
4.60/5
Our ratings are based on a 5 star scale.
5 stars equals Best.
4 stars equals Excellent.
3 stars equals Good.
2 stars equals Fair.
1 star equals Poor.
We want your money to work harder for you. Which is why our ratings are biased toward offers that deliver versatility while cutting out-of-pocket costs.
= Best
= Excellent
= Good
= Fair
= Poor
Credit Score:
Falling within this credit range does not guarantee approval by the issuer. An application must be submitted to the issuer for a potential approval decision. There are different types of credit scores and creditors use a variety of credit scores to make lending decisions.
Recommended Credit Score required for this offer is: Excellent (740-850)
Credit Score
Falling within this credit range does not guarantee approval by the issuer. An application must be submitted to the issuer for a potential approval decision. There are different types of credit scores and creditors use a variety of credit scores to make lending decisions.
Excellent (740-850)
Intro APR
0% Introductory APR on purchases for your first 7 billing cycles. After the intro APR offer ends, a Variable APR that's currently 16.74% to 26.74% will apply.
Purchases: 0%, 7 billing cycles
Balance Transfers: N/A
Regular APR
16.74% - 26.74% (Variable)
Rewards
Earn unlimited 1.5% cash back on all purchases
1.5% cash back
Annual Fee
$0.00
Welcome Offer
$500 Online Cash Rewards Bonus Offer: Get a $500 online cash rewards bonus after you make at least $5,000 in purchases in the first 90 days of your account opening.
$500 cash back
For businesses that want rewards on every dollar, this card keeps it simple. Earn unlimited 1.5% cash back, a $500 welcome bonus, and 0% Intro APR for 7 billing cycles on purchases (then 16.74% - 26.74% (Variable)), with no annual fee. Qualify for Preferred Rewards for Business and you can boost earnings up to 2.62% cash back.
Unlimited cash back with no expiration
No annual fee
Intro APR
Foreign transaction fees
Mediocre incentives
$500 Online Cash Rewards Bonus Offer: Get a $500 online cash rewards bonus after you make at least $5,000 in purchases in the first 90 days of your account opening.
Earn unlimited 1.5% cash back on purchases, or join Preferred Rewards for Business for no fee, and earn up to an unlimited 2.62% cash back on all purchases if you have a Bank of America® business checking account and qualify for our highest Preferred Rewards for Business tier.
No annual cap and cash rewards don’t expire as long as your account remains open.
No annual fee.
Choose how to redeem your cash rewards – as a deposit into your eligible Bank of America® checking or savings account, as a card statement credit or as a check mailed to you.
0% Introductory APR on purchases for your first 7 billing cycles. After the intro APR offer ends, a Variable APR that's currently 16.74% to 26.74% will apply.
Contactless Cards - the security of a chip card, with the convenience of a tap.
This offer may not be available if you leave this page or visit our website. You can take advantage of this offer when you apply now.
Bank of America content updated on 3/4/26.
If you already bank with Bank of America, your rewards can climb higher through its Preferred Rewards for Business program.
What if your personal credit is limited or poor?
Weak personal credit makes it harder to get a credit card for your new LLC. But you still have options, like secured business credit cards.
With a secured card, you put a security deposit down, and that becomes your credit limit. For example, you can open a secured business card with Bank of America with a $1,000 deposit, and you'll be given a $1,000 credit limit.
With consistent, on-time payments, you could improve your business credit over time and get approved automatically for a higher limit.
Best of all, you can still earn rewards along the way.
Getting your first card is easier than you think
If you just formed an LLC for your new business, don't be nervous about applying for a small business credit card.
You can still be approved for a card, based on your personal credit and a personal guarantee.
No. You don't need an LLC to get a business credit card. Sole proprietors, side hustlers, freelancers, or anyone with 1099 income can qualify. You can apply using your Social Security number instead of an Employer Identification Number.
You can apply as soon as your LLC is registered and you have an EIN or SSN. Issuers don't require any minimum time in business, so a company that's a few days old can qualify.
Usually, yes -- at least at first. Applying triggers a personal credit check, which can cause a small, temporary dip. After that, some issuers report business card activity to your personal credit and some don't, so check the issuer's policy.
Share This Page
We're firm believers in the Golden Rule, which is why editorial opinions are ours alone and have not been previously reviewed, approved, or endorsed by included advertisers. Motley Fool Money does not cover all offers on the market. Motley Fool Money is 100% owned and operated by The Motley Fool. Our knowledgeable team of personal finance editors and analysts are employed by The Motley Fool and held to the same set of publishing standards and editorial integrity while maintaining professional separation from the analysts and editors on other Motley Fool brands.
Terms may apply to offers listed on this page.
Motley Fool Stock Disclosures
Bank of America is an advertising partner of Motley Fool Money. Joel O'Leary has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Mastercard. The Motley Fool has a disclosure policy.
The Motley Fool owns shares of and recommends Mastercard.