At his keynote speech at Jackson Hole, Wyoming, on Aug. 28, Fed Chair Kevin Warsh struck a different note from his predecessor, Jerome Powell, promising "a quieter Fed" in which the market wouldn't get as much telegraphing of how the central bank planned to act on its interest rate decisions. Investors read his tough talk on inflation during that same speech as a (not-so-quiet) signal that a hike was coming. In keeping with what was overwhelmingly expected, the Fed dutifully hiked rates on Sept. 16.
For the S&P 500 (^GSPC -0.02%) and Nasdaq Composite (^IXIC +0.01%), the rate hike was met with only modest trading volatility, while the Dow Jones Industrial Average (^DJI -0.31%) fell 1.21%.
But generally speaking, Warsh seems to want the markets to follow the Fed's decisions rather than front-run them, which means the future is likely to be more volatile, not less. Let's unpack why that's the case.
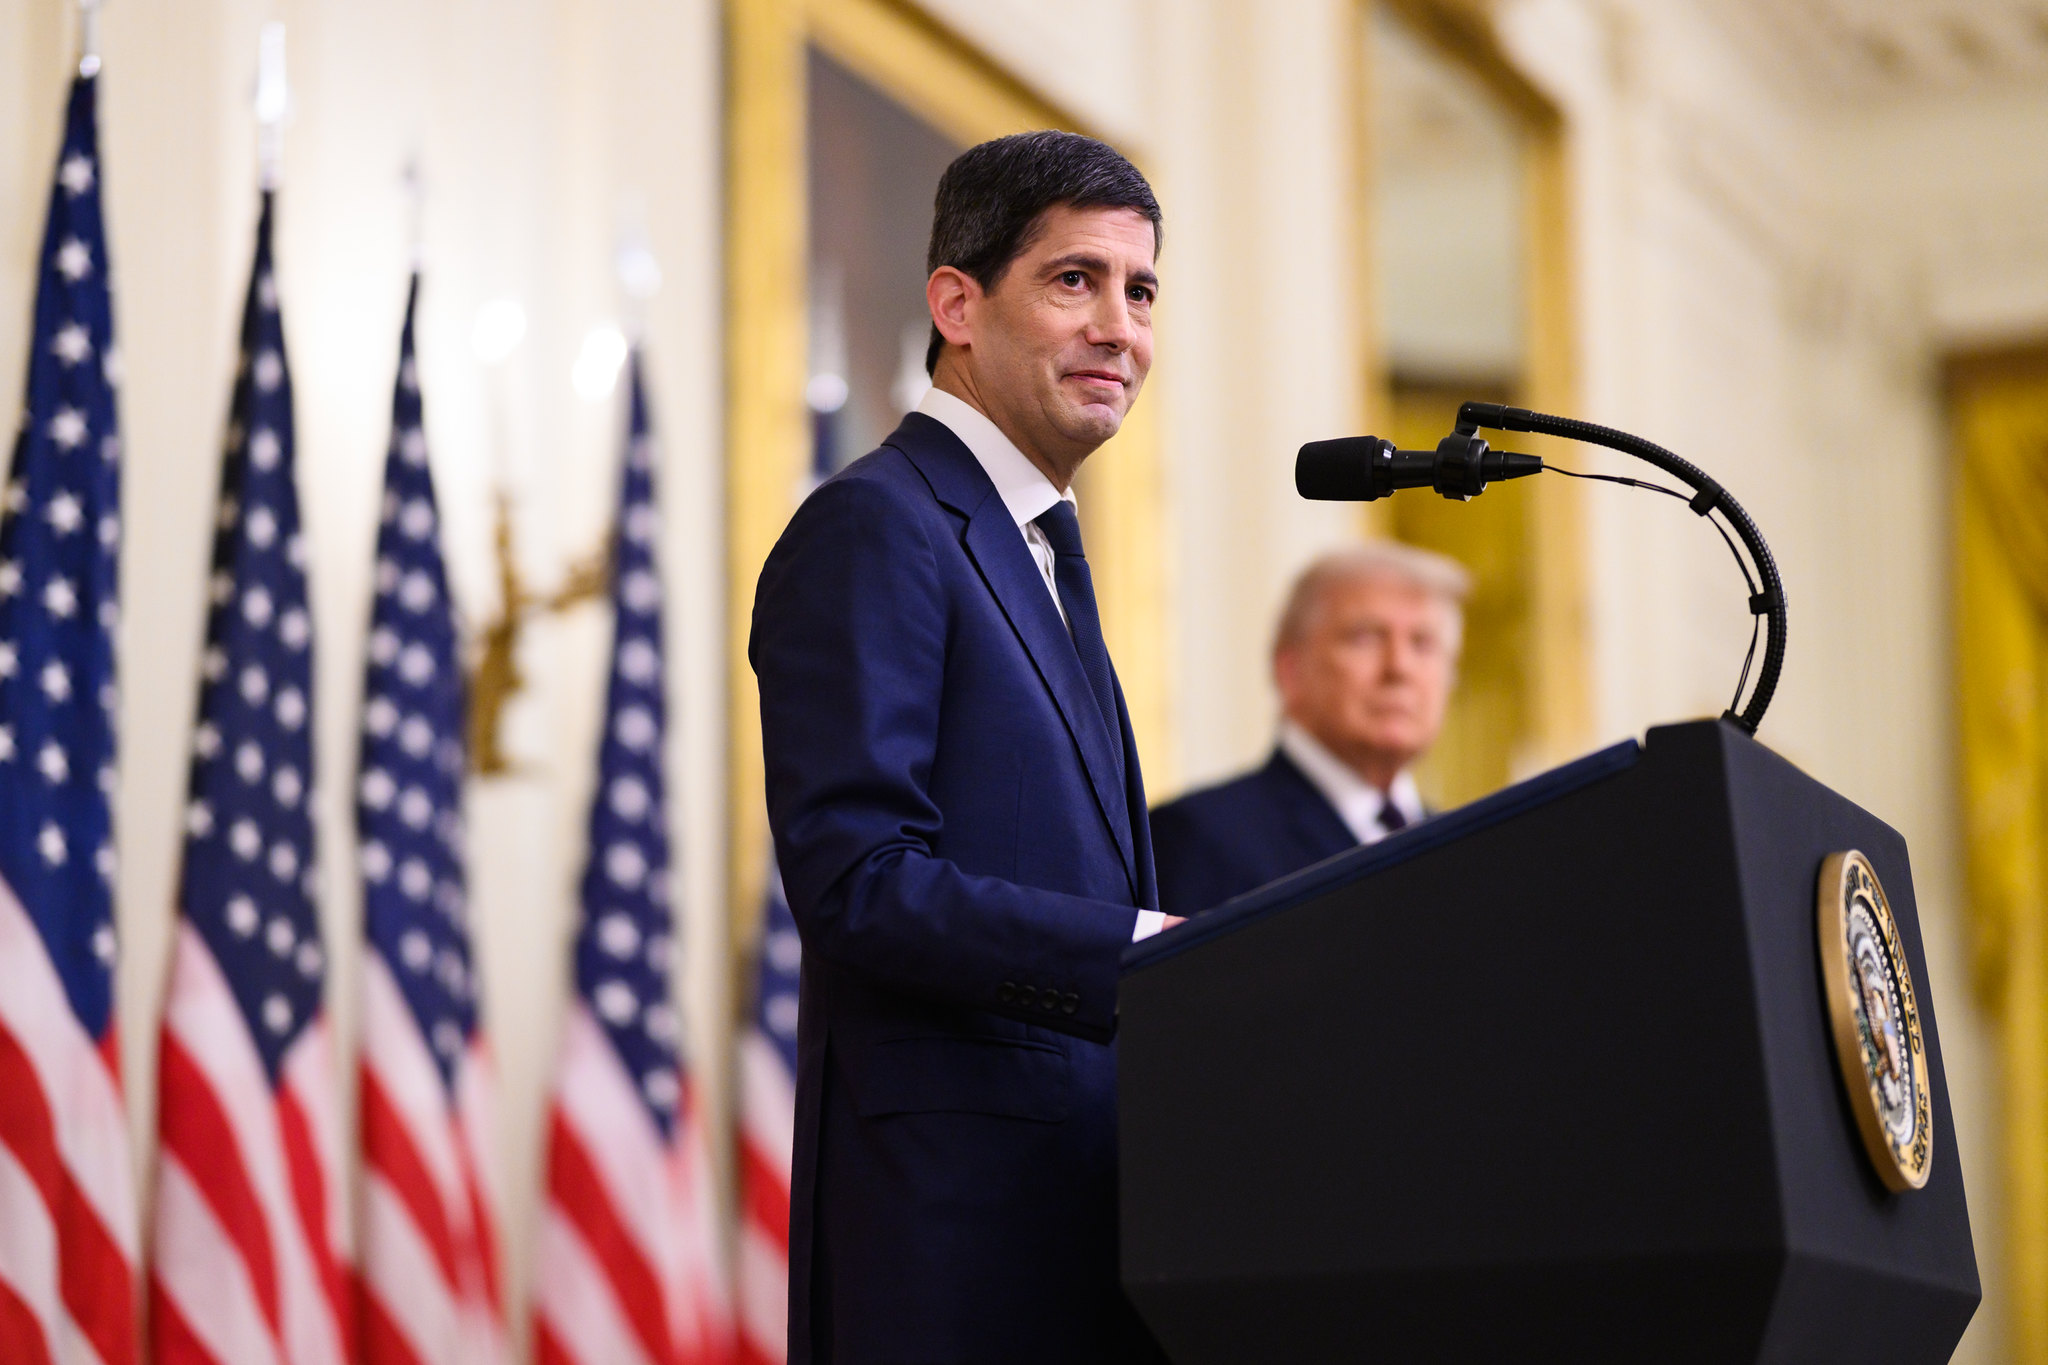
Image source: The White House.
Less signaling means more surprises
The point of doing things the way Powell did was to prevent a surprise: the market expected a certain action from the Fed, but the Fed took a different action, which could cause prices to whipsaw in a disorderly fashion. According to research from the Kansas City Fed, rate uncertainty decreased shortly after the central bank adopted date-based guidance in 2011.
By saying that it will be depriving the market of future guidance, the Fed is thus inviting some of this volatility-producing uncertainty while also redistributing some of the potential for volatility from being concentrated around the day of the rate decision's publication to being somewhat more distributed across the economic data reporting days (in addition to the rate decision day).
S&P 500 Index
Key Data Points
It's also redistributing some of the volatility from stock prices toward bonds. The MOVE index, a gauge of bond volatility, climbed to 80.6 on Sept. 18, 23% above its June lows, and it might not be done climbing.
So in a diversified stock-and-bond portfolio, bonds might be a bit less of a bedrock of stability going forward.
NASDAQ Composite Index
Key Data Points
The dot plot still exists
Despite its new approach, the Fed's Sept. 16 projections showed 16 of 18 officials expecting another rate hike in 2026. In other words, the dot plot still hands the market a guide to the Fed's preferred course of action, for now, which limits how much extra volatility the quieter approach could create.
Dow Jones Industrial Average
Key Data Points
Still, future policy changes could diminish or entirely remove any signaling from the Fed. That could certainly juice volatility in situations where the market lacks a strong consensus on whether a rate hike or a rate cut is the most likely next action, such as when economic data are conflicting. Rate-sensitive investments, such as tech stocks and crypto, would be the most exposed to the turbulence.
If the macro conditions become less obviously inflationary, there could be a bit more volatility related to the Fed's choices. Until then, expect more rate hikes.