On Oct. 12, 2026, one share of Wendy's (WEN +0.40%) costs $6.31. That's less than an $8 Baconator, and I mean just the sandwich, not the meal. If your local drive-through accepted payment by stock certificates, you would still have to add some change if you wanted a $7.30 Dave's Double.
That doesn't mean it's time to double down on Wendy's stock. A low share price doesn't necessarily mean anything, and this burger chain looks affordable for a reason.
Someone edited the recipe card
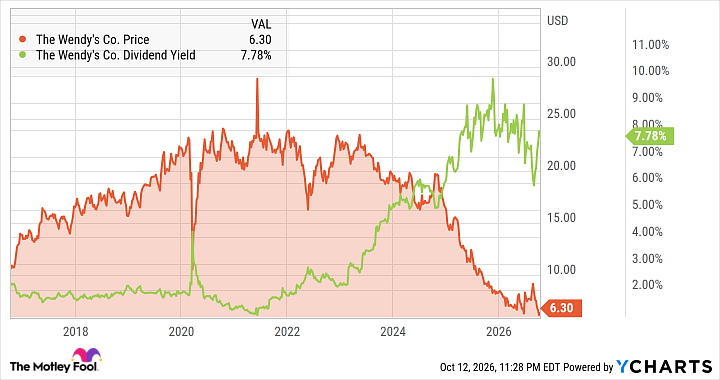
Wendy's stock has lost 65.6% over the last three years. Around early 2024, the share price began to fall while the dividend yield began to rise. That combination looks tasty on a stock screener, but a yield inflated by a falling price often signals financial trouble and a rough road ahead.
At this point, Wendy's stock trades at just 9.6 times trailing earnings and 4.6 times free cash flow. The low P/E ratio comes with some fine print. Wendy's has a $1.2 billion market cap but a $4.8 billion enterprise value, thanks to a hefty debt load. Buyers of the stock get a small bun of robust free cash flow wrapped around a very large patty of debt.
New CEO Bob Wright is well aware of the company's troubles. He started at Wendy's 28 years ago, worked alongside founder Dave Thomas, and later rebuilt Potbelly's menu while growing sales by more than 40% in five years.
But this won't be an easy turnaround. On his first earnings call, Wright said cost-cutting decisions had weakened the quality that once defined the brand. That's a striking admission from a chain whose longtime slogan was "Quality Is Our Recipe."
Image source: Getty Images.
Customers noticed
Wendy's cut its quarterly dividend from $0.25 to $0.14 in May 2025, then cut it again to $0.07 in August 2026. Many data sources still show a trailing yield near 7.8%, but the new payout works out to a forward yield of about 4.4%.
The dividend cuts reflect real operational problems. In the second quarter of 2026, U.S. same-restaurant sales fell 7% and customer traffic dropped 12.5%.
On the earnings call, CFO Steve Cirulis said that July traffic was no better. Wendy's closed 289 U.S. restaurants in the first half of 2026, and more closures seem likely. The company is in full turnaround mode, led by proven crisis-fixer Wright. If you lost count, that's Wendy's fourth CEO since February 2024.

NASDAQ: WEN
Key Data Points
Wait for the new menu
The low valuation ratios are either no-brainer buying opportunities or red flags with sparklers and neon lights. In Wendy's case, Wright faces a tough task. A loss of reputation for quality is a significant factor in the company's downturn.
So until this recovery project shows results, Wendy's stock looks cheap for a reason. The single-digit stock price is a red flag, not a buying window. Wright gets a chance to change my mind when Wendy's reports Q3 earnings on Nov. 5. I'll pay close attention to his second earnings call.