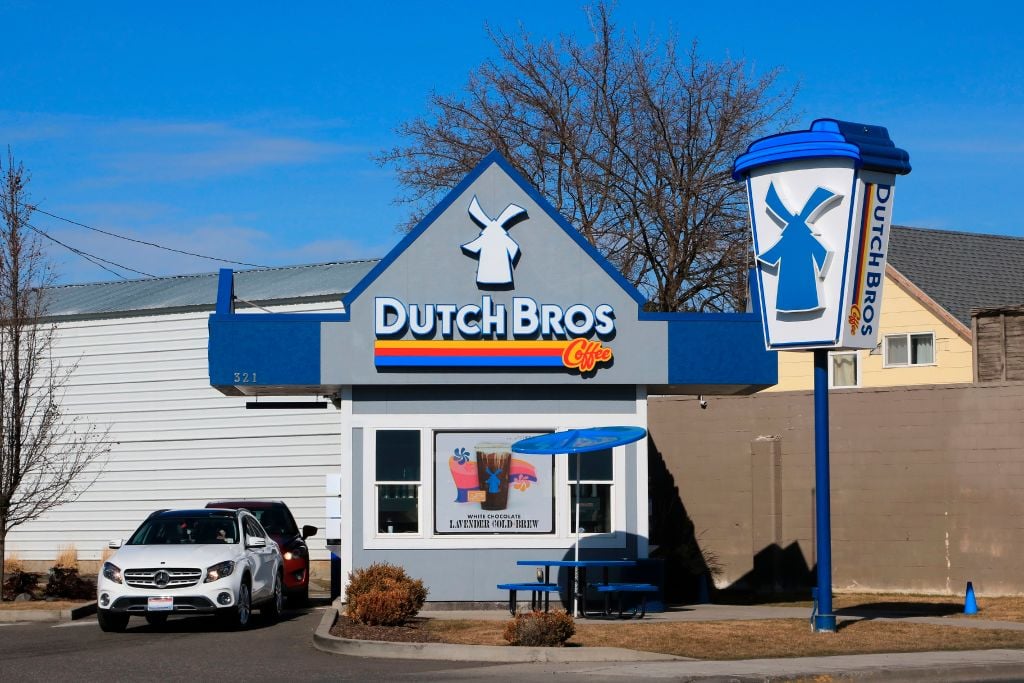
When it comes to the retail coffee industry, investors probably think of Starbucks first. While this business has a strong position in the market on a global level, there is a popular smaller rival finding success domestically.
Enter Dutch Bros (BROS +0.13%). It's rapidly expanding, making it an exciting story in the competitive industry. If you buy this growth stock today, here's where it could be in five years.

Image source: Getty Images.
Leaning on an obvious growth engine
As of March 31, there were 1,177 Dutch Bros locations nationwide. That figure has expanded dramatically from 441 stores at the end of 2020. The business is clearly seeing an opportunity to keep growing, as it evolves from only having a stronghold in the western U.S. to a national footprint.
The company's biggest growth engine is, unsurprisingly, opening new stores. The leadership team believes it can reach 2,029 coffee shops by 2029. And over the very long term, Dutch Bros believes the U.S. has room for 7,000 locations.
That should support higher revenue. This is especially true, given that systemwide same-store sales were up 8.3% in the first quarter, during a period of high economic uncertainty.
Meanwhile, the business is shifting its strategy to capture greater sales. For example, Dutch Bros' new food program was in 485 stores in the first quarter. This effort "continues to perform exceptionally well," according to CEO Christine Barone.
Given estimates that just 2% of sales come from food, there is potential for this to become a more meaningful contributor to the top line. This is the case for the morning, when consumers want to grab food with their coffee on the way to work.

NYSE: BROS
Key Data Points
Earnings power should drive stock returns
The consensus view among sell-side analysts is that Dutch Bros will report adjusted diluted earnings per share of $1.53 in 2028. This estimate would be 101% higher than the $0.76 it posted in 2025, translating to a superb compound annual growth rate of 26.3%.
A potentially higher profit pool in the future is key to the investment thesis with this business. The bottom line is a powerful fundamental driver for any company. But given that Dutch Bros is earlier in its lifecycle, the upside is significant.
And that's why the current valuation, which is expensive, matters less. Shares trade at a forward price-to-earnings ratio of 74.6. The stock price is trading at 43.5 times the 2028 forecast, however.
Investors looking to buy this stock with a five-year time horizon are staring at an attractive opportunity to achieve market-beating returns. There's a chance this stock doubles between now and June 2031.
It all depends on Dutch Bros' ability to continue executing well. Because the business is reporting strong financial results right now, there's little reason to think it won't be able to keep up the momentum.