A number like $104 billion is pretty big -- especially when that's how much revenue you have in your backlog. CoreWeave (CRWV +1.19%) buys advanced chips from Nvidia, installs them in data centers, and rents out computing power to the companies building and running artificial intelligence (AI). The company had $104 billion in its backlog at the end of June.
These remaining performance obligations (RPO) are a big part of why so many investors still see the neocloud as a huge opportunity even with its stock up 115% from its 2025 initial public offering (IPO). So, are these bullish investors right?

NASDAQ: CRWV
Key Data Points
Demand is clearly still strong, but delivering on that RPO takes an incredible amount of money. So, what does the future hold for CoreWeave? And where will CoreWeave stock be in five years?
Revenue growth and a $104 billion backlog
CoreWeave is growing like crazy. The company brought in $2.58 billion in its most recent quarter, more than double what it made a year earlier. Check out the top-line growth in the chart below.
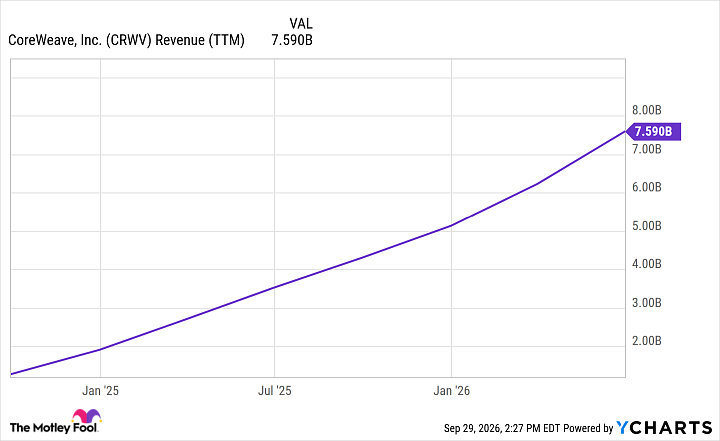
CRWV Revenue (TTM) data by YCharts.
And of course, CoreWeave's backlog is $104 billion in promised revenue it hasn't counted yet. Oh, and CoreWeave has said it signed an additional $25 billion in commitments early in the current quarter.
Of course, to count that revenue, CoreWeave has to actually make good on its commitments. And that takes a whole lot of cash.
Negative free cash flow and heavy borrowing
In its last quarter, CoreWeave generated $679 million in cash from operations but spent $6.4 billion on property and equipment. Its free cash flow -- the money left after running the business and making investments -- was a negative $5.7 billion. To fund that gap, CoreWeave is borrowing heavily -- this is a core feature of its scale-as-fast-as-possible business model.
It had roughly $35 billion in debt at the end of June, up from about $21 billion at the end of 2025. And it's not cheap debt. CoreWeave has issued bonds carrying interest rates above 9%, while some of its other loans have floating rates. If rates rise -- they currently are -- those floating-rate payments will rise with them.
As of last quarter, net interest expense was $640 million -- just $39 million less than it generated from operations.
Wall Street's wide range of price targets
Trying to predict how this will all turn out is hard. Serious growth mixed with serious risk is hard to model, and that's why Wall Street is all over the place on the stock. Here are a few price targets:
| Firm | Target |
| Bernstein | $74 |
| JPMorgan | $125 |
| Rosenblatt | $250 |
Of course, these are one-year targets, not five.
My five-year outlook for CoreWeave stock
In my view, CoreWeave is walking a financial tightrope. It's a model that could pay off handsomely but only if things go just right. That success is entirely dependent on two interrelated forces completely outside the company's control: interest rates and AI demand.
Image source: Getty Images.
I think it's more than likely that within five years there will be a significant contraction in AI spending, fueled in part by rising borrowing costs. And that will not be good for CoreWeave or its stock. Five years from now, I think CoreWeave stock will trade much lower than it is today.
Of course, if I am wrong, and interest rates retreat, and the AI boom continues at its current pace, CoreWeave will have done very well for itself.