Apple (AAPL -1.11%) has changed significantly since Tim Cook took over as CEO in August 2011. He recently retired from the role, becoming executive chair.
Cook didn't have an easy task, taking over for the legendary co-founder Steve Jobs. But he oversaw tremendous growth in the business.
Shareholders certainly shouldn't have any complaints. Over the past 15 years, Apple's stock has returned 2,720%, including dividends. That beat the S&P 500 index's 758.8%.

NASDAQ: AAPL
Key Data Points
It's important to take a look back to analyze Apple's revenue growth and composition. That way, investors can make a determination about Apple's future growth prospects under new CEO John Ternus.
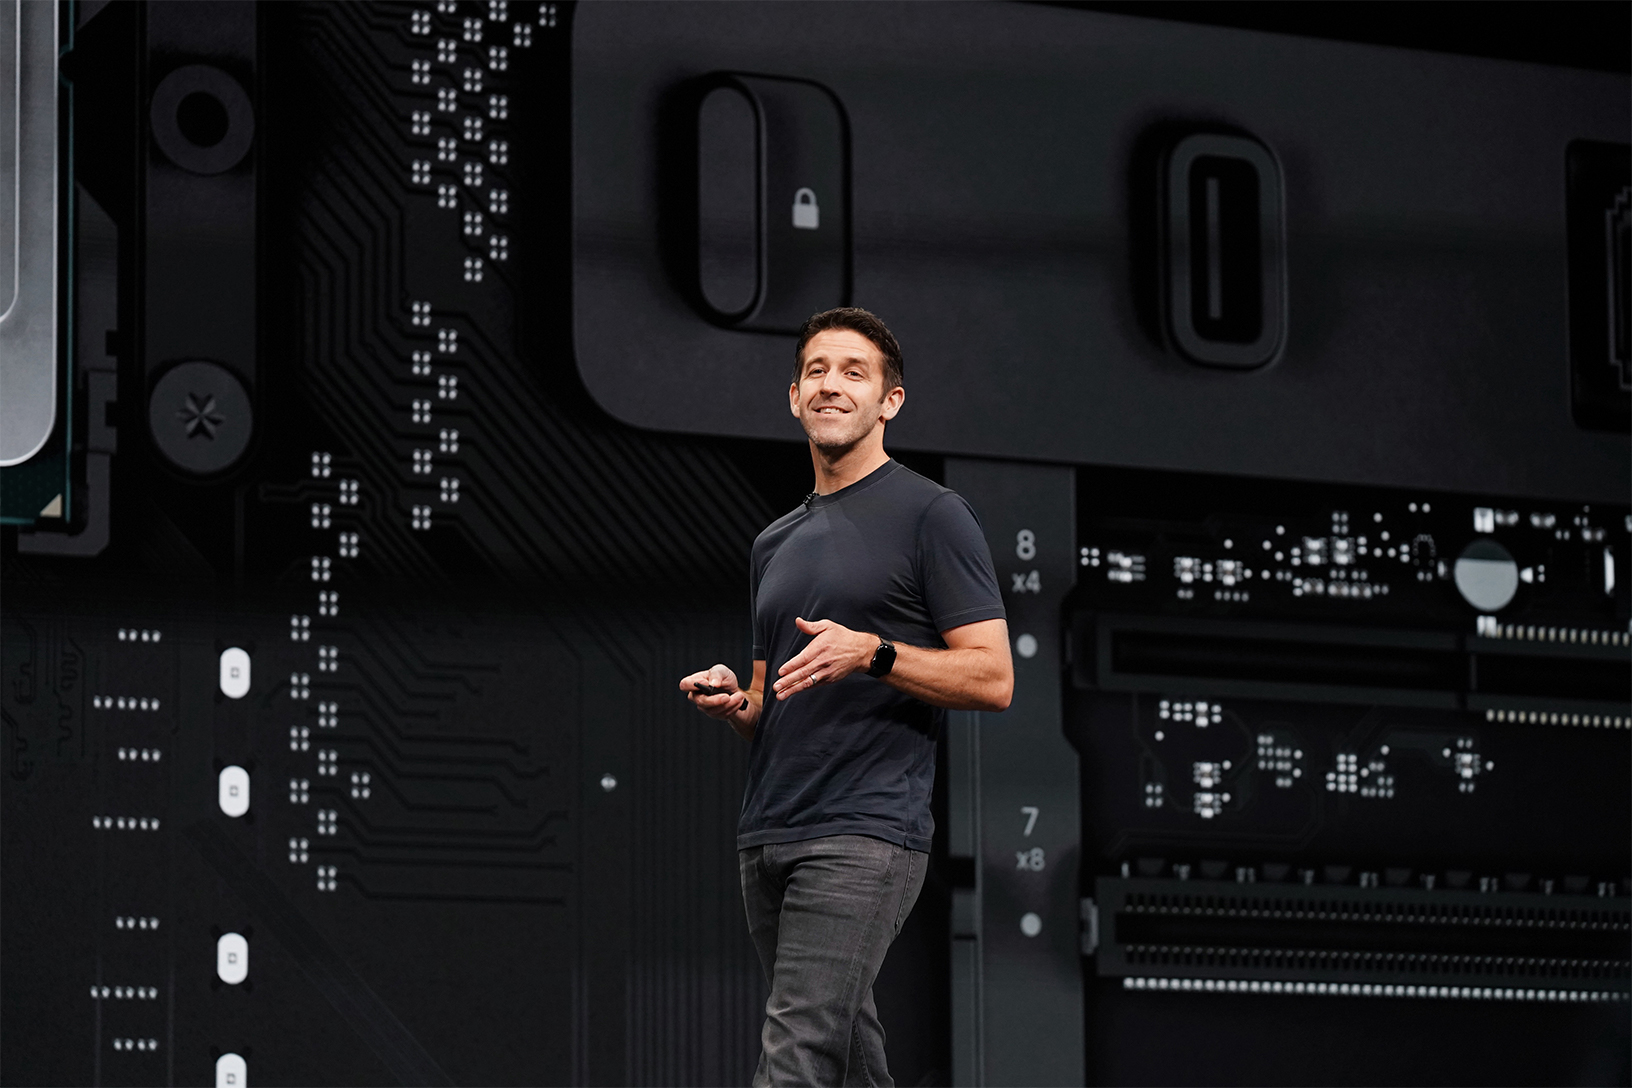
Apple CEO John Ternus. Image source: Apple Inc.
The changing revenue composition
Cook conducted his last conference call as CEO on July 30, discussing fiscal third-quarter results for the period ended on June 27. Here's an analysis of the sales growth.
Apple's quarterly revenue reached $109.4 billion, up 16% year over year. That's largely driven by iPhone sales. The product's sales, which made up about half the company's top line, grew 22% to $54.3 billion.
The higher-margin services business, which includes advertising, support services, the App Store, and payment services, is also growing nicely. Services (28% of sales) saw a 12% sales increase.
Cook oversaw tremendous growth, and the iPhone business became a much larger share of the business. For all of fiscal 2011, Apple had sales of $108.2 billion, with the iPhone representing $47.1 billion, or 43% of the total.
Future growth opportunities
The company Ternus leads will need to rely on the iPhone for sales growth for a while, given its large share of the top line. Most immediately, Apple launched the iPhone Duo, a foldable phone with a high price of $2,000. Investors will judge the initial success when the company reports fourth-quarter results.
Long-term, Apple will need to produce other products. After all, no company, no matter how successful, can rely on just one product.
Its recent track record hasn't been great, which Ternus will undoubtedly try to change. That includes an expensive failed attempt to commercialize a self-driving car, and its VisionPro product hasn't had much success.
Still, in the CEO's early days, he's reportedly prioritized product design and releases. He wants to make the organization leaner and put out more products at a quicker pace. Ternus reportedly will launch products throughout the year, rather than at special events.
I view this positively. Apple can use the cash flow from the iPhone to fund product development. Still, given the company's size, it will need these products to scale quickly to make a dent in its sales.
The company trades like a growth stock, however. Apple's shares have a price-to-earnings ratio of 38, higher than the 10-year median of 27. The stock also has a richer valuation than the S&P 500's P/E multiple of 27.
Given their expensive valuation, I'd hold off on purchasing Apple's shares until you can see how quickly it releases new products and how consumers receive them.