Investors view quantum computing as the next frontier hardware play in the wake of artificial intelligence. Many companies in the sector are building quantum computers using different technologies. This makes it difficult to know which of the myriad approaches will prevail as the tech moves from research circles to widespread adoption.
Take IonQ (IONQ -3.47%) and Rigetti Computing (RGTI -4.73%). The former develops ion-based quantum devices, while the latter employs superconducting machines.
Both offer reasons to invest, so which is the better choice? I decided to buy shares in IonQ. Here's a look at each company to help you evaluate them.
Image source: Getty Images.
A look at Rigetti Computing
Rigetti Computing boasts several strengths. It is a vertically integrated, pure-play quantum computer company, laser-focused on superconducting machines, the prevailing industry modality used by tech giants, including IBM. Its capabilities encompass in-house control over the entire end-to-end quantum computer construction process, from chip design and manufacturing to the software that operates the system.
To generate revenue, the company provides access to its quantum machines via the cloud and sells them. In a sign that Rigetti's tech shows promise, the company was awarded $100 million by the U.S. Department of Commerce in September. It's also working with Hewlett-Packard to integrate quantum devices into current supercomputers to create a hybrid computing solution.
RGTI Rigetti Computing
NASDAQ · As of 4:00 PM ET 10/22/26
Rigetti is experiencing sales growth in 2026. Its second-quarter revenue reached $5.1 million, up from $1.8 million in 2025.
Despite the substantial increase, Rigetti remains deeply unprofitable. Its Q2 operating loss totaled $28.1 million, up from $19.9 million in 2025, an indication that costs to run its business are rising.
Rigetti's cash burn would be a concern if not for a substantial stockpile of cash, cash equivalents, and investments totaling $541.3 million as of the end of Q2. This sum and the $100 million government award can sustain operations in the short term as it evolves its technology to achieve greater customer adoption.
The case for IonQ
IonQ's ion-based quantum computers are slower than Rigetti's superconducting approach, but possess the world record for fidelity, a measure of the accuracy and reliability of quantum calculations. While speed is important, the output is only helpful if it's accurate, making fidelity a critical success metric.
This accuracy contributed to the company gaining traction with customers. Its Q2 revenue hit $80.1 million, a sum that not only exceeds Rigetti by a wide margin but is also nearly double the second-quarter sales of all other pure-play quantum computer companies combined.
This is no fluke. IonQ has grown revenue every year since it became a public company in 2021. It expects that trend to continue in 2026, with forecast sales between $280 million and $290 million, more than double 2025's $130 million.
IONQ IonQ
NYSE · As of 4:00 PM ET 10/22/26
Also, IonQ's platform is robust. Its acquisition of SkyWater Technology this year gives it a foundry for the construction of its quantum computer chips. On Oct. 12, IonQ announced it was acquiring cybersecurity business Elisity to strengthen its quantum cryptography.
That said, IonQ's aggressive acquisition strategy has produced rapidly rising costs. It exited Q2 with an operating loss of $337.2 million compared to a loss of $160.6 million in 2025.
IonQ's cash, cash equivalents, and investments totaled a substantial $3 billion at the end of Q2, but ideally, it will look to rein in its acquisitions. The deal for Elisity involves stock valued at up to $1.3 billion, which presents a significant dilution impact for shareholders.
Rigetti or IonQ?
Between Rigetti and IonQ, I think the latter is the better investment. The reason I chose to buy IonQ stock is that it shows a consistent trend of rising revenue, indicating that customers value its technology.
Moreover, Rigetti's share price is sky-high compared to IonQ's, and that's after its price-to-sales ratio has steadily declined throughout 2026.
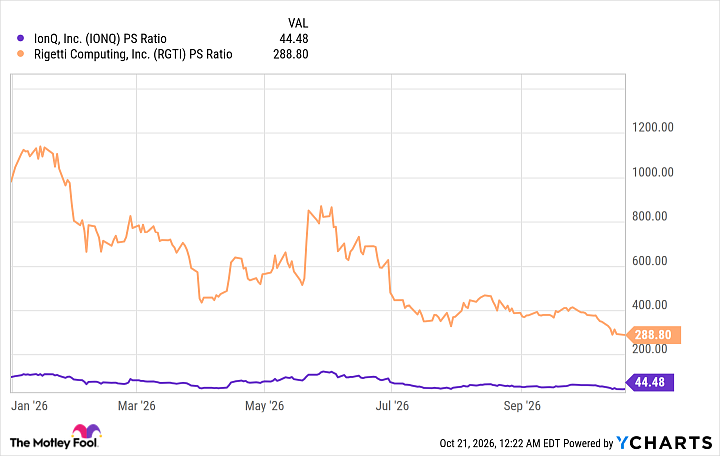
Data by YCharts.
As the chart shows, Rigetti's sales multiple is more than six times IonQ's, suggesting the latter is the better value. This, combined with IonQ's far larger revenue, comprehensive platform, and a hoard of cash and investments totaling $3 billion on its balance sheet, positions the company for long-term success.
While Rigetti's sales in the first half of 2026 hit $9.5 million, which already exceeds 2025's total revenue of $7.1 million, that sum pales in comparison to IonQ. Until Rigetti can show it can meaningfully increase revenue and sustain that trend over time, its superconducting tech is at risk of being overshadowed by deeper-pocketed rivals such as IBM.