Tom Gardner, TMF co-founder & CEO
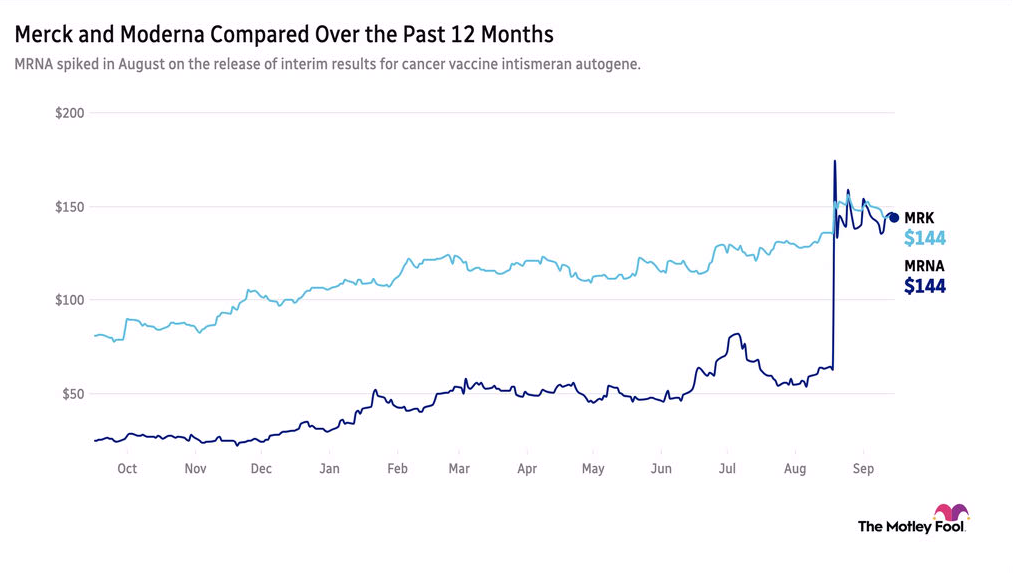
At Hidden Gems, we recommended and invested in Moderna (NASDAQ:MRNA) at $24.15 in November 2025. We've recommended it again more than a dozen times, and our Epic Portfolio cost basis was $54.15 as of April. Shares now trade near $144.
I believe Merck (NYSE:MRK) should acquire Moderna for $210 to $215 per share. Here's why:
The clock is ticking.
Merck's cancer drug, Keytruda, represents nearly half of the company's sales and faces lower-priced U.S. competition in late 2028. Qlex, its new under-the-skin version, could soften the blow. But Merck still needs new sources of growth.
A major source is emerging via Moderna's intismeran, a vaccine personalized for each patient's tumor. When added to Merck's Keytruda in a post-surgery melanoma trial, it cut the risk of cancer returning or spreading. And while longer survival is unproven, the promise is very real.
Owning beats splitting.
Today, Merck splits intismeran with Moderna 50-50 (half the cost, half the profit). Buying Moderna would unite the program's economics and give Merck greater control over the broader technology and manufacturing behind it. That would speed solutions to the world, as the unified effort can read a tumor, build the personalized shot, and ship it in weeks. This engine belongs inside Merck.
The price is right.
At $215, Moderna would cost around $86 billion. That price buys lasting control of Moderna's technology, manufacturing, and capacity to develop successive medicines (with emerging opportunities across its lung, bladder, and kidney cancer programs). And it neutralizes the risk of favorable new survival data repricing MRNA stock higher.
Merck has the financial strength and existing valuation to warrant a combined debt-plus-equity acquisition.
This action would bring together two remarkable companies and increase the chances to spare families from devastating loss.
Capitalism at its best.