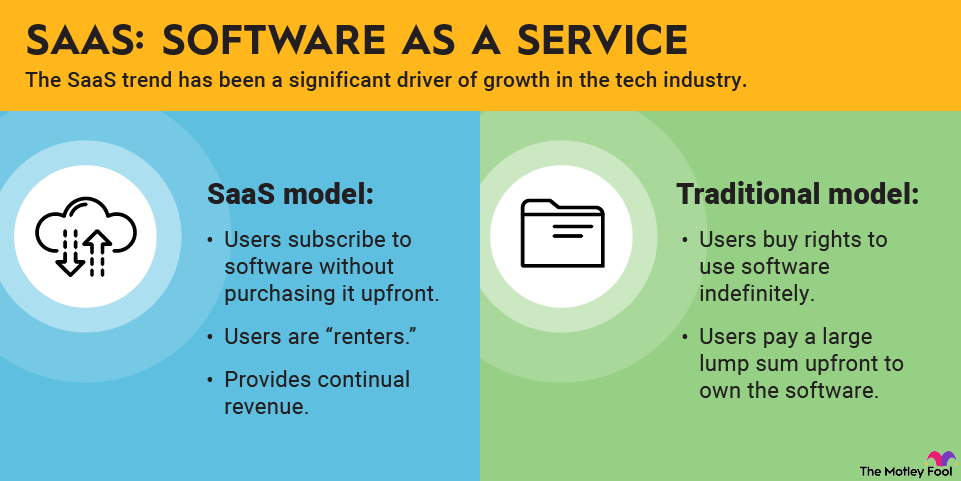
Loading paragraph...
Loading paragraph...
Loading ticker_table...
Loading paragraph...
Loading company_card...
Loading paragraph...
Loading paragraph...
Loading company_card...
Loading paragraph...
Loading paragraph...
Loading company_card...
Loading paragraph...
Loading paragraph...
Loading company_card...
Loading paragraph...
Loading paragraph...
Loading paragraph...
Loading paragraph...
Loading paragraph...
Loading paragraph...
Loading hub_pages...
Loading paragraph...
Loading faq...
About the Author

Scott Levine is a contributing Motley Fool stock market analyst covering energy, industrials, technology, and materials. He is also a high school English teacher and a small business owner. He holds a bachelor’s degree in English and creative writing from Binghamton University, a master’s degree in secondary education from Adelphi University, and an advanced certificate in school building leadership from CUNY Queens College. A crossword puzzle enthusiast, he has solved more than 3,100 New York Times puzzles with a 97% solve rate.
Scott Levine has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends PubMatic, Roku, and The Trade Desk. The Motley Fool recommends Magnite and Verizon Communications. The Motley Fool has a disclosure policy.
Read Next