Parker-Hannifin (PH +0.69%) focuses on motion control, hydraulics, pneumatics, filtration, and aerospace systems, so it is somewhat unique, with no single conglomerate overlapping with 100% of its product portfolio.
The industrial company reports earnings on Aug. 6 and analysts, on average, are expecting earnings per share (EPS) of $8.27 and revenue of $5.57 billion. The stock has consistently beaten analysts' estimates, though. Considering the company's track record, it may make sense to buy the stock before Aug. 6.
Here are three reasons why it might be a good buy-and-hold industrial stock, regardless of what happens with the company's fourth-quarter earnings.
Image source: Getty Images.
The company's record backlog and momentum
Supported by the successful 2022 integration of Meggitt and the pending $2.55 billion acquisition of CIRCOR Aerospace, Parker-Hannifin entered the quarter with a record order backlog, reaching $12.5 billion in the fiscal third quarter ended March 31. It also had $5.5 billion in sales, up 12% year over year, and reported record adjusted earnings per share (EPS) of $8.17 for the quarter, up 16% from the same period last year.

NYSE: PH
Key Data Points
High aerospace backlogs provide top-line visibility and margin expansion that cushion against potential weakness in broader short-cycle industrial markets. Its aerospace systems segment had $1.8 billion in sales in the third quarter, with a 22% rise in commercial original equipment manufacturer (OEM) sales and a 14% rise in aftermarket sales. The segment's operating margin grew by 80 basis points year over year to 29.5%. The company's guidance points to 12% year-over-year growth in the segment.
The company should also benefit from the rise in military spending spurred by the conflict in Iran, as its products are part of nearly every military aircraft.
High-quality cash generation and capital allocation
Parker's capital deployment remains a key catalyst. Robust free cash flow -- with $2.6 billion in the third quarter -- has enabled rapid debt paydown, while simultaneously funding strategic bolt-on mergers and acquisitions and returning cash to shareholders. It had repurchased $825 million worth of its shares through the third quarter while cutting its long-term debt to $6.7 billion.
A dependable, growing dividend
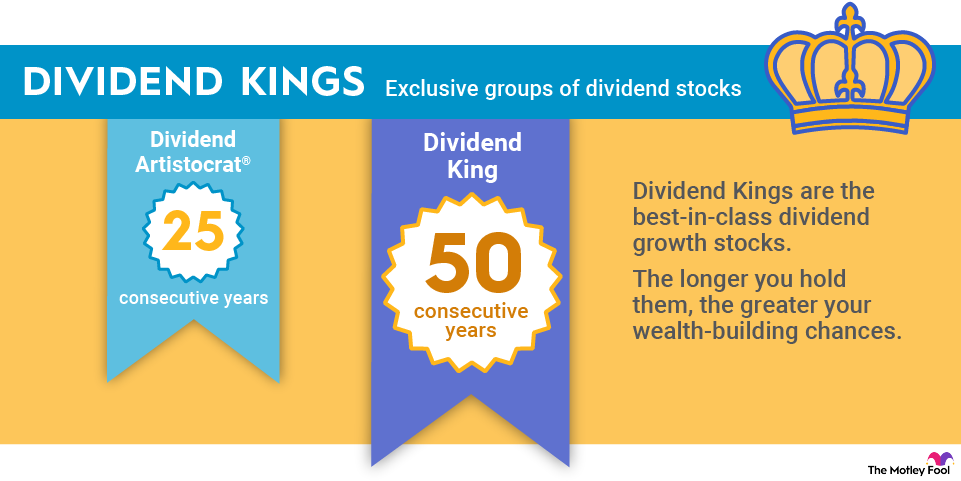
The company is a Dividend King, one of a small list of stocks that have increased their quarterly dividend for 50 or more consecutive years. While many Dividend Kings now have single-digit dividend increases, Parker-Hannifin increased its dividend by 11% to $2 per share in April, marking the 70th consecutive year of dividend increases. Its five-year dividend growth rate is almost 94%.
One reason not to buy Parker-Hannifin
The stock is up more than 37% so far this year and is trading near record highs, not far off its 52-week high of $1,034.96. Its price-to-earnings ratio (P/E) is above 36, and it has a PEG ratio around 8.5. Those numbers are historically high for the stock, but compared to its competitors, they are somewhat conservative.
However, any near-term weakness in short-cycle industrial PMI data, management caution regarding full-year 2027 guidance, or an earnings print that merely meets (rather than beats) estimates could trigger post-announcement profit-taking and volatility.