There's a lot for investors to be excited about when it comes to the growth trajectory of GE Vernova (GEV +0.13%). The company's second-quarter earnings were impressive, with total revenue up 22% year over year, orders jumping 88% in the same time period, and the backlog ballooning to $176 billion. Management raised guidance for both revenue and free cash flow. Overall, an incredibly strong showing for the Boston-based business. Why then did the industrial stock drop?

NYSE: GEV
Key Data Points
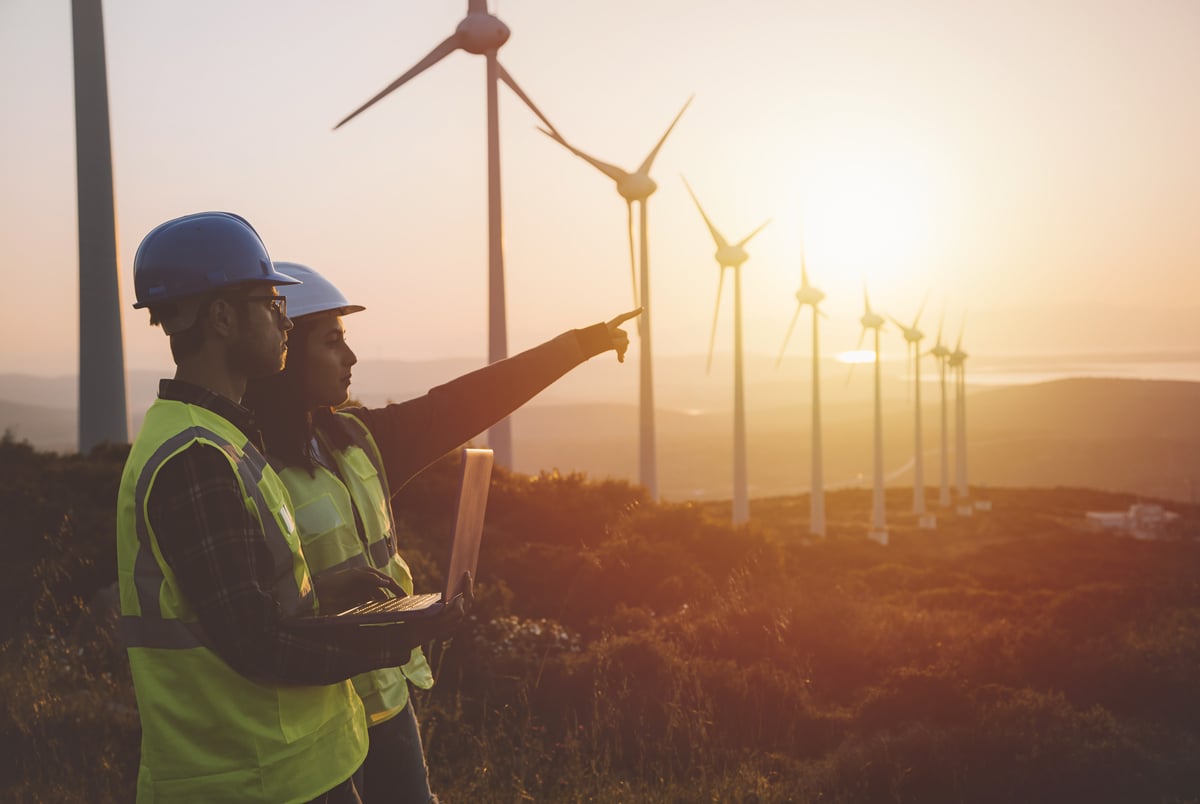
The reason is one segment in particular: wind. GE Vernova's wind revenue declined 10%, while orders sank 40%. The widening losses in the wind division concerned investors more than the wins in power and electrification excited them.
The reaction from investors was largely overblown, in my opinion. The company's long-term bull case is still compelling. Its power and electrification divisions, which make up the vast majority of the business, are still riding high on insatiable demand from AI infrastructure.
Image source: The Motley Fool.
GE Vernova's gas turbine capacity is sold out through 2028, free cash flow exceeds $5 billion, and the wind segment is becoming a smaller piece of GE Vernova's pie. So yes, the company's difficulties with its wind business are real and a significant drag overall, but that's not the whole story for GE Vernova.
Any dips in stock price caused by an overreaction to the wind segment should be seen as an opportunity to buy at a lower price, not a red flag. GE Vernova's stock is still up 45% in 2026 and more than 580% since General Electric split into three separate companies in April of 2024.