Contrary to a common assumption, stock trading isn't the top source of revenue for brokerage firms like Charles Schwab (SCHW -1.15%). Neither are fees for investment management. Surprisingly enough, clients' cash balances along with fixed income assets (like bonds) and margin interest are most brokerages' biggest sources of revenue. And with interest rates at multiyear highs, this revenue has been significant of late. In fact, net interest revenue of nearly $3.4 billion accounted for nearly half of Schwab's second-quarter top line.
So what happens to Charles Schwab's revenue if interest rates peel back again?
Then and now
You need to do a little digging to find it, but it's there. During the three months ending in June, Schwab spent just under $1.1 billion of its own money paying for access to this customers' funding. Mostly, this went to interest payments on bank or bank-like deposits. But it collected over $4.4 billion worth of interest payments, with the biggest chunk of those receipts coming from fixed-income securities it owns for itself. Its average net yield? That is, the difference between the nearly 4% it's getting on these assets and the interest rate of just under 1% it's paying for access to this capital? It's right at 3%. Not bad.
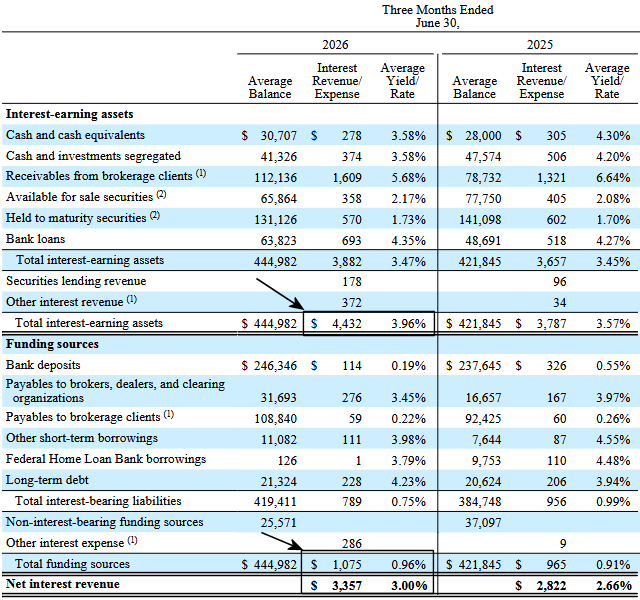
Image source: Charles Schwab's Q2 2026 report.
Things aren't always quite this fruitful, however.
Higher interest rates tend to lead to higher net yields simply because the interest rates earned on interest-bearing assets rise quite a bit, but Schwab's cost of this capital doesn't grow nearly as much. Take a look at these same numbers from Q2 of 2021, when the COVID-19 pandemic sent interest rates plunging. Although the brokerage firm was paying practically nothing for this funding, it was also only earning a little more than 1.5% on its interest-bearing assets and idle cash at the time -- and there was quite a bit more of it then than there is now. More than $530 billion produced less than $2 billion in net interest income.
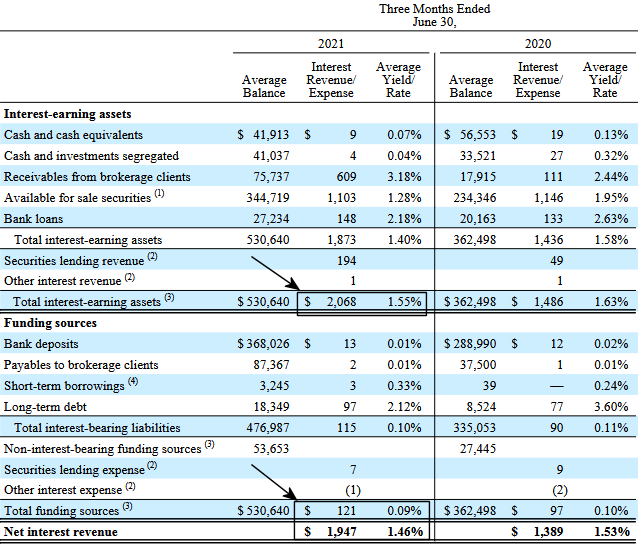
Image source: Charles Schwab's Q2 2021 report.
Not now, but eventually
No two interest rate backdrops are ever exactly the same because no two economic backdrops are the same. Although the "spread" between a broker's interest costs and interest receipts generally widens as rates move higher and narrows as interest rates fall, the exact size of the difference between what it's earning and what it's paying out isn't etched in stone.
Still, the general tendency is a reliable one, and one that current or prospective Schwab shareholders should understand. The amount of net interest revenue the brokerage firm is collecting right now -- nearly half of the company's total revenue, in fact -- is almost twice what it was collecting when rates were so low just a few years ago. While this is an extreme swing, should interest rates peel back even just a little bit, it could take a measurable toll on Charles Schwab's bottom line.
Fortunately, that probably won't happen in the immediate future. After last week's surprisingly strong jobs report from August, the likelihood of a rate hike in the near future is even higher.