When Ray Dalio speaks, investors tend to listen, and likely for good reason. He ran Bridgewater Associates, the hedge fund he founded, for half a century, and over that time, he was one of the most successful investment managers in history.
In fact, he has long used history as a guide for deploying capital, and today, he believes history offers lessons for how investors should approach the AI boom. Specifically, he sees echoes of 1929 and 2000 in the current situation, and is urging investors to approach AI stocks with caution. Here is what he said and why investors may want to heed his advice.
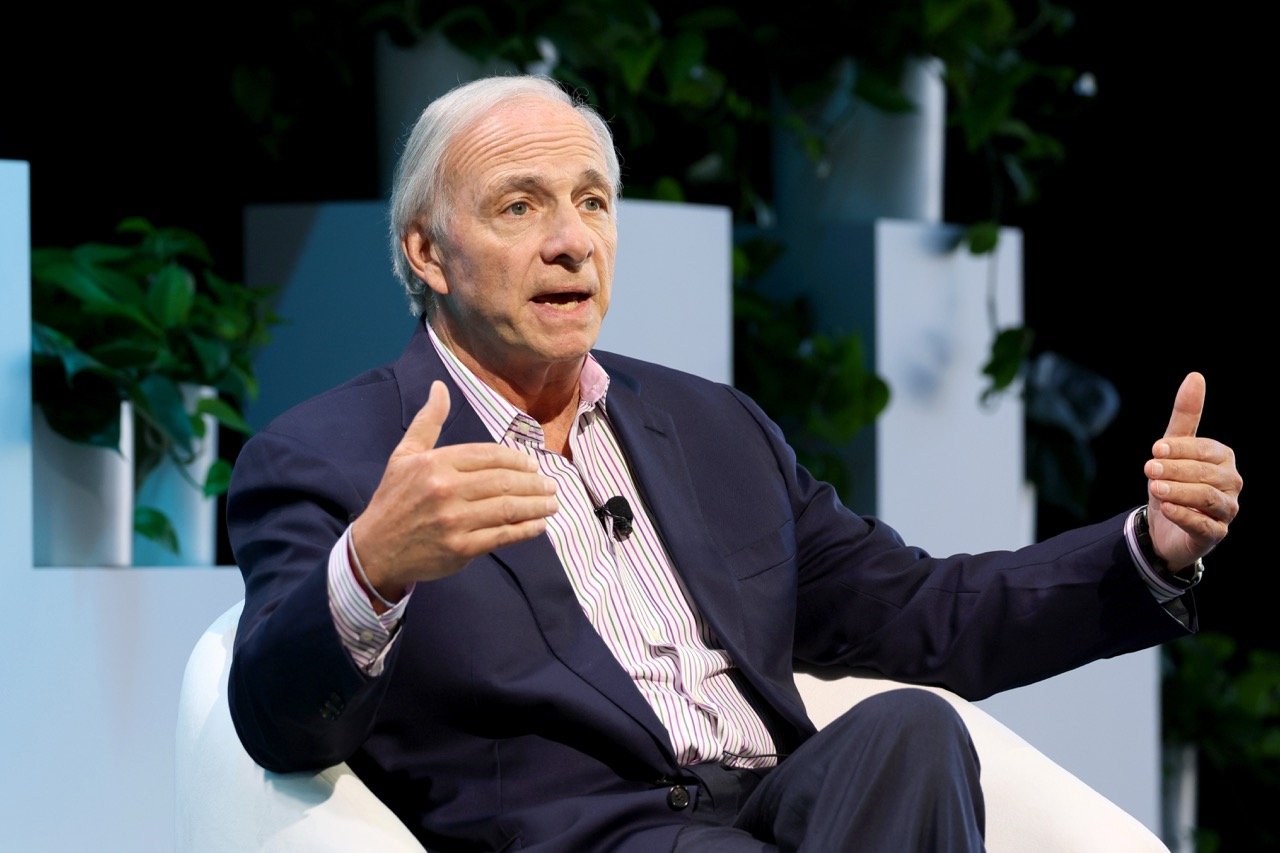
Image source: Getty Images.
Ray Dalio and AI
First of all, investors should remember that Dalio has stepped down from Bridgewater. Thus, the fund's investments in AI stocks like ServiceNow and Nutanix were likely made without his input.
Given what he has said recently, he may even disagree with those purchases. When Dalio appeared on the podcast The Diary of a CEO in August, he said that AI shows "classic signs" of a bubble.
One can see this in the S&P 500's cyclically adjusted price-to-earnings (CAPE) ratio, otherwise known as the Shiller P/E ratio. That metric is a gauge of how the broad market is valued relative to inflation-adjusted historical earnings, giving it a longer-term view. The CAPE ratio currently stands at 41. That is well above where it peaked right before the stock market crash of 1929 and just below the record high of 44 it reached in 2000, just before the dot-com bust.
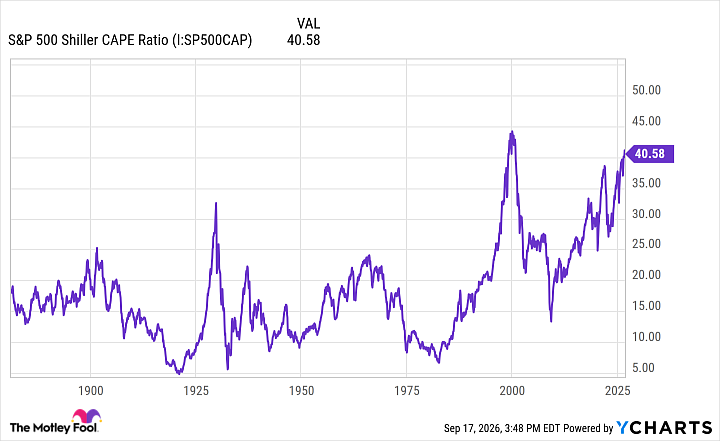
S&P 500 Shiller CAPE Ratio data by YCharts.
Those are the historical parallels that Dalio cites in making his prediction about AI. In fact, he believes conditions have already begun to prick the bubble.
Investors should also note that when Dalio speaks of bubbles, he describes them in degrees of a bubble, avoiding a "bubble/not a bubble" binary. Hence, no single event is likely to prick the bubble. However, he cites events such as rising interest rates or wealth taxes that may trigger forced selling and tank stock prices.
Additionally, another common action in such times, secondary stock issuance, tends to dilute investor wealth, and since companies can theoretically issue as much stock as they want, dilution poses a real risk to investors. While that may not destroy the AI industry (the internet survived the dot-com bust, after all), such an event could cause investors pain.
How investors should react
Investors should probably listen to Dalio.
In 2008, when the S&P 500 fell by 37%, his fund gained 9.5%. That indicates his considerable ability to see turbulent events coming and turn them into opportunities to drive returns.
Nonetheless, unless one has zero tolerance for risk, the answer is probably not simply to sell AI stocks. Investors should note that Berkshire Hathaway has aggressively purchased shares of Google parent Alphabet under current market conditions.
Warren Buffett and his successor as CEO, Greg Abel, have been vocal about their appreciation for Alphabet. Also, despite the company being on track to spend between $195 billion and $205 billion on AI-driven capital expenditures for the year, Alphabet generated $53 billion in free cash flow over the trailing 12 months.
This means it can afford to invest in AI, and could maintain its stability even should those investments fail to generate the desired returns. With Alphabet trading at a P/E ratio of 17, the potential rewards could easily outweigh the risks for prospective shareholders.

NASDAQ: GOOGL
Key Data Points
Unfortunately, most AI companies are not in similar positions. Many of them have borrowed heavily to fund their AI-driven capex. Also, rising interest rates are likely to strain those companies. Even worse, should infrastructure demand suddenly drop, it could cause such companies tremendous pain, and some could be forced into bankruptcy.
Thus, rather than abandoning AI completely, most investors should probably view this possible scenario as an opportunity to invest in the highest-quality AI companies, possibly at lower prices.
Approach AI cautiously
Given Dalio's record of success as an investor and his ability to turn historical perspective into investing opportunities, his viewpoint deserves serious consideration.
Admittedly, Dalio could be wrong about the degree to which the AI sector is in a bubble, and even if he's right, its growth could continue for the foreseeable future. Moreover, much as the internet survived the dot-com bust, AI is likely here to stay, even if the sector is headed for a downturn.
Nonetheless, Shiller CAPE ratios this extreme have historically preceded deep downturns, so planning for such an event is prudent. For those who want to continue investing in the AI sector, rotating into higher-quality AI-related tech stocks or more conservative investments -- as Dalio advises -- could make sense.