Bristol Myers Squibb (BMY +2.18%) is up a little more than 17% so far this year. Analysts don't seem that optimistic about the pharmaceutical stock, with an average price target of $66.71, just over $3 above its current trading price.
The bear case for the stock is that several of its top sellers, including Eliquis and Opdivo, are facing patent expirations. However, that's discounting the rise in the company's growth portfolio. Here are three reasons why the bull case for the stock is getting louder.
Image source: Getty Images.
It's underpriced compared to its peers
The company is coming off a strong second quarter, in which it reported revenue of $12.9 billion, up 6% year over year, and earnings per share (EPS) of $1.62, up 153% from the same quarter a year ago.
Despite strong recent operating performance, the stock trades at a discounted valuation of less than 10 times forward earnings and less than 14 times trailing earnings. That's lower than most of its mega-cap pharmaceutical peers, including AbbVie, AstraZeneca, Merck, Johnson & Johnson, Pfizer, and Roche.
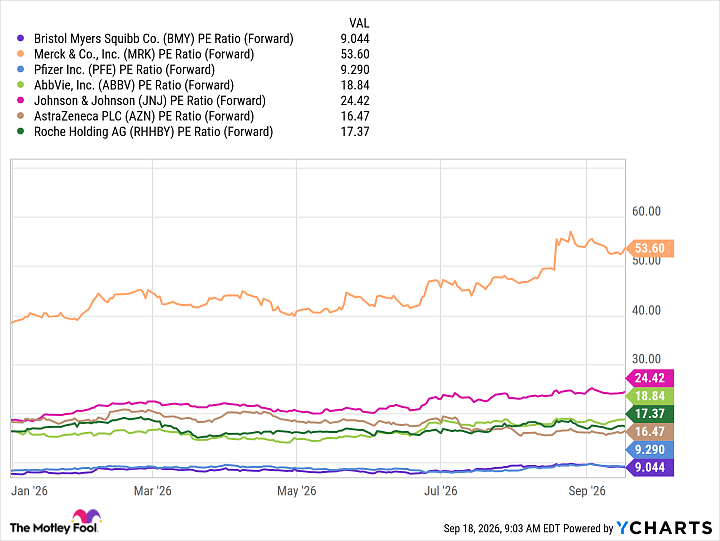
BMY PE Ratio (Forward) data by YCharts.
This suggests the market has overly discounted the stock relative to its more than $11 billion in annual free cash flow, creating a high margin of safety and rerating potential as pipeline milestones read out.
Its growth drugs, including Opdivo, Qvantig, Cobeyta, Camzyos, Reblozyl, Breyanzi, and Opdualag, now account for nearly 60% of total revenue and grew revenue by 15% year over year in the second quarter. Double-digit expansion across these commercialized therapies, combined with next-generation pipeline candidates such as blood thinner Milvexian, gives the company a clear runway to fill the top-line revenue gap.
It has a solid, well-funded dividend
Bristol Myers Squibb has paid out a dividend for 94 consecutive years and has raised it for the past 17 years. This includes a 1.6% increase to $0.63 per share this year, boosting the dividend yield to 3.95% at current prices, more than three times the average dividend yield on the S&P 500.
With a conservative payout ratio of around 44% of trailing free cash flow (FCF), the dividend is well supported by free cash flow, paying investors handsomely as the pipeline executes.
The other area where the company is shareholder-friendly is in stock buybacks. It has a $5 billion stock repurchase plan in effect.
Its cash machine gives it a nice cushion
Bristol Myers Squibb continues to beat quarterly earnings and revenue expectations, and delivered more than $3 billion in FCF in Q2. This substantial cash generation allows management to simultaneously fund late-stage research and development, pursue strategic bolt-on acquisitions, and aggressively pay down debt to strengthen the balance sheet.
BMY Bristol Myers Squibb
NYSE · As of 4:00 PM ET 10/15/26

Ironically, one thing that could certainly push the stock higher is another company purchasing it. According to reports, AstraZeneca and Bristol Myers Squibb held merger talks valuing Bristol Myers Squibb at $400 billion. If that deal went through, Bristol Myers Squibb, as the buyout candidate, would see its shares jump. It's worth noting that such a mega-merger would face stiff scrutiny from regulators.
Regardless of any potential mergers, Bristol Myers Squibb, like AbbVie a few years ago, is poised to offset the revenue loss from its legacy drugs with its new therapies. That likelihood hasn't yet been fully priced into the stock.