The proliferation of artificial intelligence (AI) has created massive chip demand, which isn't surprising as semiconductors are the basic building blocks in data centers that train large language models (LLMs), and run agentic AI and inference applications.
It is worth noting that AI data centers employ various kinds of chips. From central processing units (CPUs) to custom AI processors to graphics processing units (GPUs), the AI supercycle has triggered impressive growth for companies designing these chips. However, the common factor among CPUs, GPUs, and custom AI chips is their memory.
All AI accelerators need to be equipped with faster, larger memory to enable fast data transfer and store a large number of parameters so that AI training and inference tasks can be executed quickly. This explains why SK Hynix (SKHY -5.99%) is one of the most important companies in the AI semiconductor ecosystem.
Let's see why buying this growth stock could be one of the best ways to capitalize on the AI boom.
Image source: Getty Images.
SK Hynix dominates the AI memory space
AI accelerators are equipped with high-bandwidth memory (HBM). This is a specialized type of memory that's manufactured by stacking multiple dynamic random-access memory (DRAM) chips vertically close to the AI accelerator. As a result, HBM enables the transfer of massive amounts of data while keeping energy consumption in check.
SKHY SK Hynix
NASDAQ · As of 11:10 AM ET 10/22/26
Not surprisingly, HBM demand has been growing at a terrific pace. SK Hynix estimates that the HBM market's revenue could increase 58% in 2026 to $54.6 billion. Importantly, HBM demand is poised to accelerate over the next couple of years. Investment bank Citi estimates that HBM bit demand could jump by 62% in 2027, followed by a bigger increase of 69% in 2028.
At the same time, the demand-supply gap in the memory market is poised to widen. Citi estimates that DRAM supply will increase by 19% in 2027 and 22% in 2028. This is good news for SK Hynix, which controls 50% of the HBM market, according to Counterpoint Research, well above Samsung's 33% share. The company's share of the overall DRAM market was 25% in the second quarter, next only to Samsung.
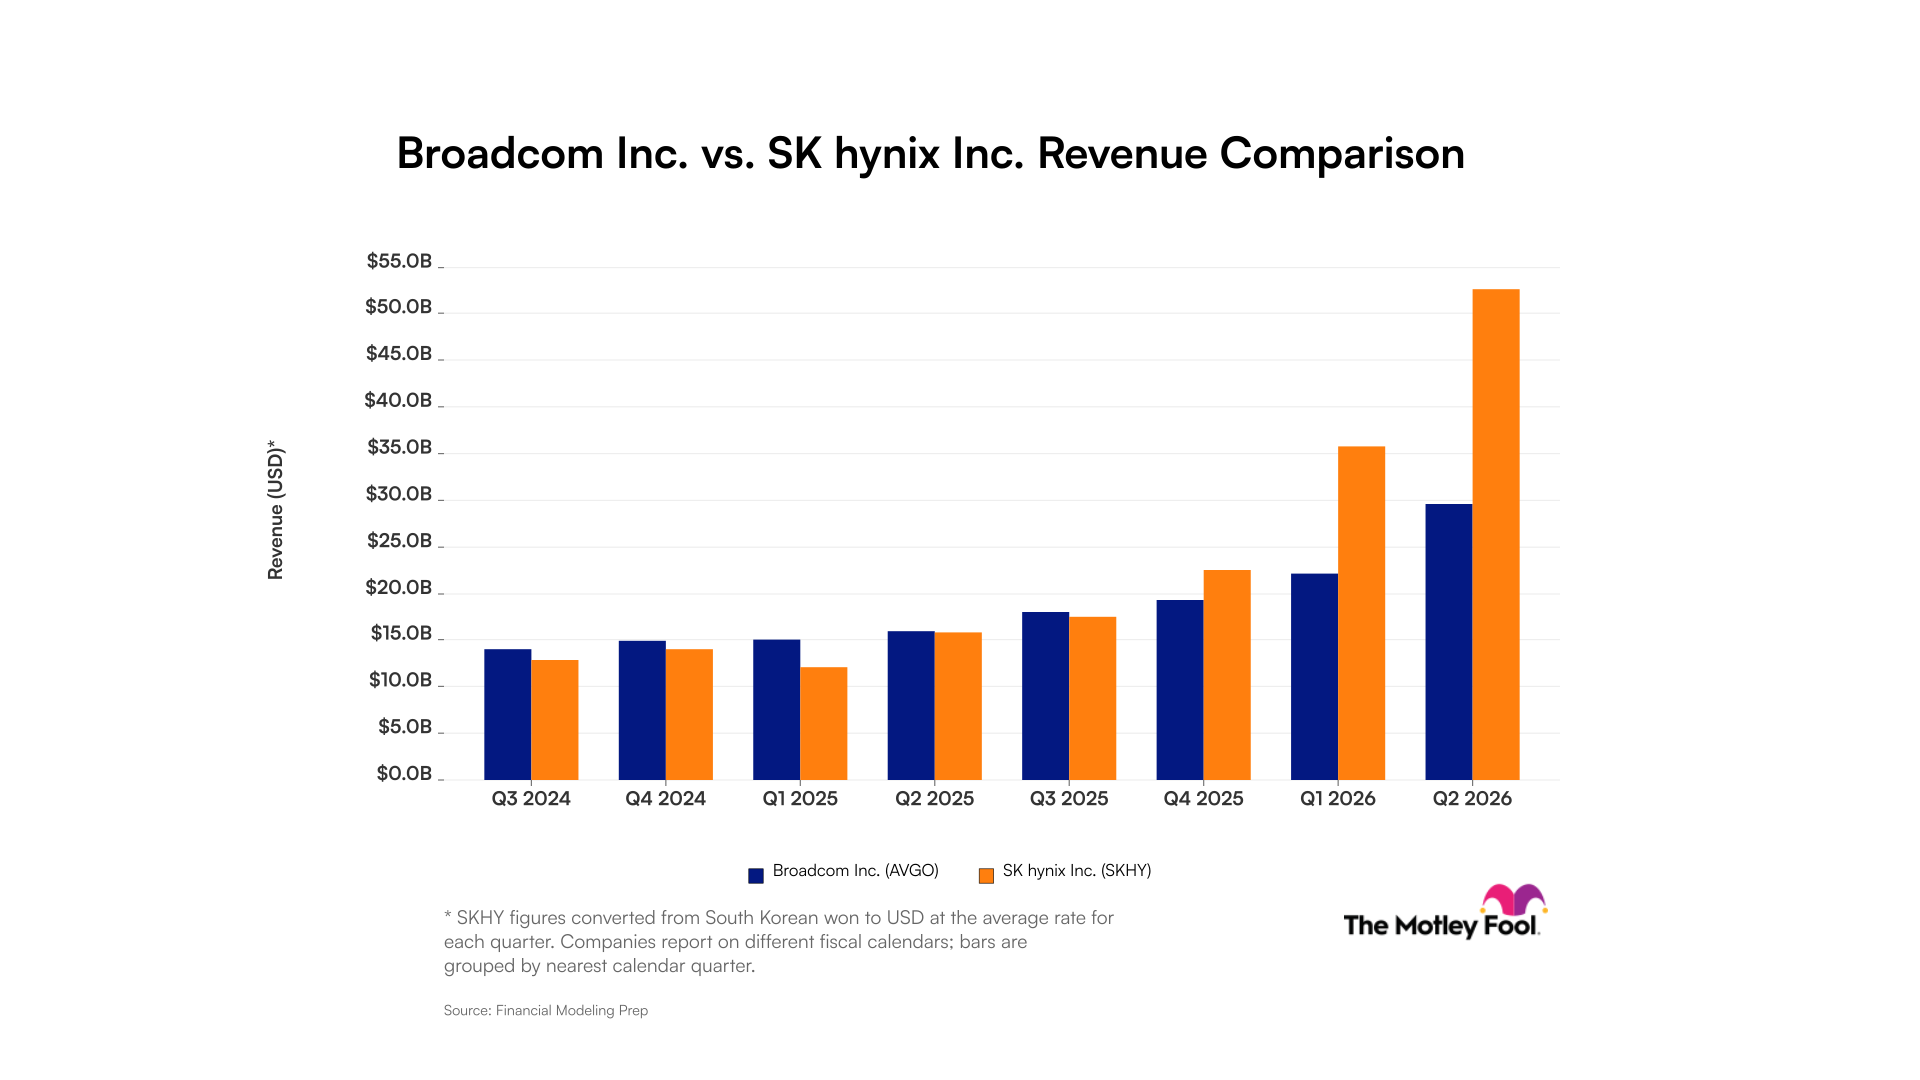
SK Hynix's pole position in HBM puts it in a solid position to deliver healthy revenue and earnings growth over the long run. The company's revenue jumped by 3.5x year over year in Q2, while operating profit was up by 6.5x. The robust growth in HBM demand, along with the supply constraints, should help SK Hynix sustain such solid growth in the future.
In fact, the company's earnings per share (EPS) could increase at an 82% annual pace over the long run, according to YCharts. This makes SK Hynix a screaming buy right now, especially considering its valuation.
Analysts may be underestimating the upside potential
SK Hynix's 12-month median price target of $245 implies 25% upside from current levels, according to 11 analysts covering the stock. Even better, the stock is rated as a buy by all analysts covering it, according to CNN. However, this growth stock could easily crush that target considering the 80%-plus long-term EPS growth it could deliver.
A big reason that's going to be the case is SK Hynix's earnings multiple of just 11. That's significantly lower than the S&P 500 index's earnings multiple of 23. The company's strong earnings growth rate could be rewarded with a premium valuation, paving the way for impressive gains over the long run.