There's a lot of buzz surrounding quantum computing stocks right now, and three of the most popular among investors are Rigetti Computing (RGTI +0.97%), D-Wave Quantum (QBTS -0.40%), and IonQ (IONQ +1.11%).
Their share prices have soared over the past three years, but most have lackluster sales, and rising costs mean that the jury is still out on their ability to survive over the long term.
So, let's take a quick look at what each company is doing to stay in the fight and which one looks best positioned to be here years from now.
Image source: Getty Images.
IonQ's commercial business is expanding
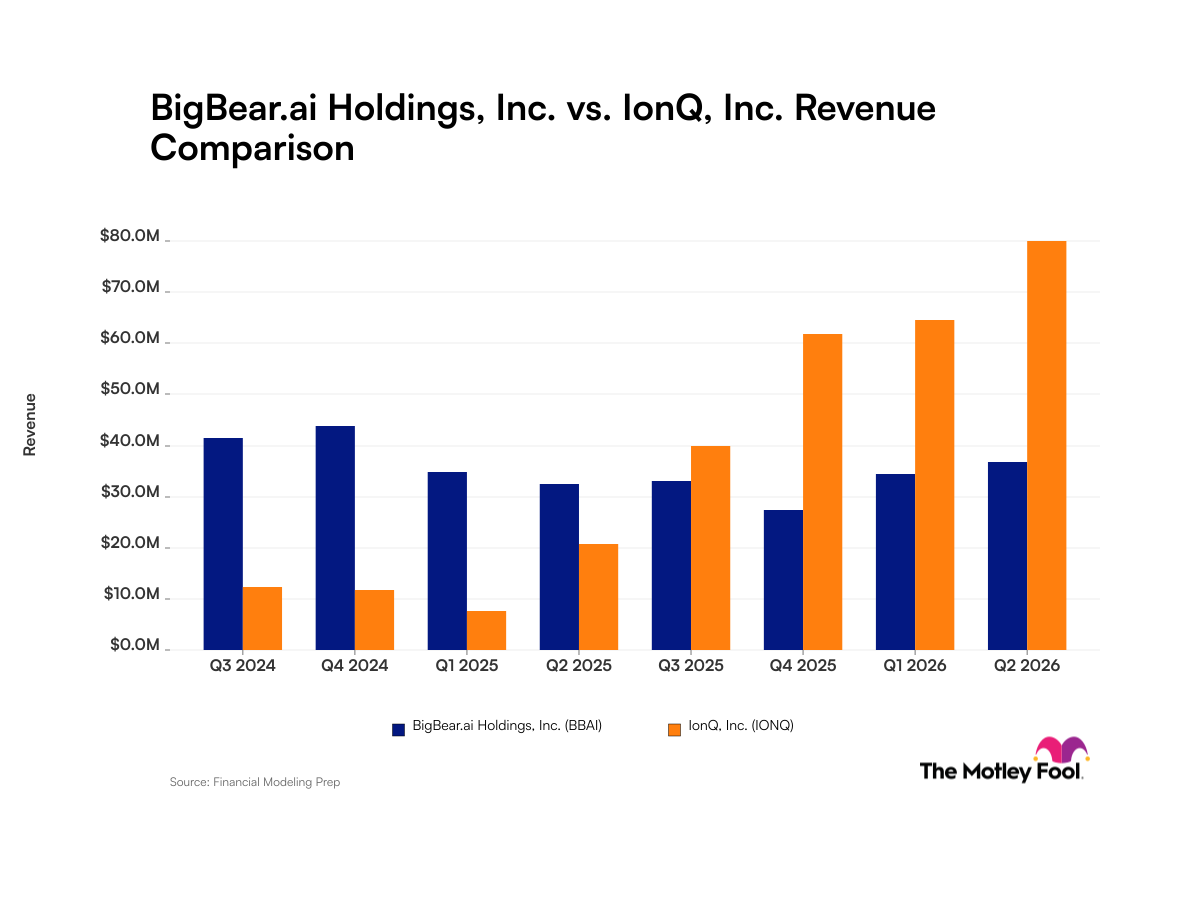
IonQ recently reported second-quarter revenue of $80.1 million, a 287% increase from the year-ago quarter. Part of that jump came from a recent acquisition of SkyWater Technology, a chip foundry business, but organic sales are on the rise, too.
IonQ's management says that organic quantum computing revenue will double this calendar year. That's impressive growth and shows that IonQ can attract commercial customers.
But investors should know that the company isn't profitable yet, and its losses are widening. IonQ's non-GAAP (adjusted) earnings before interest, taxes, depreciation, and amortization (EBITDA) loss was $120.3 million in the second quarter, much higher than its loss of $36.5 million in the year-ago quarter.
Still, IonQ has cash and cash equivalents of $3 billion, so there's little worry that the company will run out of money any time soon.

NYSE: IONQ
Key Data Points
Rigetti is gaining customers, but commercial sales are lacking
Rigetti recently expanded its collaboration with Hewlett-Packard and the Pittsburgh Supercomputing Center, and its sales popped 185% in the second quarter.
The problem is that revenue was just $5.1 million, barely a blip on the company's own income statement. Investors should know that Rigetti's CEO, Subodh Kulkarni, has said that "commercial revenue remains early" and it's likely it could be several more years before its tech reaches a point where it's significant.
The good news for Rigetti is that the company is debt-free and has $541 million in cash to keep the lights on for a while.

NASDAQ: RGTI
Key Data Points
D-Wave has a long way to go
D-Wave's bookings in the second quarter were impressive, soaring 1,120% to $35.5 million. That's a good sign that customers are interested in D-Wave's products and services, but revenue hasn't come as easily for the company.
D-Wave had sales of just $3.1 million in the quarter, below sales in the year-ago quarter, and its adjusted EBITDA loss was $37.1 million for the quarter.
D-Wave has about $588 million in cash and cash equivalents, which should give the company a substantial runway, but its lack of sales and significant losses should be a red flag for investors.

NASDAQ: QBTS
Key Data Points
IonQ likely has the best shot at survival
The quantum computing market is just getting started, and it'll likely be a wild ride for a while. But IonQ has higher revenue than its peers, and its organic sales from its quantum computing business appear on track to increase significantly.
And, given its very strong cash position, IonQ has plenty of money to keep itself going for the foreseeable future.
But that doesn't mean investors should hit the buy button right now. IonQ's stock is very expensive, with a trailing price-to-sales (P/S) ratio of 57, which is far above the tech sector average of about 8.
It could take many more years for the commercial benefits of quantum computing to catch up to the technology's potential. Which means that investors buying IonQ or any quantum computing stock will have to wait a while to see how all of this plays out -- and likely endure significant share price volatility along the way.