It's hard to believe, but we're entering the fourth quarter of 2026. This year has been one for the ages, with some stocks soaring while others in the same industries have stayed relatively flat. I think the smartest stocks to buy now aren't the ones that have soared already in 2026; they're the ones that have been quiet while their peers have been making waves.
Two of the top 10 performing S&P 500 stocks so far this year have been AMD (AMD +0.65%) and Intel (INTC -0.19%): They're up 195% and 230%, respectively, in 2026. However, I think their runs are about over for now.
Instead, I'd rather invest in Broadcom (AVGO -2.15%), Nvidia (NVDA +1.09%), and Taiwan Semiconductor Manufacturing (TSM +0.66%). Here's why I think these three are bound for new heights.
Image source: Getty Images.
Nvidia's and Broadcom's prospects are brighter than AMD's
Nvidia and Broadcom are competing against AMD in the race to deliver AI processing power. AMD has had a great year so far, and grew its data center revenue by 107% in Q2 alone. It is doing better and better each quarter, but Broadcom and Nvidia are growing faster despite being larger.

NASDAQ: AVGO
Key Data Points
AMD's data center revenue totaled $6.7 billion in Q2. Nvidia's grew at a 117% pace to $89 billion. Broadcom's AI semiconductor revenue of $16.7 billion in its latest quarter was closer to AMD's, but Broadcom's grew the fastest at a 221% pace.
Despite that, AMD shares have outperformed Nvidia and Broadcom so far in 2026. The reason? Its earnings valuation has exploded.
A lot of AMD's expected growth has already been priced into its stock, and based on next year's earnings projections, AMD now trades at a far higher multiple than Nvidia or Broadcom.
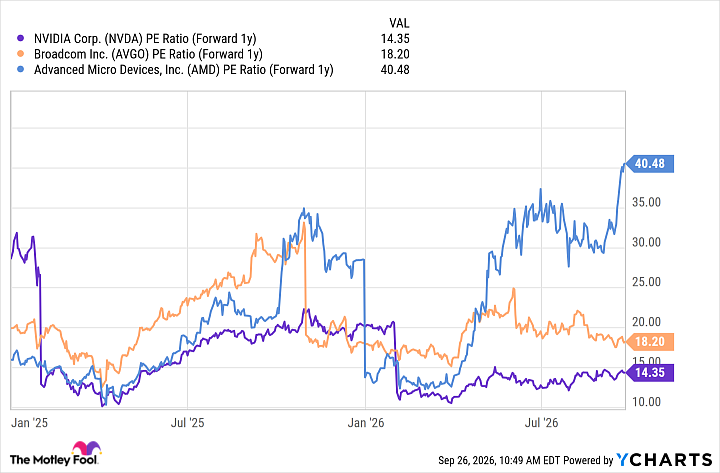
NVDA PE Ratio (Forward 1y) data by YCharts.
That will hamper its future share price growth for some time, whereas Nvidia and Broadcom are still primed to deliver impressive returns. That makes these two far better buys, and investors should be focused on them in October.
Taiwan Semiconductor has already done what Intel is trying to do
The primary story surrounding Intel is the revival of its foundry business. For years, Intel didn't have the same chipmaking capabilities as Taiwan Semiconductor and lost a lot of business to the industry leader. Now, however, several outside investors have injected cash into Intel's foundry business to fund its efforts to catch up, and now it is looking to acquire more clients to make use of its new capabilities.

NYSE: TSM
Key Data Points
That game plan obviously excites investors; the only problem is that a lot of the hoped-for turnaround is already priced into the stock.
If you compare Intel's and Taiwan Semiconductor's valuations using next year's expected earnings, it's clear that TSMC is a much cheaper stock. I think this gap will result in TSMC delivering far better stock performance over the next year than Intel.
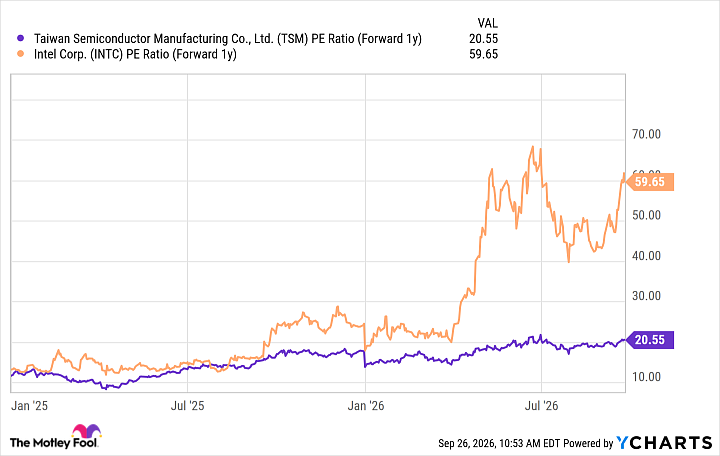
TSM PE Ratio (Forward 1y) data by YCharts.
With Intel stepping up its game, it will have more competition in the foundry space. However, TSMC is still the industry leader by far, and is primed to deliver faster growth regardless of its much larger size. In that light, I'm willing to bet that it will outperform Intel through the rest of 2026 and into 2027.