It's been an uncomfortable past few weeks for American Express (AXP -0.66%) shareholders. The credit card company's stock is down nearly 20% from July's peak, moving back within sight of March's 52-week low -- partly on worries about rising costs and partly on concerns about the overall health of the economy.
Experienced investors understand that this is just a typical short-term pullback within the confines of long-term progress. If you look at the bigger picture, you'll like where this stock is likely going, making this dip a compelling buying opportunity.
Image source: Getty Images.
American Express is persistently consistent
Nobody owns a functioning crystal ball that can perfectly predict the future. It's possible this prediction won't be on target. However, even though AXP shares don't move in a straight line, their long-term performance is shockingly consistent, reflecting the equally consistent growth of its top and bottom lines.
There are exceptions, to be sure. For instance, like almost everything else, this stock struggled during 2022's bear market.
Now take a look at its revenue and earnings even during that turbulent period, and for that matter, in the meantime. The continued growth of both has remained surprisingly steady.
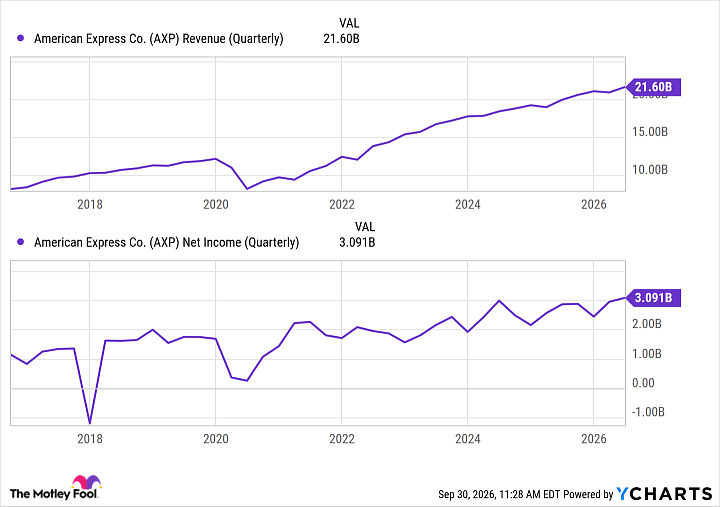
Data by YCharts.
Investors appear to doubt that this will remain the case for the foreseeable future. That's the interpretation of their response to American Express's full-year guidance updated in its second-quarter report, anyway. Although the company raised its 2026 revenue growth expectation from a range of 9% to 10% to a firm 10%, it left its profit expectations at $17.30 to $17.90. Investors were quick to interpret this only partially revised outlook as a sign that American Express's expenses are outgrowing its sales. Technically speaking, perhaps they are.
Most investors are overlooking a much more important detail about these numbers, though. That is, even at the low end of this year's profit guidance range ($17.30), this credit card powerhouse is still on pace to grow its bottom line by 12.4% from last year's earnings of $15.38 per share.
In other words, American Express is still a growth juggernaut, as it has been for years in any decent economic environment. Indeed, these growth rates of 10% and 12% are about the same rates that Amex's top and bottom lines (respectively) have experienced for a couple of decades now -- outside of decided economic challenges like a pandemic, of course.

NYSE: AXP
Key Data Points
Price projection
So given this, where might this stock be in, say, five years?
Assuming history repeats itself and the market continues to value American Express's stock as it has for a long while now, that would put it on pace to be worth around $540 a share at this point in 2031. That's an average annual gain of around 12% from its current trading level, matching its near- and long-term performance. Newcomers might even get a little more performance than that, given its recent dip and subsequent discount.
For what it's worth, new buyers should get off to a reasonably good start. Despite the stock's recent weakness, analysts are maintaining a 12-month price target of $ 380.57, which is 24% above the current price. That's not a bad tailwind to start out a new position.