Credo Technology (CRDO +2.21%) has become one of the hottest ways to invest in artificial intelligence (AI) without buying a traditional semiconductor stock. The company doesn't make GPUs or high-bandwidth memory (HBM). Instead, Credo specializes in moving data between processors, switches, memory, and other components inside AI data centers. While this might sound less exciting than designing the next accelerator, Credo's picks-and-shovels are increasingly needed as AI chip clusters require high-speed connectivity.
As of this writing (Oct. 7), Credo stock has surged 52% in 2026. While that's an impressive return, the rally might just be getting started. Let's assess what a $5,000 investment in Credo Stock could become by 2030.
Image source: The Motley Fool.
Credo is addressing one of AI's biggest bottlenecks
Buying more GPUs isn't useful for AI development if they can't communicate efficiently. Credo aims to solve the data bottleneck through its copper interconnects, called ZeroFlap Active Electrical Cables (AECs), as well as digital signal processors (DSPs), Ethernet retimers, and OmniConnect memory solutions. Together, these technologies represent the pipes that move data quickly while reducing power consumption, thereby improving network reliability for AI workloads.
Credo's growth has surged on the backdrop of exploding demand for artificial intelligence (AI) infrastructure. During fiscal 2026 (period ended May 2), the company generated $1.3 billion in sales -- up 206% year over year. Growth accelerated into this year, as the company reported sales growth of 115% year over year to $479 million during the first quarter of fiscal 2027.
The company's acquisition of DustPhotonics brought silicon photonics technology in-house. The rationale behind the deal is to help Credo build a vertically integrated connectivity stack to address both electrical and optical interconnects across AI infrastructure buildouts.

NASDAQ: CRDO
Key Data Points
Wall Street is bullish on Credo
Credo is transforming from an under-the-radar semiconductor company into a high-expectation AI stock. In investment terms, this means great earnings won't necessarily translate to a rising stock price. The company needs to prove it can outperform already aggressive expectations.
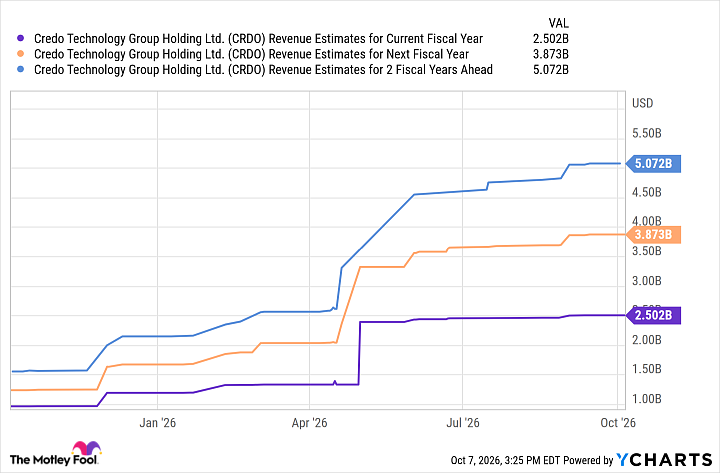
CRDO Revenue Estimates for Current Fiscal Year data by YCharts
Wall Street expects revenue to reach $5.1 billion by fiscal 2029, essentially double this year's forecast and quadruple what Credo reported last year. These numbers clearly represent extraordinary growth and give us something to think about when valuing the stock.
Credo stock is a speculative opportunity
At the moment, Credo trades at a price-to-sales (P/S) ratio around 23. This is pretty rich considering the company is only on pace to generate a little more than $2 billion in revenue this year and is still scaling profits. As the company matures and hopefully translates AI infrastructure spending from primarily a sales catalyst into larger profits, investors should expect Credo's valuation multiples to compress.
If the company achieves the fiscal 2029 revenue target and receives, say, a 12 P/S ratio, the company would command an implied market capitalization of roughly $61 billion. That represents roughly 49% upside to Credo's current trading levels, making the initial $5,000 investment worth approximately $7,450.
The subtle theme here is that even though Credo has a legitimate long-term opportunity spanning copper connectivity, optics, silicon photonics, and memory it may not be the most lucrative stock to buy at today's price. The returns in my analysis above are attractive considering the timeframe, but they are also far from guaranteed. A lot needs to go right for Credo to continue doubling in size for consecutive years, all while maintaining a premium valuation.
To me, Credo looks like it could become a winner from the AI infrastructure boom in the long run, but for now, it is a stock I'd prefer to accumulate selectively through dollar-cost averaging rather than following the crowd into momentum swings.