Bloom Energy (BE -1.27%), a developer of solid oxide fuel cells (SOFCs), is expected to post its third-quarter earnings report in the last week of October. Its stock has already risen 2,350% over the past three years, but I wouldn't sell it as long as it reiterates or raises its full-year guidance.
Image source: Getty Images.
How rapidly is Bloom's top-line growth accelerating?
Bloom's year-over-year revenue growth accelerated significantly in the first half of 2026.
|
Metrics |
Q2 2025 |
Q3 2025 |
Q4 2025 |
Q1 2026 |
Q2 2026 |
|---|---|---|---|---|---|
|
Revenue |
$401 million |
$519 million |
$778 million |
$751 million |
$1.07 billion |
|
Growth (YOY) |
20% |
57% |
36% |
130% |
166% |
Data source: Bloom Energy. YOY = Year-over-year.
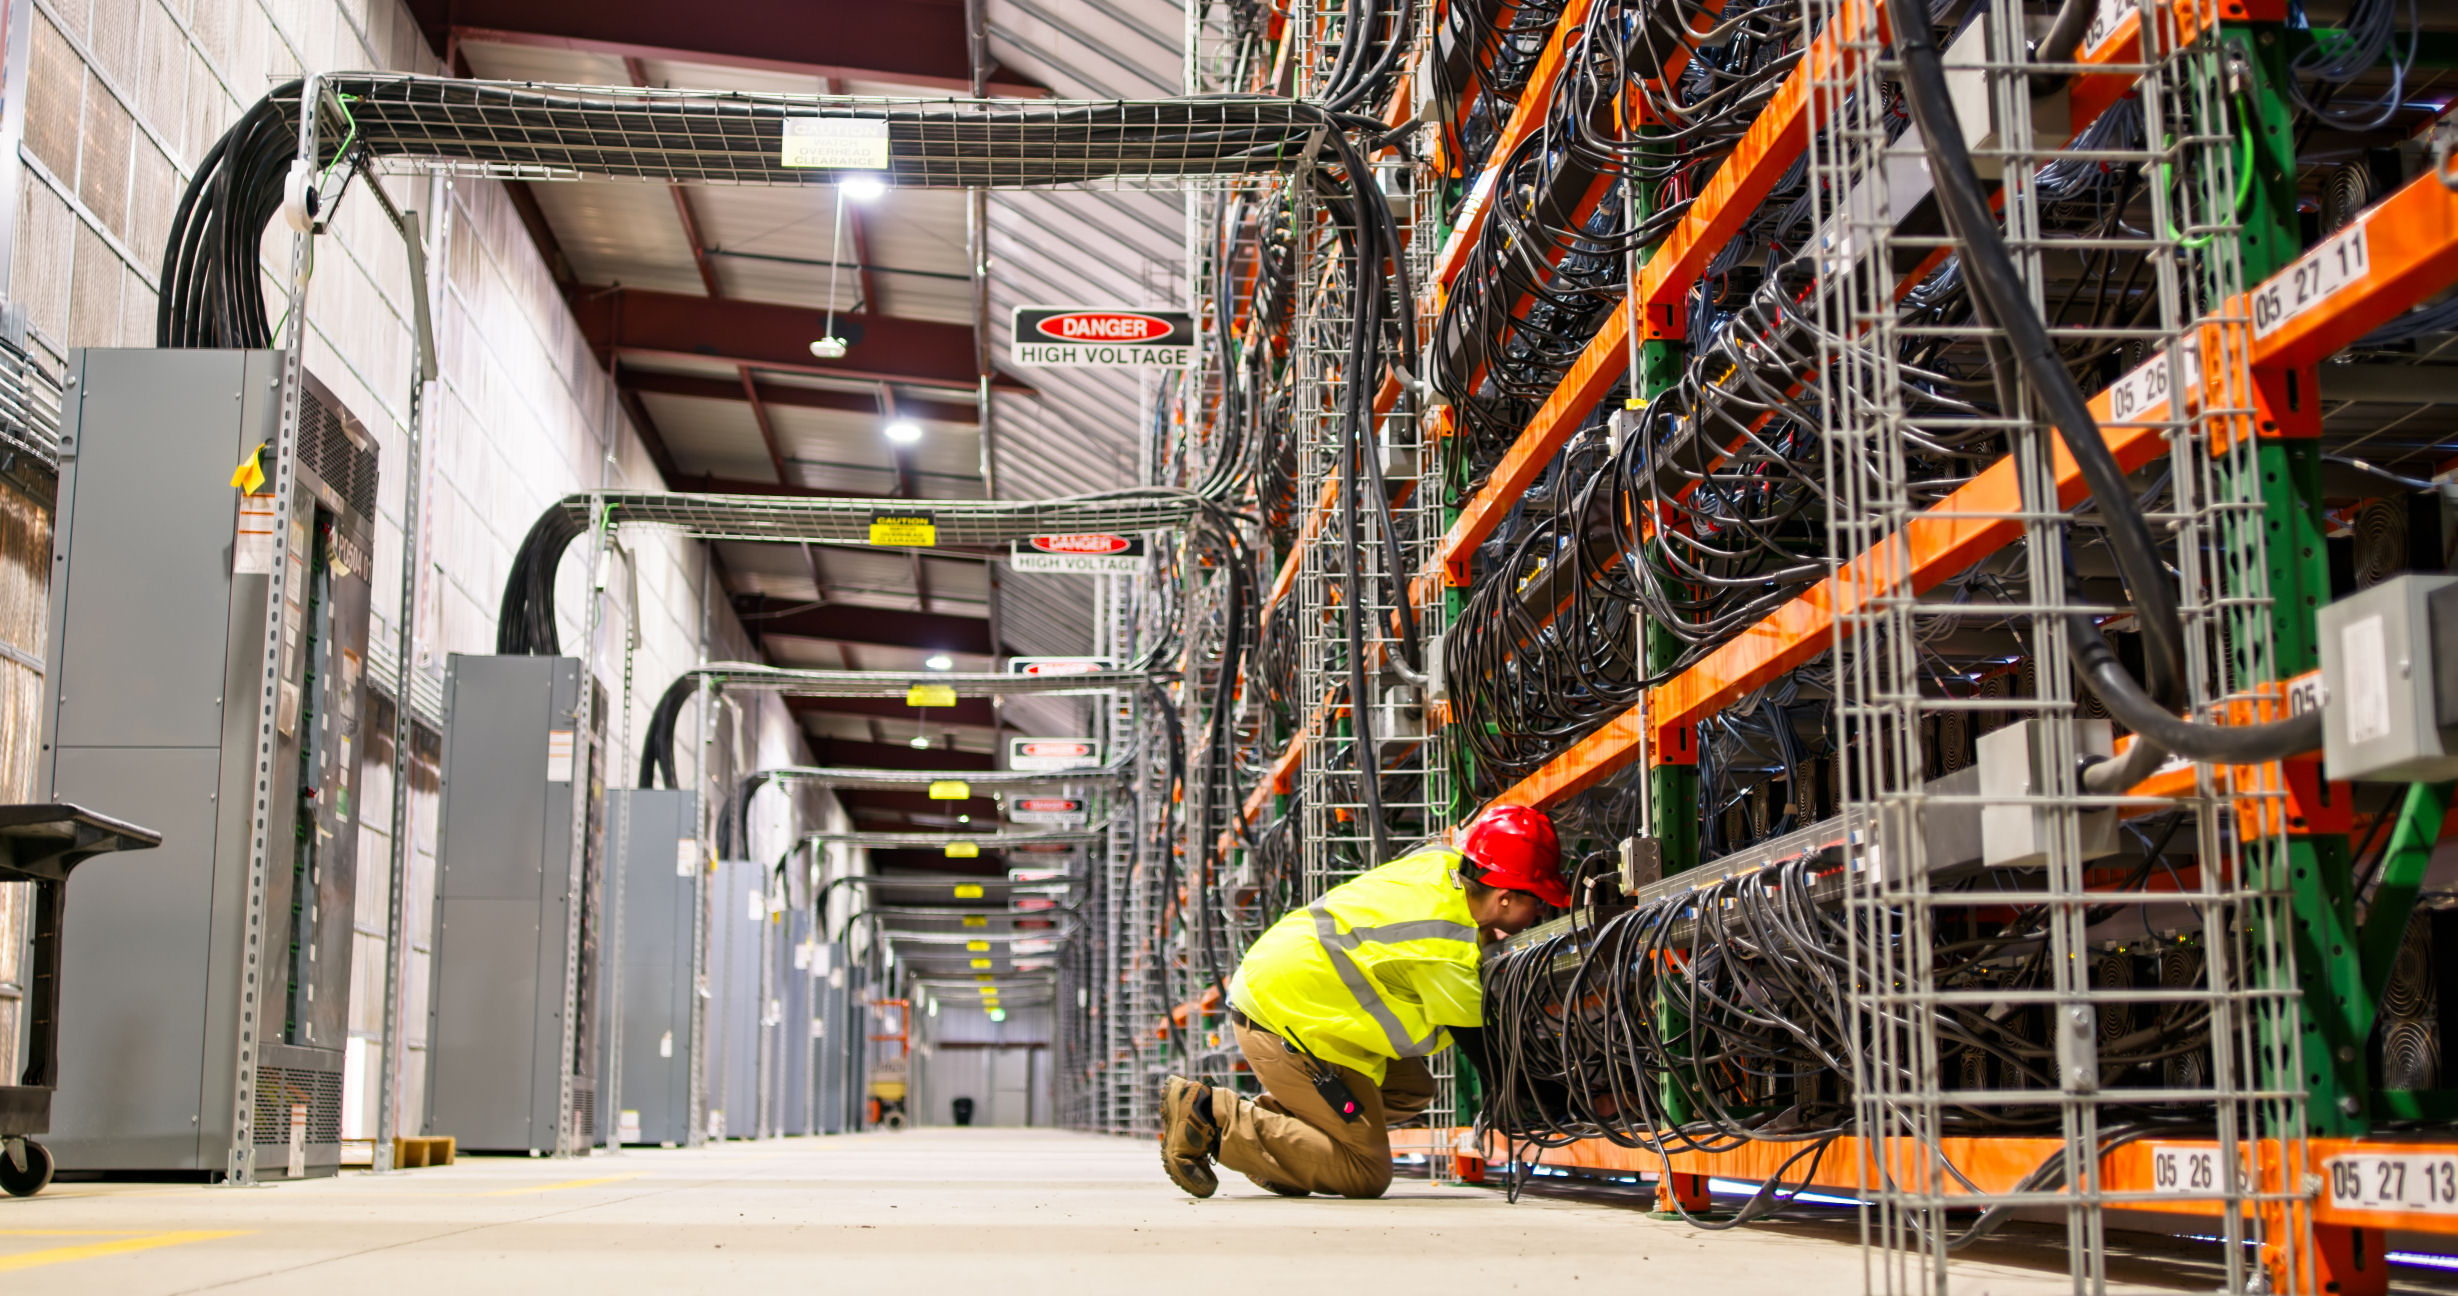
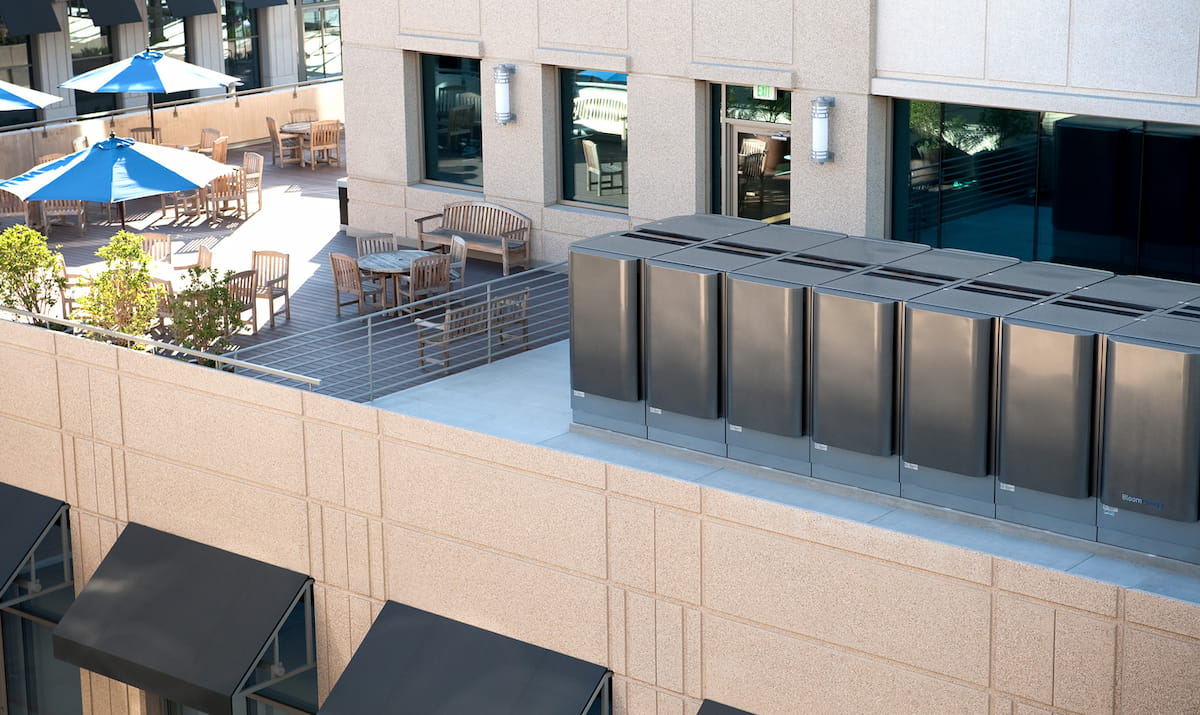
That growth was entirely driven by the surging demand for its SOFC systems -- which convert natural gas, biogas, propane, and hydrogen into electricity without any combustion -- among AI-driven data centers. They can also be deployed rapidly and bypass traditional power grids.
BE Bloom Energy
NYSE · As of 4:00 PM ET 10/15/26

Bloom initially expected its revenue to rise 53%-63% to $3.1 billion-$3.3 billion in 2026. But during its first-quarter report, it raised its outlook to $3.4-$3.8 billion, or 68%-88% growth. In its second-quarter report, it raised its outlook again to $3.9-$4.2 billion, or 93%-108% growth. Many investors will be waiting to see if Bloom can beat analysts' estimates and raise its full-year guidance for the third consecutive time. If that happens, its stock could soar even higher.