Microsoft (MSFT -1.93%) is among the big three cloud computing infrastructure providers and is always included in any list of AI hyperscalers. It's heavily pursuing a massive amount of AI computing power for its internal service, Copilot, while also powering other products like OpenAI's ChatGPT through its cloud computing platform, Azure.
To support this growth, Microsoft is investing heavily in data centers. This year alone, it expects its capital expenditures to hit $175 billion, with most of that going toward constructing and equipping data centers. That is leading to strong growth, but what if this growth is actually hurting its business?
While it may sound odd, Microsoft's business is actually being harmed by the heavy pursuit of its cloud computing empire. Here's why.
Image source: Getty Images.
Microsoft is spending big
At first, you may imagine that the reason that these capital expenditures are hurting Microsoft is that it could be spending that $175 billion in ways that generate a more direct return for shareholders, such as on share buybacks or dividends. But that's not what I'm talking about. In fact, I'm OK with Microsoft spending big on AI because it needs to evolve its business to adapt to the AI age or risk being left behind.
MSFT Microsoft
NASDAQ · As of 4:00 PM ET 10/16/26

Moreover, Microsoft's spending is resulting in strong growth. Azure saw its revenue rise 43% during its latest quarter, passing a $100 billion annual run rate. Additionally, Copilot reached 30 million paid seats, indicating strong adoption of the proprietary AI platform. Overall, Microsoft's revenue rose 18% last quarter.
While that's impressive for a company that's as large as Microsoft, there's a major caveat.
Azure's operating margin likely isn't as good as the rest of Microsoft's business
Unfortunately for investors, Microsoft doesn't publicly break out detailed statistics for its individual segments, such as Azure's operating margins. However, Azure's chief competitors, Amazon Web Services (AWS) (AMZN -1.87%) and Google Cloud from Alphabet (GOOG -2.32%) (GOOGL -2.47%), freely share that information. It's unlikely that Microsoft Azure's margins are much different from theirs, since they operate using essentially the same business model. During the most recent quarter, Google Cloud's operating margin was 36% while AWS' was 39%. So, I think it's highly likely that Azure's operating margins are in the high-30% range.
The problem? Microsoft's operating margin as a whole is well above that range.
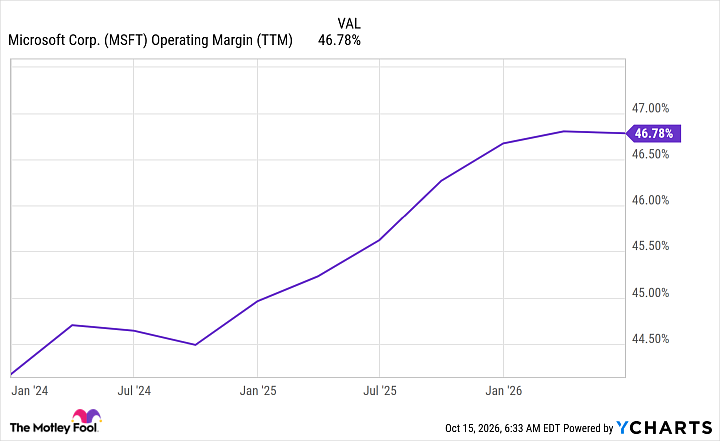
MSFT Operating Margin (TTM) data by YCharts.
So, what does this mean? The more Microsoft invests in its Azure cloud computing business, the more downward pressure this business unit will apply to Microsoft's overall operating margin picture. Investing $175 billion into AI computing capacity may sound like a smart idea, but it will fundamentally shift how Microsoft's operating picture looks five years from now.
Not all growth is created equal, and this lower-margin growth may cause its profits to grow more slowly than revenue.
However, all of this assumes that Azure's operating margins are in line with those of its industry peers, rather than a higher figure like 45%, which would be on par with its overall business. If this is the case, then all of this spending on data centers makes a lot of sense. But if its margins are similar to those of its peers, then it's hurting Microsoft's business.
Regardless, Microsoft needs to spend this money to keep up; otherwise, its cloud business could lose substantial ground to AWS, Google Cloud, and the other players investing heavily in new compute capacity. This puts Microsoft in a bit of a pickle, and it's why I prefer investing in Amazon and Alphabet instead. This could also help explain why No. 2 cloud player Microsoft is a bit more reserved in its spending, with $175 billion budgeted for capital expenditures this year versus No. 3 Alphabet's $200 billion or No. 1 Amazon's $220 billion.
While Microsoft is still a solid AI pick, AI won't have nearly as much of a positive impact on its business as it will on Alphabet and Amazon. I'd rather own those two.