1. Nice Chips, Need a Loan With That?
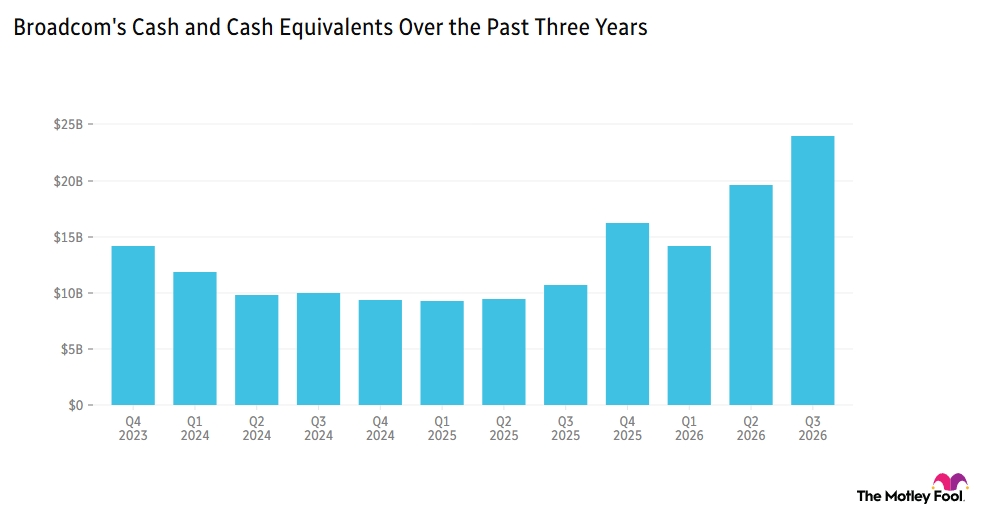
Broadcom (AVGO -4.35%), a recommendation from both Team Rule Breakers and Team Hidden Gems, designs custom chips for the biggest artificial intelligence (AI) labs. Now it's helping them pay for those chips. Broadcom has held early talks on more than $50 billion of financing for custom AI chips it is developing with OpenAI. This follows last week’s $60 billion financing to fund chips for Anthropic.
- Funding loyalty: OpenAI and Anthropic need cash to pay for this much hardware up front. If Broadcom finds them the money, they're less likely to buy chips elsewhere. Off-the-shelf graphics chips (GPUs) sellers don't have this edge. It also makes future orders more predictable. Broadcom expects AI chip revenue of about $230 billion in fiscal year 2028.
- The AI borrowing spree: More of the AI boom is being paid for with borrowed money. Oracle (ORCL -5.48%) is also in talks with lenders about a major chip purchase. SpaceX (SPCX -4.20%) wants to borrow $40 billion to buy Nvidia (NVDA -2.94%) chips. These labs, however, must earn enough from this compute to carry the debt. Broadcom is using a slightly different approach, though: it wants to find lenders for its buyers to win more orders.
2. TSMC Proves AI Demand is Real
Taiwan Semiconductor Manufacturing Company (TSM -3.01%), a Team Hidden Gems recommendation, hit a record this month and is already up 61% this year. TSMC makes the advanced chips inside Nvidia's AI accelerators and Apple's (AAPL +1.11%) iPhones. So when it announces numbers, it gives investors a fresh look at AI demand. Its latest report just revealed how far the AI build-out still has to run.
- Demand has room to run: TSMC’s third-quarter revenue surged 51% to NT$1.49 trillion ($46.7 billion). Management expects 2026 revenue to grow a little over 40% in U.S. dollars, up from its earlier forecast of more than 30%. With major customers projecting rapid sales growth, TSMC shouldn’t have to worry about its order book. Supply of advanced chipmaking capacity remains tight, and more work should shift to the company’s 2-nanometer and 3-nanometer chips.
- An unbeatable edge: Fool contributing analyst Tim Green believes that “demand is so high for AI-related chips that TSMC can grow revenue at an impressive rate even if competitors win some major deals.” He believes that as potential use cases for CPUs and other chips open up, TSMC will be manufacturing many of those chips, “now and in the future.”
3. Chips So Hot, Samsung’s Profit Jumps 9x
Samsung Electronics just offered another powerful reality check on the AI boom. The world's largest memory chipmaker expects a third-quarter operating profit of 107.4 trillion won ($80.1 billion). That’s a record, and a staggering nine-fold growth over last year! Revenue is expected to jump 127% to 195 trillion won.
- Orders are arriving early: What’s driving Samsung’s profits? AI-fueled demand. Customers are buying high-bandwidth memory (HBM), the fast memory stacked beside AI processors, earlier than planned. Memory supply remains tight, and the imbalance is expected to persist. With only three major suppliers, memory makers hold all the pricing power today.
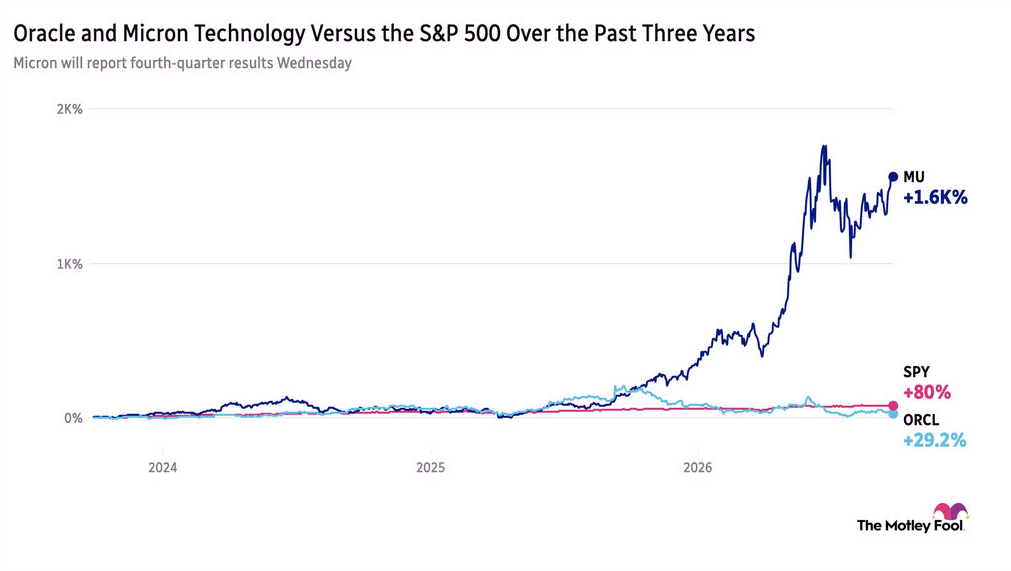
- There’s a catch: Memory is still a cyclical business. Samsung’s shares sit about 25% below their June peak, perhaps because investors know memory can swing from shortage to glut. Big players like Team Rule Breakers recommendation, Micron Technology (MU -4.79%), are rapidly increasing capacity. The thesis holds as long as AI demand absorbs that new supply. We think it will.
4. How We Got Salesforce Right at 100 Times Earnings
Salesforce (CRM +1.44%) traded at 100 times earnings when we recommended it in Rule Breakers in January 2009. Skeptics said the price already assumed too much. They were right about the multiple and wrong about the stock.
That's the trap David Gardner names in Rule Breaker Investing as the sixth trait of a Rule Breaker: overvalued. A true Rule Breaker is hard to value, not impossible, and traditional metrics like the P/E ratio rarely flatter one. The skeptics on CNBC and Yahoo! Finance usually have the numbers right. They just miss what the numbers don't capture.
That's why we treat valuation as a two-step process, not a stop sign:
- Start with the skeptics' case: Take the numbers everyone already sees and figure out exactly what they imply.
- Build the case they're missing: With Salesforce, close to $450 billion in annual software spend was moving to the cloud. The company was also on pace to become the fastest enterprise software business to reach $10 billion in revenue. Our thesis was that the shift mattered more than the multiple. It did.
We'll keep applying that same logic to every Rule Breaker the market calls overvalued. The multiple rarely tells the whole story.
That initial (split-adjusted) $6.76-a-share Rule Breakers recommendation is up around 3,300%, beating the S&P 500 by more than 2,000 percentage points over the same stretch. Salesforce has been recommended 20 further times across TMF services, by both Team RB and Team Hidden Gems.
Shares trade around $225 today. Team Rule Breakers has a 5-year price prediction of $382.16, which works out to an annualized gain of about 11%.
5. Today’s Question!
A stock is trading at 100 times earnings, and everyone calls it a bubble. What will convince you to still buy it?
Discuss with friends and family, or become a member to hear what your fellow Fools are saying!