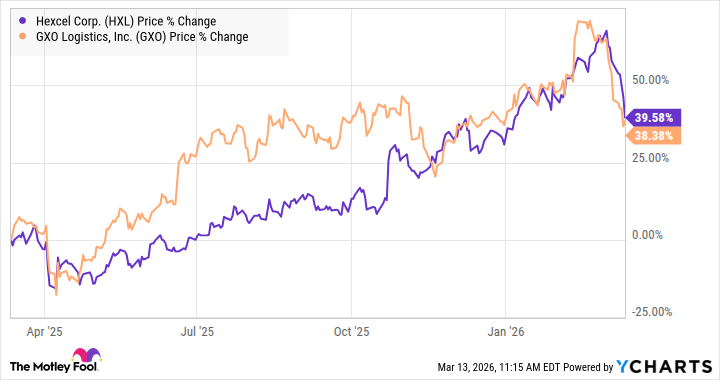
Advanced composites company Hexcel (HXL -2.45%) and contract logistics company GXO Logistics (GXO -0.88%) are vastly different companies, but they share a few commonalities that make them compelling buys for long-term investors. They both have excellent long-term growth drivers, trade at highly attractive valuations, and are on the cusp of a significant cyclical growth pick after a period of weak end markets.
Here's why both are excellent additions to a diversified investor's portfolio.
A few words of warning
Given recent events, it would be remiss not to note that the key drivers of these stocks, a massive ramp-up in aircraft production (Hexcel) and a long-overdue cyclical recovery in the manufacturing sector (GXO), are at risk from a protracted conflict in the Middle East that leads to supply chain and inflationary issues.

Image source: Getty Images.
That said, both have sold off recently, and the headline risk I write off applies across most stocks. As such, these stocks are great buys for investors relatively sanguine about the conflict and looking to buy on the dip it's created.
Hexcel is the future of the aerospace industry
Boeing and Airbus have multiyear backlogs and are both aggressively ramping up production after facing supply chain issues and material shortages in recent years. That's great news for Hexel, which provides advanced lightweight composites to both companies and their subcontractors.
Hexcel's materials offer weight and strength advantages over traditional metals, resulting in reduced fuel costs, emissions, and life cycle costs. As such, Hexcel is a play on increased aircraft production over the next decade. In addition, each generation of new aircraft tends to have more lightweight composites on board, so in theory, Hexcel could grow earnings even if aircraft unit production growth is zero.
An example of the underlying growth is the comparison between the older Boeing 777 (10% of weight in composites) and the newer Boeing 777X (30%). A Boeing 777X can generate up to $2 million in revenue for Hexcel, with an Airbus A350 generating up to $5 million.
Wall Street analysts project Hexcel's sales to grow at a double-digit annual rate through 2028, with earnings up 17.1% annually and free cash flow (FCF) at 25% annually. With Boeing and Airbus holding decade-long backlogs, Hexcel has excellent growth prospects.
Great news for GXO Logistics
The cadence of GXO Logistics growth is demonstrated in the table. The company is a leading contract logistics contractor specializing in e-commerce logistics warehousing. Demand boomed during the lockdown years as customers rushed to invest in e-commerce facilities.
Unfortunately, that growth spurt pushed spending forward, and an inevitable retraction occurred in 2023 and 2024.
|
GXO Logistics |
2021 |
2022 |
2023 |
2024 |
2025 |
2026 |
|---|---|---|---|---|---|---|
|
Organic revenue growth |
15% |
15.4% |
2% |
3% |
3.9% |
4% to 5% |
Data source: GXO presentations.
It gets worse: The supply chain crisis led many companies to build up inventory, and the industrial sector has since drawn down inventory, as confirmed by the U.S. Institute for Supply Management (ISM) Purchasing Managers Index (PMI) and new orders data. Both surveys have indicated contraction since the end of 2023. That said, January and February data have indicated a sharp expansion, and it looks likely that the long-expected cyclical bounce is in place.
That's great news for GXO, and its guidance for mid-single-digit organic growth in 2026 supports that argument. Thinking long term, the growing use of automation, robotics, and artificial intelligence (AI) in warehousing plays to the advantages of outsourcing logistics to specialists like GXO, which know how best to use the technology.
Wall Street analysts project GXO's revenue to grow at a mid-single-digit rate through 2028, with earnings growing 10% annually and FCF at 18% annually.
Image source: Getty Images.
Stocks to buy
Trading at 18.3 times the midpoint of management's FCF guidance for 2026, GXO is an excellent value for a company with such strong long-term growth opportunities. Hexcel is more expensive on a near-term basis (31 times analysts' estimates for FCF in 2026), but provided there isn't any slowdown in commercial aerospace, its long-term growth is assured, and the company looks likely to generate bundles of earnings and cash in the future as aircraft production ramps up.