Bloom Energy (BE +0.22%) stock has slumped about 24% from its recent peak. The catalyst is waning AI optimism due to the potential for resurgent inflation and rising interest rates to slow AI-related capex spending. That could impact demand for Bloom Energy's advanced fuel cells, which are helping accelerate the deployment of AI infrastructure.
Here's a look at whether the hydrogen stock's recent slump makes it impossible to ignore right now.

Image source: The Motley Fool.
Capitalizing on the power surge
AI is driving surging electricity demand. According to a Goldman Sachs estimate, U.S. data center power demand will more than double by 2027, rising from 31 gigawatts (GW) last year to 66 GW. AI data center power demand should continue to grow briskly over the next decade.
Power is one of the biggest bottlenecks in data center development. That plays right into Bloom Energy's hands, as its advanced fuel cells are fast-to-deploy on-site power solutions. For example, last year it delivered a fully operational fuel cell system to Oracle in just 55 days, more than a month ahead of its anticipated 90-day deployment schedule. That impressed the cloud giant, which expanded its strategic partnership with Bloom Energy to deploy up to 2.8 GW of its fuel cells to accelerate its AI infrastructure build-out. Bloom also formed a $5 billion strategic AI infrastructure partnership with Brookfield Asset Management last year to deploy its fuel cells into AI factories (specialized AI data centers).

NYSE: BE
Key Data Points
The investment proposition
Those strategic partnerships are helping power robust growth for Bloom Energy. The company's revenue rocketed 130% in the first quarter to more than $750 million. Meanwhile, it produced $72.2 million in operating income (a $91.3 million jump) and generated $73.6 million in cash from operating activities (a $184.3 million year-over-year increase). Bloom expects to record between $3.4 billion and $3.8 billion in revenue this year, an 80% increase from last year at the midpoint (an acceleration from its initial expectation of 60% revenue growth), with improving profitability.
Bloom Energy's founder and CEO, KR Sridhar, believes his company is "ushering in the era of digital power for the digital age [and] rapidly becoming the standard and "go-to choice" for on-site power." That belief, along with the company's surging revenue and earnings, has helped power a big rise in the stock over the past year. Shares are up nearly 1,000% despite the recent 24% dip.
As a result, Bloom still trades at a premium valuation. It currently fetches nearly 18 times sales and over 110 times earnings. For comparison, that's higher than some of the fast-growing AI semiconductor and memory stocks:
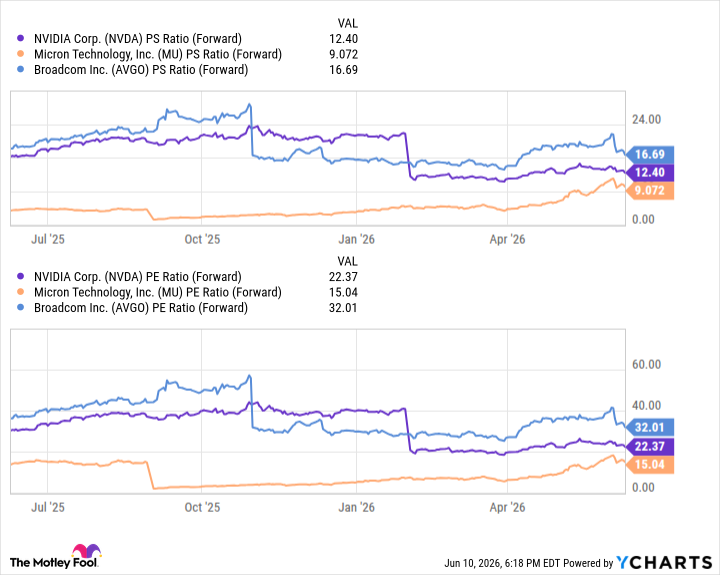
NVDA PS Ratio (Forward) data by YCharts
Bloom Energy would have to continue delivering accelerated growth to justify that valuation multiple. If it runs into a speedbump, shares could take a tumble as investors lower their lofty expectations.
Bloom Energy is intriguing, but expensive
Bloom Energy is becoming the partner of choice for AI data center developers seeking a rapidly deployable power solution. That's driving robust growth for the advanced fuel cell maker. However, investors have already priced in significant growth. So, while the recent decline in Bloom's stock makes it more interesting, it's not yet to the point of being impossible to ignore.