SoundHound AI (SOUN -3.47%) released its second-quarter results last week, and the voice artificial intelligence (AI) company hit a new all-time high for revenue. On top of that, it also boosted its full-year guidance, as the business is getting bigger and benefiting from greater demand for its services.
The business remains unprofitable, but the market appeared bullish on the results nonetheless, with SoundHound's stock rising after the numbers came out. Is the AI stock a good buy in light of the earnings report, and can it be headed higher this year? Let's take a closer look at its financials.

Image source: Getty Images.
SoundHound's top line rose by 45%
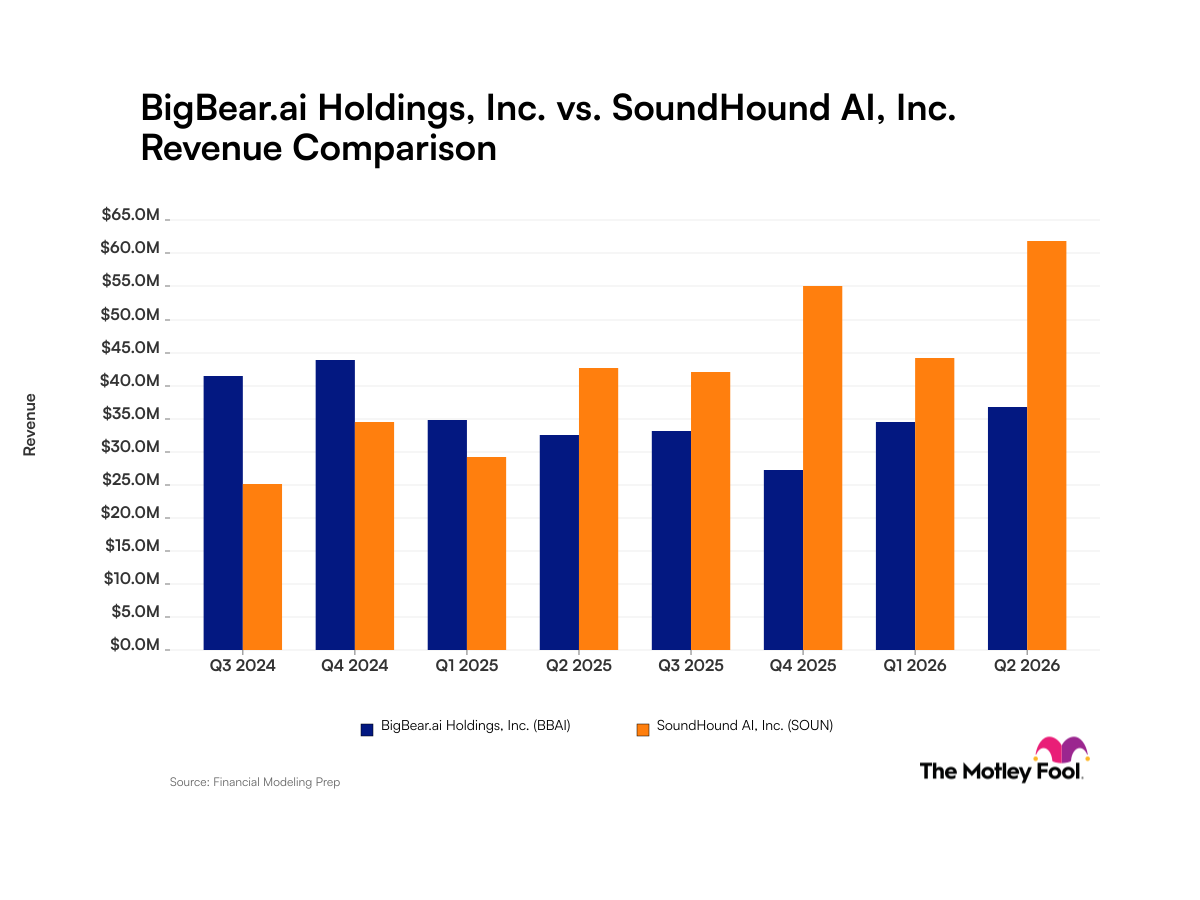
For the period ending June 30, SoundHound's revenue came in at $61.9 million, which represented a year-over-year increase of 45%. That growth is impressive, but investors should be aware that it's also heavily due to acquisitions, as SoundHound has bought up other tech companies in recent years in an effort to grow and diversify its operations. It can be a risky strategy as integrations don't always go smoothly, plus, they add cost and complexity along the way.
The good news is that the company's gross margin improved from 39% a year ago to just over 45% this past quarter. A stronger margin means a lower proportion of revenue goes to cover the cost of goods sold, and that can shrink losses and improve prospects for profitability. And that's just what happened -- SoundHound's net loss of 42.8 million was a big improvement from the $74.7 million loss it incurred in the prior-year period.
For the full year, SoundHound is projecting its revenue to be within a range of $230 million to $260 million. It's an increase on the lower end of the range as SoundHound was previously forecasting at least $225 million in revenue. The top end of the guidance, however, remains unchanged.

NASDAQ: SOUN
Key Data Points
Is SoundHound's stock a buy after these results?
SoundHound posted strong numbers in Q2, but it still incurred a loss and its cash burn remains problematic; over the past six months, the company has used up nearly $60 million just to fund its day-to-day operating activities, up from around $44 million a year ago.
While SoundHound did post some solid top-line growth, acquisitions make it difficult to assess the true organic growth of the business. And although it raised its guidance, it wasn't significant. Meanwhile, it continues to burn through a lot of cash and incur losses. Overall, the earnings report simply wasn't strong enough to prove that it's become a better buy than it was before the latest numbers came out; SoundHound is still a stock I'd hold off on buying.