Buying and holding high-quality companies or exchange-traded funds (ETFs) is an excellent way to build wealth over a long-term time horizon. But some investors prioritize passive income over long-term capital appreciation to supplement retirement income, cover a portion of their expenses, or align with other financial objectives.
Bonds, Treasury Bills (T-Bills), money market funds, and high-yield savings accounts remain go-to solutions for investors seeking passive income outside equities. But the ETF industry has grown rapidly in size and sophistication.
Now, investors can buy covered call ETFs, which cap upside potential in exchange for income. The JPMorgan Equity Premium Income ETF (JEPI +0.50%) and the JPMorgan Nasdaq Equity Premium Income ETF (JEPQ +1.38%) have emerged as two of the largest covered call ETFs by net assets, with the former focusing on S&P 500 (^GSPC +1.09%) components and the latter geared toward components of the Nasdaq-100.
As of Aug. 31, 2026, the JPMorgan Equity Premium Income ETF, which we will refer to simply as JEPI going forward, has a 30-day SEC yield of 7.4%, while JEPQ sports a 30-day SEC yield of 13.3%. Those yields are far higher than what investors can get from T-Bills or bonds -- even with 10-year Treasury yields surpassing 5% for the first time since 2023.
While the S&P 500 yields just 1.1%, there are ETFs that invest in high-yield dividend stocks that yield far more than the index. The Schwab U.S. Dividend Equity ETF (SCHD +0.25%), which we'll refer to as SCHD going forward, is one of the most popular high-yield stock ETFs with $111.9 billion in net assets. Its 30-day SEC yield is just 3.2%, which is solid in its own right but far lower than JEPI and JEPQ.
Here's why investors could realize a higher yield from SCHD than JEPI and JEPQ over the long term and reasons why SCHD has significant advantages over covered call ETFs.
Image source: Getty Images.
Producing monthly dividend income
JEPI and JEPQ actively manage portfolios of equity securities and equity-linked notes (ELNs) and sell covered calls on their respective benchmarks. ELNs combine fixed-income characteristics with exposure to stocks or equity indexes, aiming to achieve a higher yield than bonds, less upside potential than pure-play equities, and offering some downside protection.
Put simply, these ETFs generate yield based on volatility, which is why their monthly dividend payments have varied considerably since JEPI's inception in May 2020 and JEPQ's inception in May 2022.
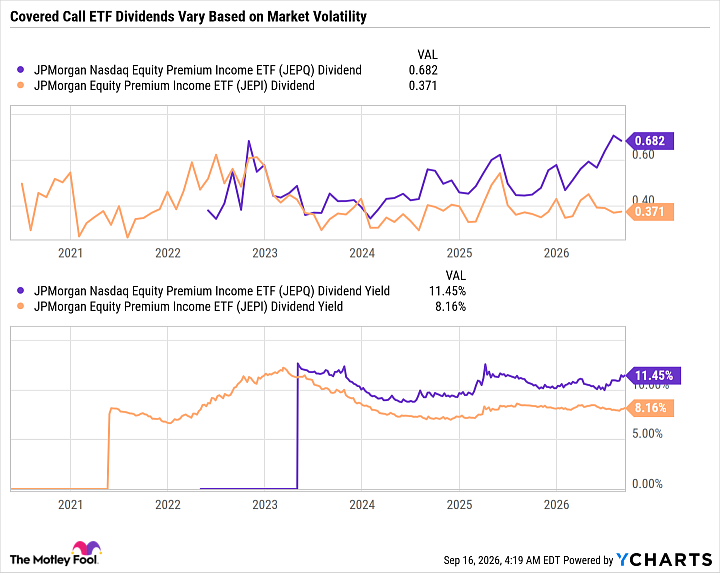
JEPQ Dividend data by YCharts
For example, JEPQ's June 1, 2026, dividend payment was $0.564 per share, but its latest Sept. 1 payment was $0.683 per share because volatility was higher in August than in May. These swings mean investors can't rely on the 30-day SEC yield as a standard for the whole year. Rather, it's better to view annualized yields as a range, roughly 8% to 13% for JEPQ and 6% to 11% for JEPI.
Because JEPI and JEPQ cap upside with call options, they perform best when the market is volatile, which drives up call premiums. But when the major indexes are producing sizable returns, the call premiums generated by JEPI and JEPQ won't be enough to keep pace with the total return of the benchmarks.

NYSEMKT: JEPI
Key Data Points
Compounding passive income over the long-term
SCHD doesn't cap upside potential or use options to boost its yield. Rather, it aims to mirror the performance of the Dow Jones U.S. Dividend 100 Index, which invests in high-yield stocks with track records of consistently paying dividends. The top five holdings in SCHD as of Sept. 15 are Merck, Abbott Laboratories, Chevron, ConocoPhillips, and Coca-Cola. The fund has a 39.6% turnover rate --meaning investors can expect roughly 40% of its holdings to be replaced or traded over a 12-month period.
SCHD has gradually increased its payout over time by rotating into high-yield stocks and ensuring the portfolio is not overly concentrated in a handful of names. Since its inception in October 2011, SCHD has increased over fourfold in value, and its dividend is up over sixfold.
This strategy has massively benefited long-term SCHD holders through a growing share price and dividend per share.
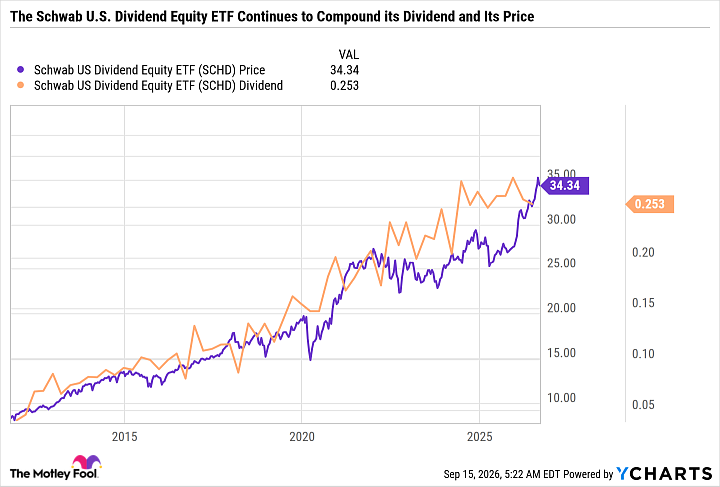
Investors who bought SCHD 10 years ago would have been able to do so for about $14 a share and a $0.08 quarterly dividend compared to the price at the time of this writing of $34.34 per share and the most recent quarterly dividend being $0.253. This means the yield on cost for SCHD investors a decade ago would be around $1 per share per year divided by $14, which is 7.1%.
This exercise goes to show how buying and holding SCHD can benefit a long-term investor with a combination of growing dividend income and potential capital gains -- whereas JEPI and JEPQ are structured to generate limited capital gains and focus on high passive income today rather than gradually increasing it.
SCHD gets the long-term edge
JEPI and JEPQ are ideally suited for investors looking to generate monthly passive income from equities. However, their payouts vary, and the covered calls provide limited downside protection during rapid market sell-offs. They also have 0.35% expense ratios, which is far higher than SCHD's 0.06% expense ratio.
SCHD pays dividends quarterly rather than monthly, so it doesn't have the income-generating size or frequency of JEPI and JEPQ. But it is arguably a better buy for investors who prioritize total return over the long term rather than centering the vast majority of returns on passive income alone.