Investors are largely in agreement that most of Berkshire Hathaway's (BRKA +0.00%) (BRKB +0.02%) stock holdings are solid picks. Every now and then, though, one of its selections raises a few eyebrows.
That's what happened when Berkshire bought 3 million shares of department store chain Macy's (M +1.99%) in the first quarter of this year. Most people appreciate that the struggling company owns a real estate portfolio that may well be worth more than the organization's current market cap of just under $6 billion. To unlock that value, however, the company would need to take on the expensive -- and business-destructive -- headache of winding down at least some of its existing retailing operations, perhaps undermining the value of that real estate in the process.
But maybe Berkshire Hathaway isn't looking at what's since grown to a 7.4 million share/$162 million stake in Macy's as a real estate bet after all. It could be a legitimate turnaround play.

NYSE: M
Key Data Points
Stabilizing
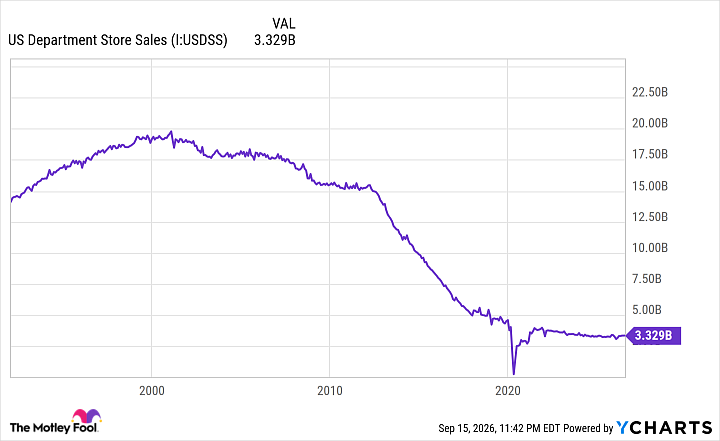
This premise could be difficult to digest given the so-called retail apocalypse that's been underway since the advent of e-commerce. And, anyone who's been keeping close tabs on the brick-and-mortar retailing industry's struggle probably knows that department store chains' revenue peaked in the early 2000s, and has been dwindling ever since.
Now take a closer look at some numbers from the U.S. Census Bureau. While not exactly growing, U.S. department stores' collective sales clearly aren't losing ground any longer either. The worst of this sliver of the retailing industry's degradation may be in the rearview mirror.
US Department Store Sales data by YCharts
This makes some sense. Consumers eventually tire of what's common, and instead look for novelty. The in-store shopping that's been increasingly out of favor for many years has finally become a fresh, entertaining, and somewhat social experience again to a whole new tranche of shoppers. It would also be wrong to not point out that newly reinvented department stores are thriving on affordable luxury that appeals to a more affluent crowd.
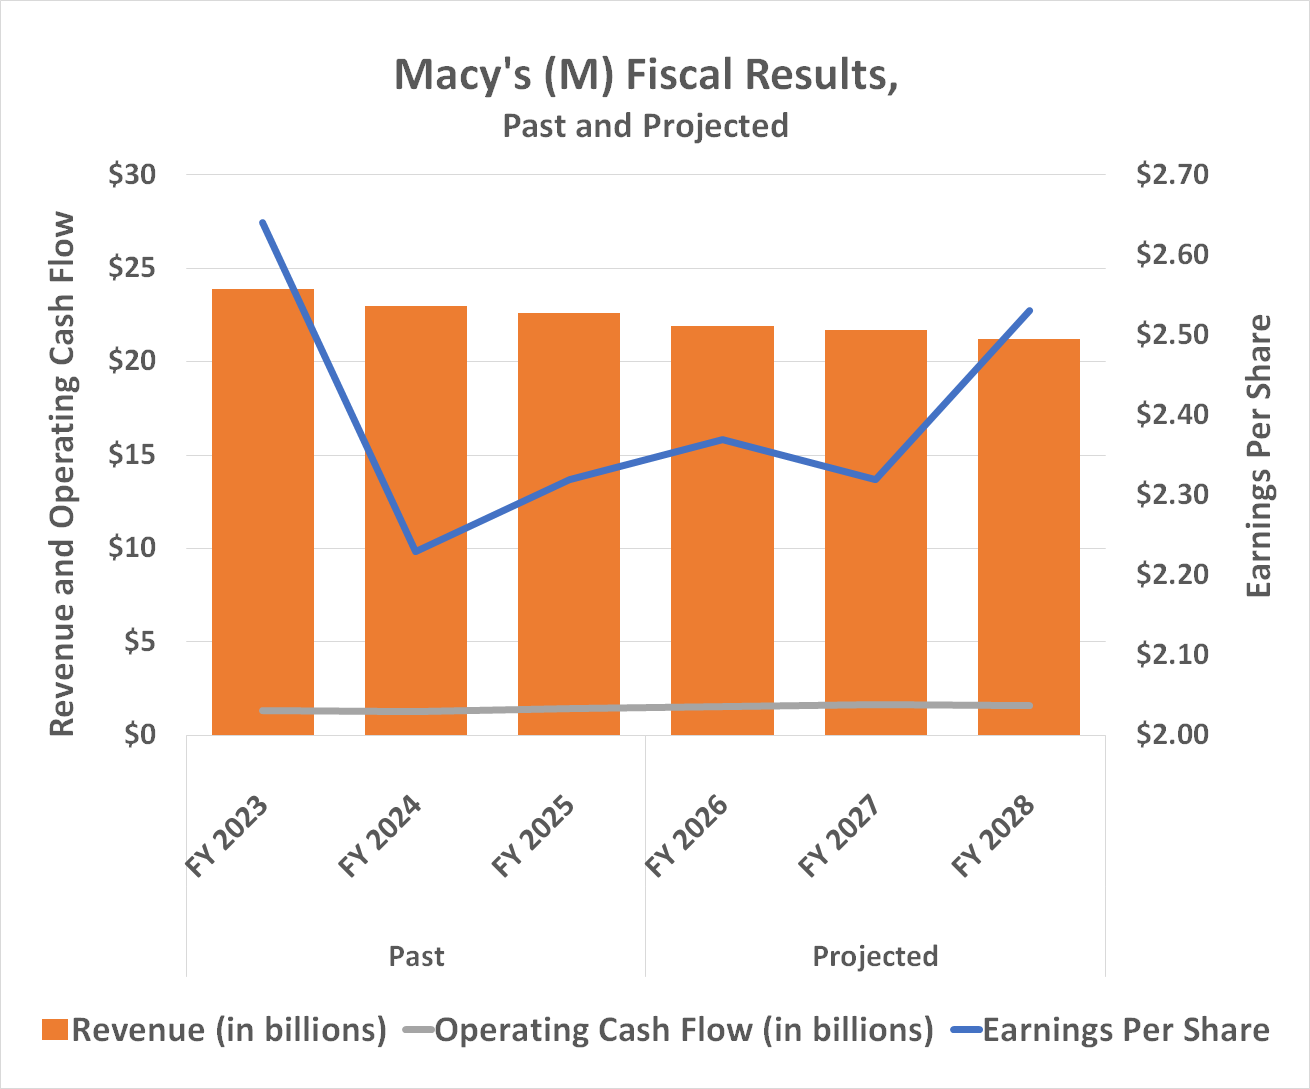
Macy's is participating in the industry's revitalization, too. Last quarter's same-store sales growth was a reasonably healthy 2.7%, marking the fifth straight quarter that comparable sales improved on a year-over-year basis. The iconic retailer raised its full-year revenue and earnings guidance as well. Moreover, although analysts expect the department store chain's revenue to continue to decline slightly at least through 2028, the analyst crowd also expects greater efficiency and smarter merchandising to grow Macy's bottom line during this period.
Data source: Simply Wall St., Morningstar. Chart by author.
Not the value trap that the low P/E suggests it is
There's still work to be done to be sure, and there's no guarantee that the company's business will continue firming up.
There's a respectable glimmer of hope that it can, though... certainly more than there's been in a while. Given that its retailing operation can at least tread water (and as such is no longer a liability), it's also no longer a drag on the value of Macy's real estate.
And from this perspective, the stock's trailing-12-month price-to-earnings ratio of just above 8 makes Macy's a compelling -- even if somewhat speculative -- bargain for Berkshire.