Warfare is evolving, and so are the technologies in the defense spending supply chain. Drones, artificial intelligence (AI), and space are growing in importance, while legacy systems such as aircraft carriers lag.
Many investors look to the large defense contractors as the best bets for this evolving landscape. But there may be some hidden gems that could be better long-term winners in the stock market, such as Canada-based Kraken Robotics (KRKNF -0.69%), which sells components for naval drones and other modern technologies that are seeing growing importance.
The stock is now down 57% from all-time highs, and may be a great stock to pick after completing a transformational merger. Here's why.
KRKNF Kraken Robotics
OTC · As of 3:02 PM ET 10/26/26
Supplier for the future of warfare
Kraken Robotics is not winning direct contracts for naval technology projects, but is the leading component supplier for projects like unmanned underwater vehicles (UUVs). It has battery technology with superior performance in sub-sea environments, communication systems, sonar tracking, positioning equipment, and other capabilities these UUVs need.
The U.S. government and its allies are seeing a growing need for unmanned operations at sea due to increasing disruptions in regions around the world, such as the Persian Gulf, the Baltic Sea, and the Taiwan Strait. Companies like California-based Anduril Industries are building fleets of UUVs that will use Kraken's batteries.
This has led to solid revenue growth for Kraken, along with plenty of new contracts signed this year. Revenue was 109 million Canadian dollar over the past 12 months, which is many multiples of what it generated just a few years ago.
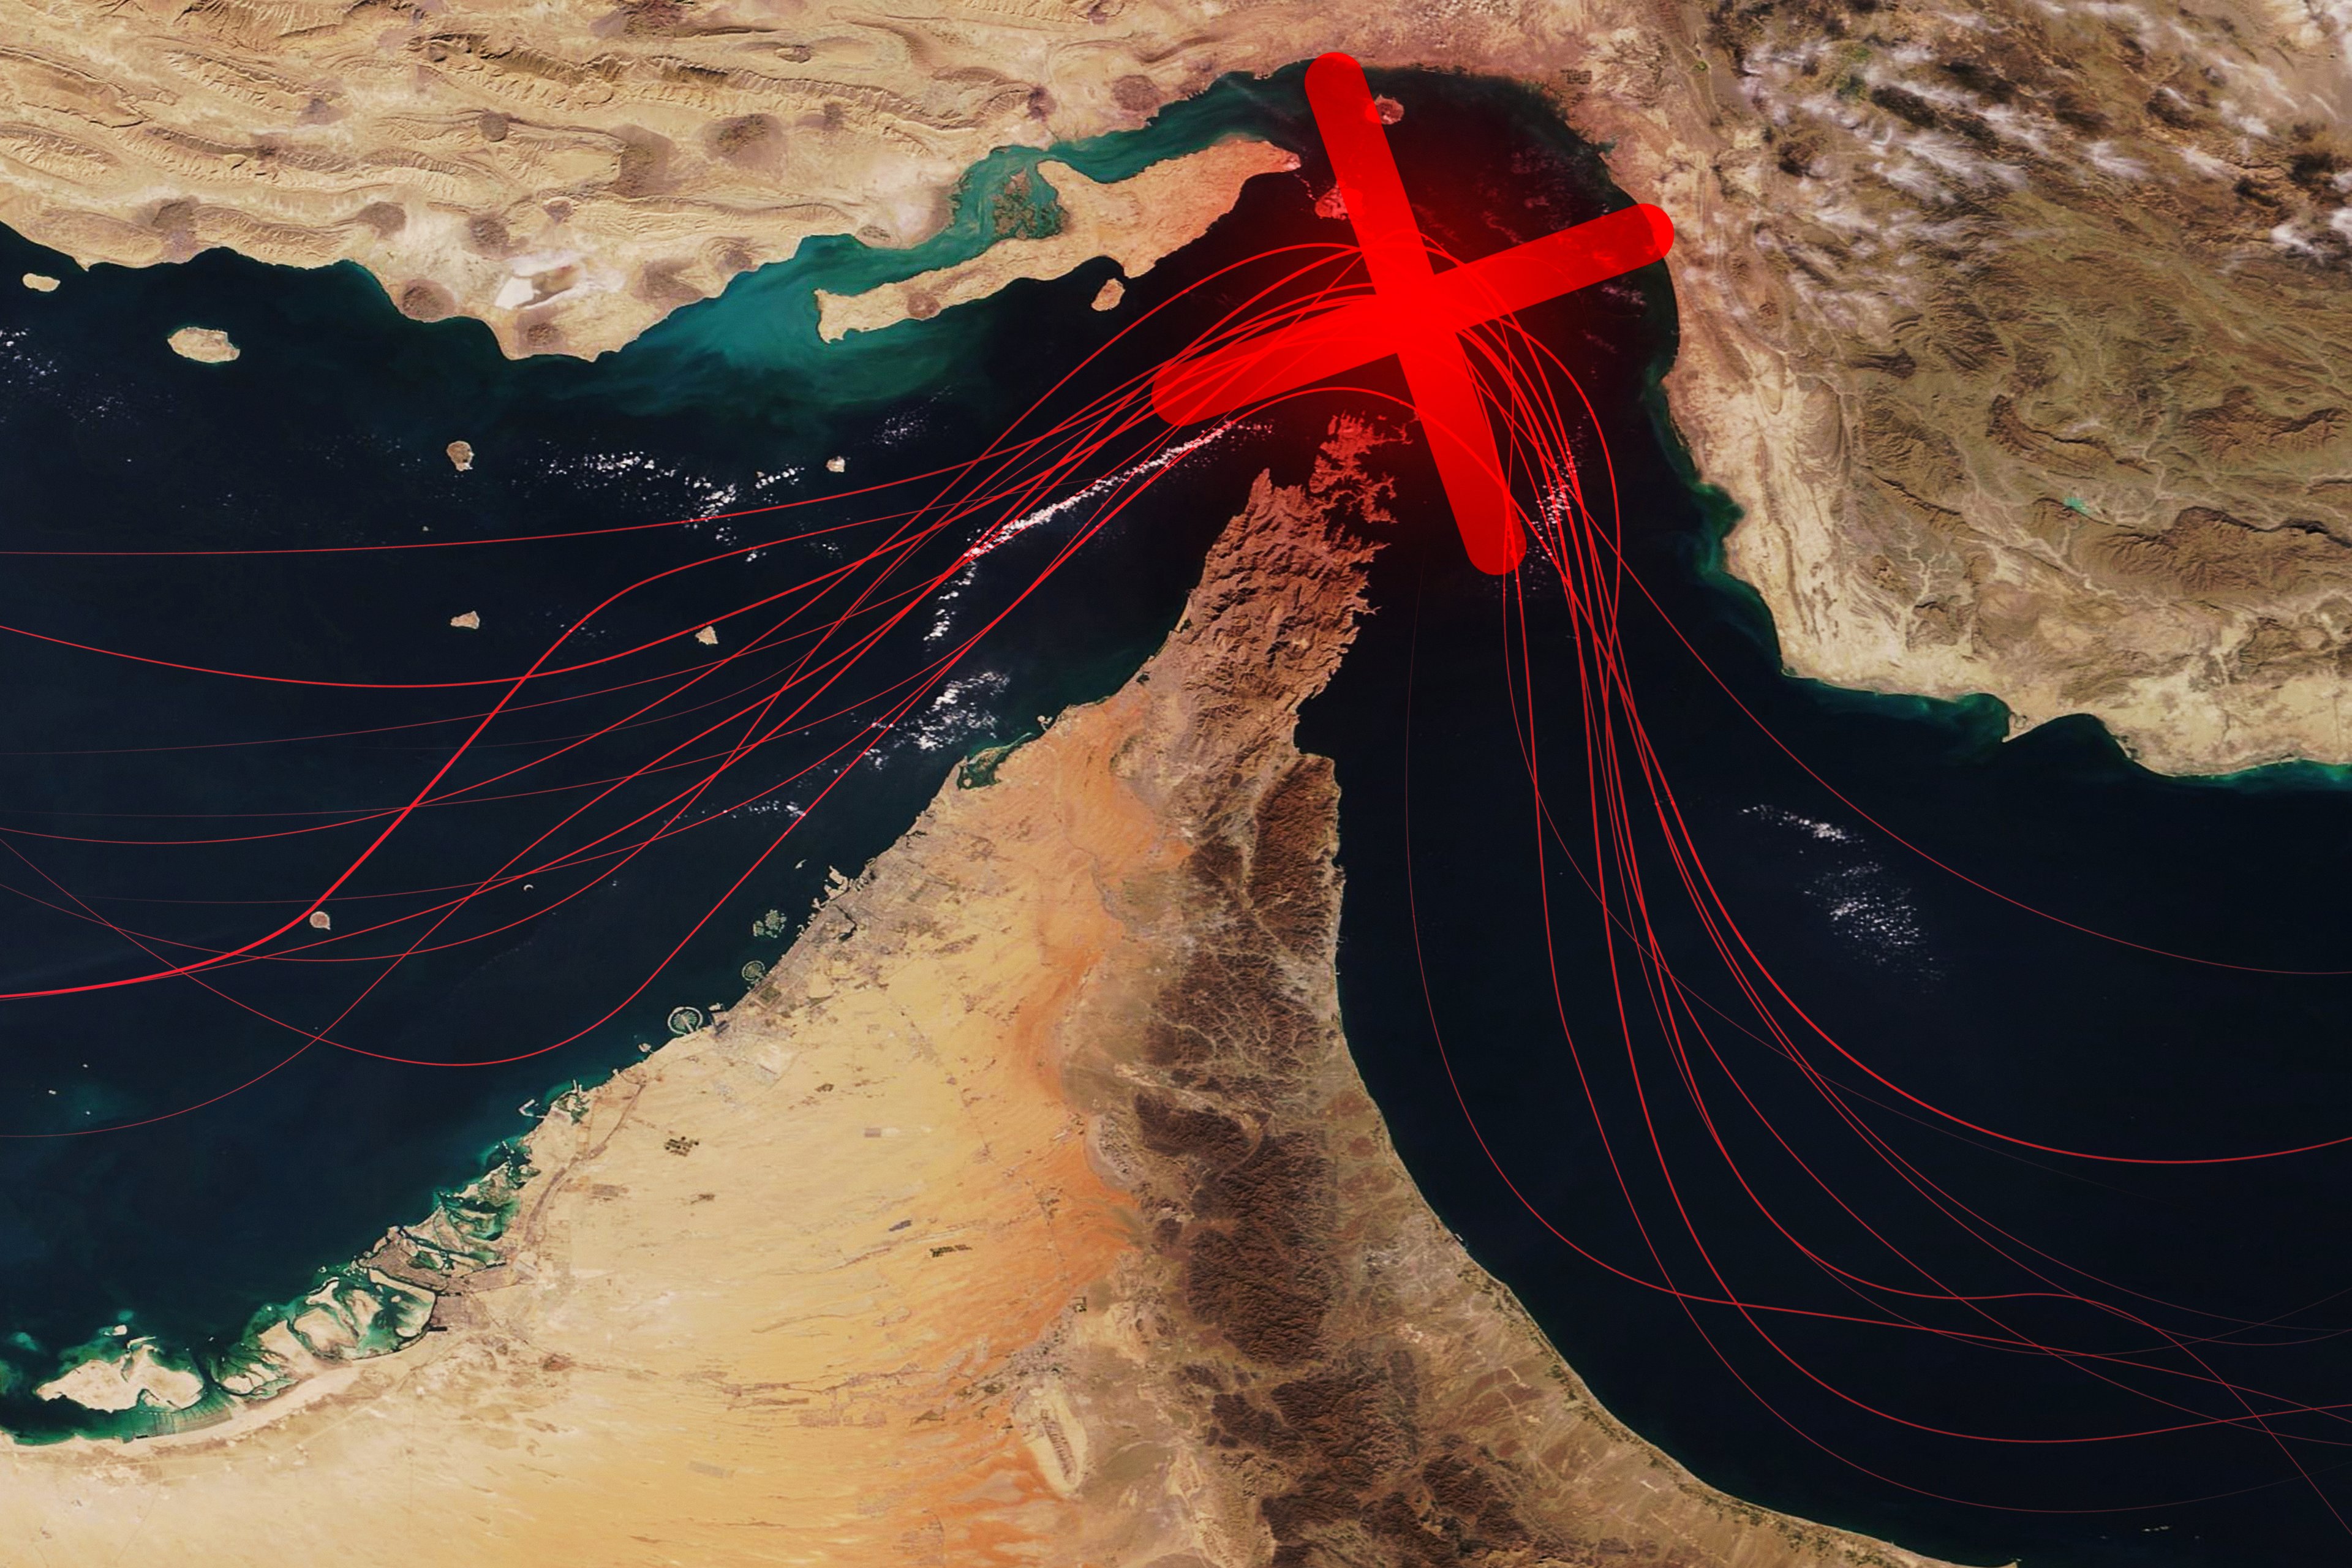
Image source: Getty Images.
Merger and financial projections
To take the next step toward scaling as a supplier, Kraken recently merged with another sub-supplier in naval warfare, the Covelya Group, with the merger closing this summer. The company will bring new technologies and a large revenue boost for Kraken through the rest of this year and into 2027.
This year, with half a year's contribution from Covelya Group, Kraken expects consolidated revenue to grow to CA$290-320 million for full-year 2026, with gross margins of around 60%. This has greatly accelerated its revenue scale, with more growth expected in the years ahead.
Long-term, the U.S. government, NATO allies, and Asian Pacific allies are planning to increase spending on projects such as underwater drones, which should lead to steady demand for Kraken Robotics in the years ahead. By 2030, I wouldn't be surprised if its revenue reached CA$1 billion.
Is Kraken Robotics stock cheap?
After this drawdown, Kraken Robotics now trades at a market cap of CA$1.4 billion. This is an expensive valuation compared to its trailing figures, but it could be an attractive multiple if we look at forward projections.
In 2027, it is plausible that Kraken's revenue will exceed CA$500 million due to growth engines in underwater warfare, with analysts calling for a consensus figure of over CA$550 million today.
Based on Kraken's 60% gross margin, it is plausible that the business could generate a 20% operating margin at maturity. In fact, it already has a history of strong margins, with a 15% margin figure back in 2024 at a much lower revenue level.
20% margins on CA$500 million in revenue is CA$100 million in annual earnings, or a 14x multiple vs. the current market capitalization. Long-term, if revenue gets to CA$1 billion, that is CA$200 million in earnings, or just a 7x multiple. A stock with growth prospects like Kraken deserves to trade at a much larger premium to earnings.
Taking this into mind, now looks like a good time to buy the dip on Kraken Robotics stock and hold for the next decade.