The S&P 500's (^GSPC +0.73%) dividend yield is near historic lows at roughly 1%. That's largely because stock prices have climbed faster than dividends, which pushes yields down. The index's heavy weighting toward big tech companies -- many of which pay modest dividends (or none at all) -- also keeps the market-weighted average yield thin.
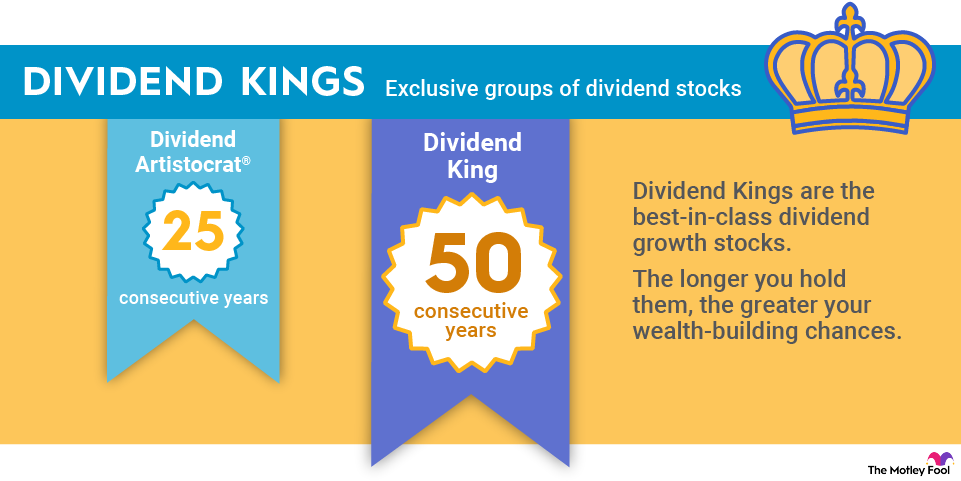
By comparison, PepsiCo's (PEP +0.23%) forward dividend yield is 4.66% -- more than four times the market average. It has raised its dividend for more than 50 straight years, earning it Dividend King status, meaning a company that has raised its payout for 50 years or more. And it's still investing to drive future growth.
Here are three reasons PepsiCo looks like a solid income investment for 2026 and beyond.
Image source: Getty Images.
1. Growing free cash flow can keep PepsiCo's 54-year dividend growth streak going
PepsiCo raised its dividend by 4% earlier this year, extending its streak to 54 consecutive annual increases. The company typically prioritizes capital allocation by investing in the business first, then paying dividends, and using remaining cash for acquisitions and share repurchases.
Over the past year, it paid out 84% of free cash flow as dividends. That's elevated, but there are reasons it could improve. PepsiCo's trailing-12-month free cash flow reached a record $9.2 billion, but nearly $1 billion in tax payments is set to roll off in 2027, which should free up additional cash.
Management also expects to moderate capital spending, leaving more room for dividends. Taken together, that should help protect the dividend while still funding the investments needed to keep the business growing.

NASDAQ: PEP
Key Data Points
2. PepsiCo targets higher margins and earnings growth
Margin expansion would be another tailwind for free cash flow and dividend growth. Management aims to lift operating margin by at least 100 basis points (one percentage point) over the next three years.
International performance could help as well. In the second quarter, international operating margin rose a full percentage point as that segment reached $40 billion in annualized revenue. Over time, management is targeting high-single-digit earnings growth.
3. Sales volume growing at the fastest pace since 2022
PepsiCo's global food volumes rose 3% year over year in the second quarter, while beverage volumes increased 2% -- its strongest volume growth since 2022.
The food business, in particular, could improve over the long run. The company plans to refresh key brands, including Lay's, Tostitos, and Gatorade, with more zero-sugar options and higher-quality ingredients, which could drive greater demand.
Overall, this Dividend King offers a yield about 4x the S&P 500 average while pursuing initiatives to build a faster-growing, more profitable business. After falling 34% from its previous high, Pepsi stock may be undervalued and positioned for a rebound in 2027.