When looking for a fantastic investment, investors often look at a company's moat or competitive advantage. If a company has a strong one, this could almost guarantee years of revenue growth, as it means rivals will find it difficult, and sometimes even impossible, to upset this player. One tech giant in particular has a rock-solid moat as the only company around offering something in high demand.
This company is ASML (ASML -0.40%), the only maker of extreme ultraviolet lithography systems (EUV). These systems are a key part of advanced chip manufacturing, and considering the high demand for artificial intelligence (AI) chips these days, it's clear that ASML's future looks incredibly bright. How does this translate into growth for you as an investor? Here's what $1,000 invested today could be worth by 2030.
Image source: Getty Images.
Why rivals likely won't beat ASML
So, first let's talk a bit more about ASML's business. As mentioned, it is the only maker of EUV, offering it a significant moat. It would require years of research and development and significant investment for another company to create a rival platform, and this means it's very likely that ASML will maintain its leadership in this area. ASML invested about $6.7 billion in EUV research and development over 17 years to build the platform that it offers today.
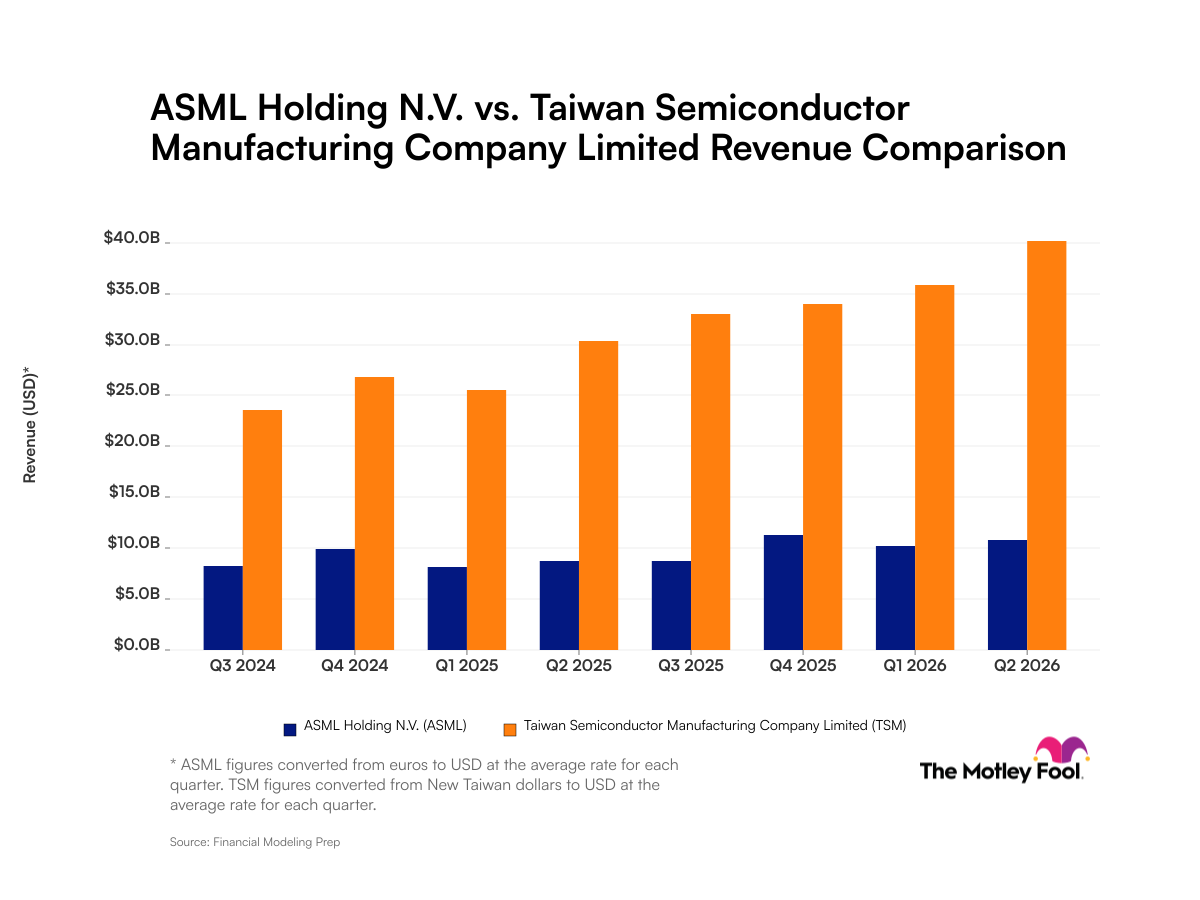
Meanwhile, EUV demand is booming as it's a crucial element in the manufacturing of advanced chips. EUV uses an invisible light with an extremely small wavelength to print patterns from a large blueprint onto silicon chips. Like a stencil, EUV sets the stage for the placement of transistors. Taiwan Semiconductor Manufacturing, the maker of the world's most well-known chips from designers like Nvidia and Advanced Micro Devices, uses ASML's EUV machines as part of the manufacturing process.
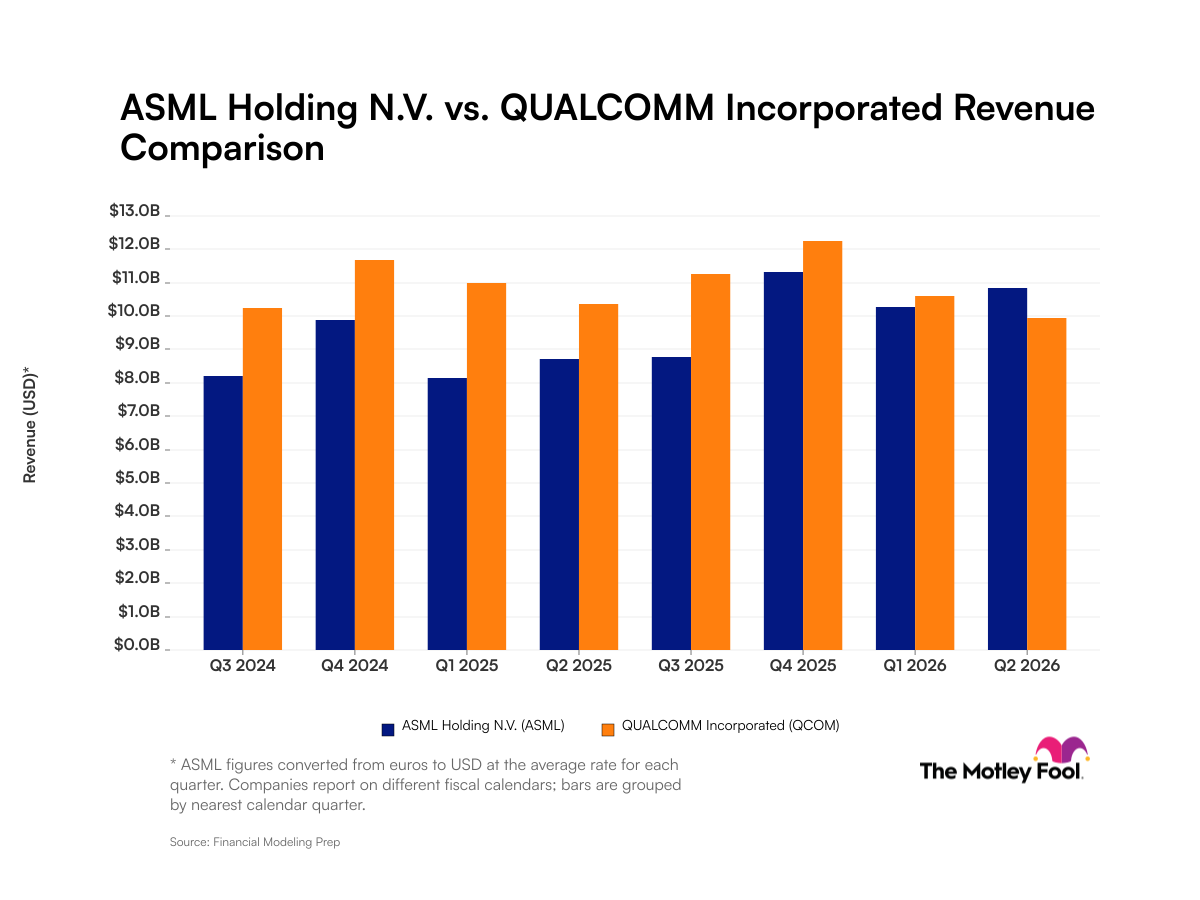
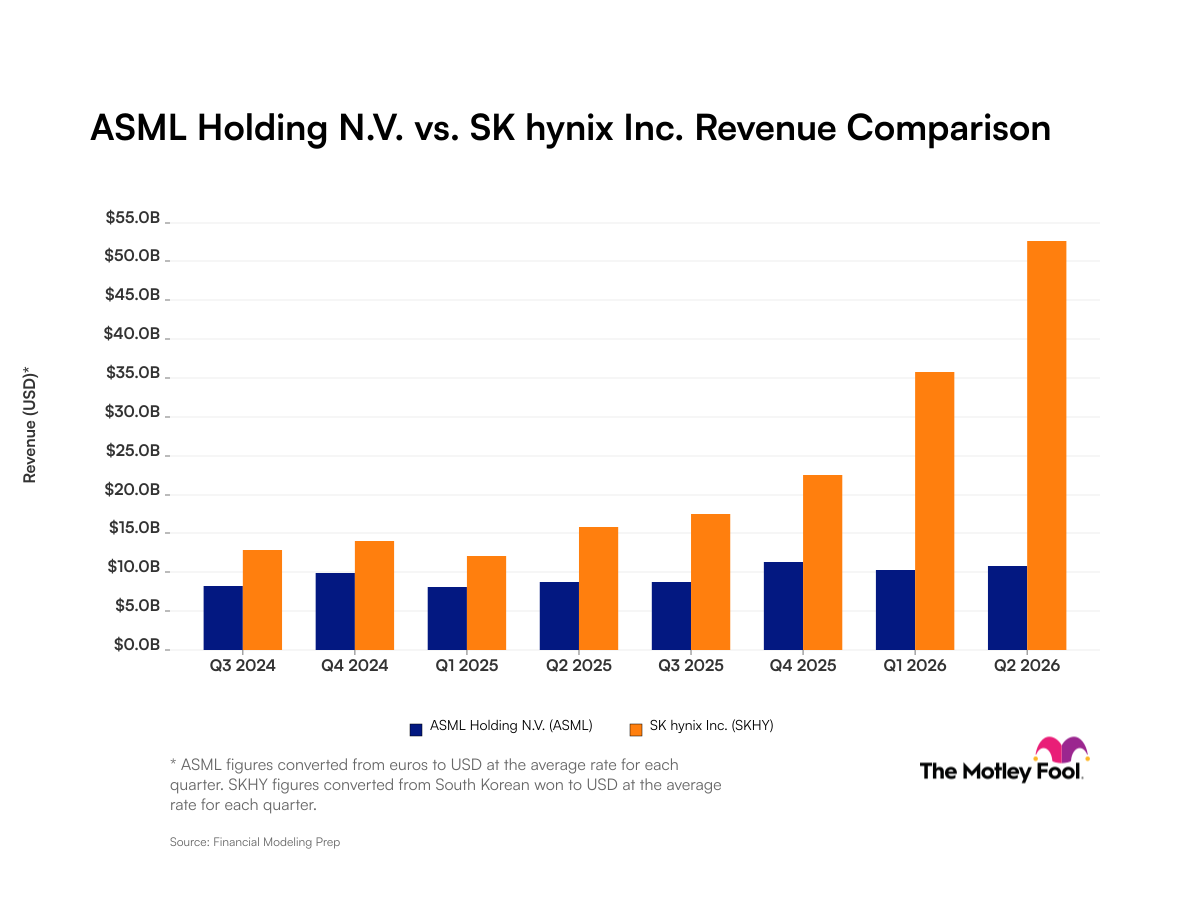
Considering the soaring demand for advanced chips, it's not surprising that ASML's earnings have taken off. Net sales last year totaled about $36 billion, and the company expects sales this year to rise to the range of $48 billion to $50 billion, and that's at a gross margin between 54% and 56%, showing high profitability on sales.
It's also important to remember that ASML dominates the deep ultraviolet lithography (DUV) market, too, competing with Nikon and Canon. DUV is an older technology, but it is widely used across the chip market and contributes significantly to growth at ASML.
All of this has translated into gains for the stock -- it's climbed 80% over the past year.

NASDAQ: ASML
Key Data Points
ASML could deliver $90 billion in revenue in 2030
Now, speaking of growth, let's consider what may happen if we invest $1,000 in ASML stock today. What will that investment be worth in five years? As a starting point, let's consider ASML's potential growth over that time period. The company could deliver revenue of more than 80 billion euros, according to Morningstar. That represents $90 billion, considering today's euro-dollar exchange rates.
ASML's trailing 12-month price-to-sales ratio is almost 17 right now, but it's climbed to nearly 20 in recent times. Considering the potentially $90 billion in sales in 2030, ASML could see its stock price advance 176% to $5,000. That would leave the stock trading at 21x trailing 12-month sales, on par with today's valuation levels.
If this exact scenario played out, your $1,000 investment would be worth $2,760 by 2030.
Of course, it's important to remember that this is just one potential outcome, based on a possible revenue figure and respecting a certain valuation range. The stock could surprise us in either direction, either lagging behind this prediction or soaring well past it.
What does this mean for you as an investor? Though it's interesting to calculate a potential outcome, it's more important to focus on a company's business and long-term prospects. If the stock price surprises us with a bigger win sooner than expected, that's fantastic, but if not, that's OK. What is most important is the company's ability to generate growth over time, as this most often results in a long-term win for investors. And in that department, there's reason to be optimistic about ASML, given its outstanding moat in the high-growth semiconductor space.