Are investors overlooking obvious technology investments right in front of their faces? Stocks like Nvidia and Palantir Technologies have soared in recent years, lifting the S&P 500 index higher. However, some strong technology companies' stocks have been relative laggards during that time.
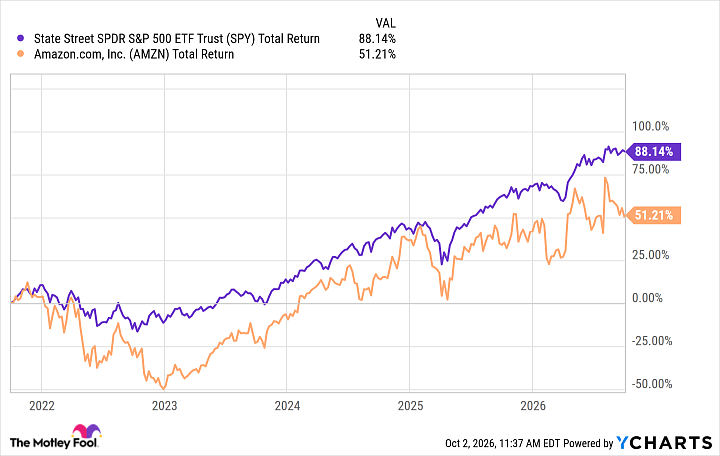
One example is Amazon (AMZN +1.95%). Over the last five years, its shares are up 51%, compared with an 88% gain for the index. I think the market is massively underappreciating Amazon's potential as an artificial intelligence (AI) winner.
Here's why I view Amazon as the most undervalued AI play for your portfolio in 2027 and beyond.
Image source: Getty Images.
Massive cloud acceleration
Evercore's Mark Mahaney has a price target of $355 on Amazon stock, which currently trades at around $250. He sees its potential to flip from AI laggard to AI winner over the coming quarters.

NASDAQ: AMZN
Key Data Points
Why? Because of how much Amazon Web Services (AWS) is benefiting from the AI infrastructure boom. Amazon has chosen not to develop its own cutting-edge AI model, but AWS is the world's No. 1 cloud infrastructure player, and it aims to remain the data center, IT layer, and platform provider of choice for the training and deployment of AI services.
Last quarter, AWS revenue grew 37% year over year to $42.2 billion, a huge acceleration from recent quarters. With AWS' backlog growing and Amazon pouring capital into new data centers, investors should expect this growth to continue compounding over the coming quarters.
Don't forget e-commerce automation and advertising
AI can bolster Amazon's e-commerce, retail, and services divisions in different ways.
First, it is applying AI search tools to its website to help customers parse ordering choices more efficiently. Second, it's using AI to help brands create sponsored ads and more effectively target their advertisements. Third, Amazon is layering in automation and AI across its supply chain, including warehouse sorting, self-driving delivery, and drone delivery. The last one is a longer-term investment, but could lead to huge efficiency gains for Amazon in the years ahead.
Amazon's North America retail business grew 16% last quarter to $116 billion. Margins remain quite thin for that segment, at 7.4% over the last 12 months, but that is due in part to the investments it is making in automation and AI. Over the longer term, there should be immense operating leverage across this supply chain, leading to a nice expansion of segment margins.
SPY Total Return Level data by YCharts.
Why Amazon is a cheap stock today
If you factor in everything, Amazon stock looks relatively cheap, even with a market cap of $2.7 trillion.
First, consider that AWS now boasts an annualized revenue rate (ARR) of $169 billion. If this figure grows by 37% again over the next 12 months, it would reach $232 billion by this time next year. In the long term, revenue growth will slow, but there is still significant potential at AWS. Plus, it has a profit margin of roughly 35%, which equates to around $81 billion in operating earnings.
The rest of Amazon -- including its international segment -- is currently generating $627 billion in revenue. I think this figure could grow to around $800 billion over the next two to three years, with nice margin expansions due to the factors discussed above.
A 10% consolidated margin on $800 billion in revenue would amount to $80 billion in earnings for the non-AWS businesses, giving the company $161 billion in total earnings. Based on that figure, its current forward earnings multiple is just 17, which suggests that Amazon stock is undervalued if you buy and hold for the next few years, let alone the long term.