Trading at just 6 times forward earnings and with a 6% forward dividend yield, Comcast (CMCSA -1.25%) stock is arguably priced for disaster. But is the super-low valuation of this telecommunications and media giant warranted, or have investors overreacted by giving the stock such a "value trap" valuation?
On one hand, there is justification for caution, given the company's ongoing broadband subscriber losses. On the other hand, with Comcast's upcoming plans to spin off the rest of its media assets, it may be on the verge of unlocking its underlying value. Or is it?
Let's take a closer look to see whether this is a prime deep-value opportunity or a name that's likely to remain a value-and-yield trap.
Image source: Getty Images.
Comcast, valuation, and market skepticism
Broadband subscriber losses and their impact on Comcast's profitability remain key drivers of the stock's poor performance and low valuation. Comcast stopped reporting subscriber numbers this year, but as noted in a recent downgrade by KeyBanc analyst Brandon Nispel, the company is on track to lose 558,000 broadband subscribers in 2026, with another 665,000 expected to "cut the cord" with Comcast in 2027.
Nispel is not alone in his downbeat view on Comcast's dwindling subscriber base. Based on analyst estimates for 2026 and 2027 earnings, it's clear that declining subscribers, and thus declining revenue and earnings for Comcast, remain highly anticipated. Forecasts call for earnings of $3.48 and $3.59 per share in 2026 and 2027, respectively, down from $4.10 per share in 2025.
Still, it's not as if this is the sole factor at play with Comcast shares right now. After last year's spinoff of Versant Media Group (VSNT -1.20%), a new entity that owns Comcast's former cable television business, Comcast plans to spin off NBCUniversal and Sky into a separate public company soon.
Analysts anticipate the market rerating these businesses separately, leading to share appreciation, even if earnings aren't set to amaze anytime soon. These bullish price targets range from $31 to $37 per share.
Value unlock remains highly speculative
A major reason so many analysts still believe better times lie ahead for the stock price is recent merger activity among telecom stocks and media stocks. Following Charter Communications' purchase of Cox's cable business, there is much speculation that Comcast will merge with Charter, creating new opportunities for cost and growth synergies.
CMCSA Comcast
NASDAQ · As of 4:00 PM ET 10/21/26
After Skydance (SKYD +10.85%) purchases Warner Bros. Discovery, there's also much speculation that a larger media conglomerate could swallow up NBCUniversal after it becomes independent. However, there are no guarantees. It's unclear whether a Comcast-Charter merger would get through antitrust scrutiny.
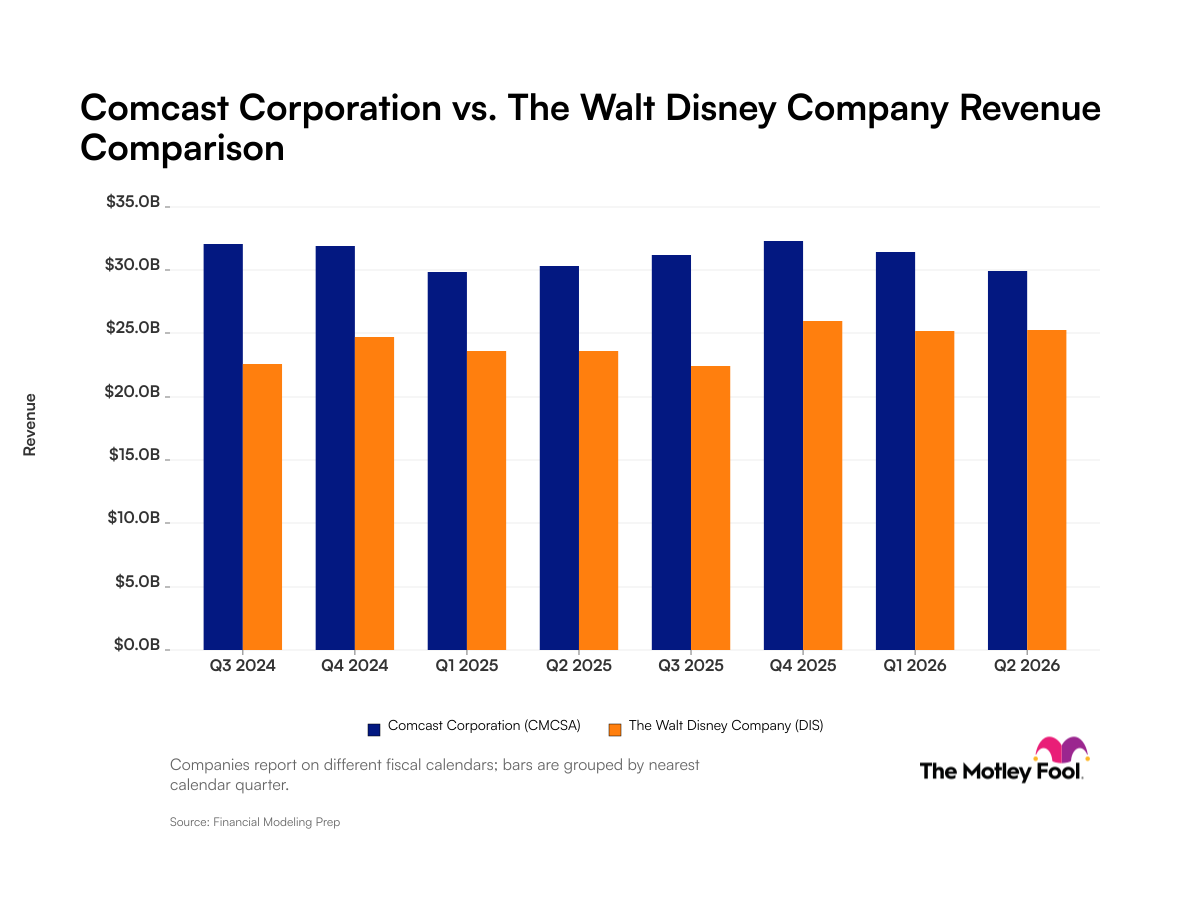
After completing such a big transaction, I don't see Skydance rushing in to buy NBCUniversal, either. Other companies could bid for NBCUniversal, but given how peers like Walt Disney already own competing broadcast networks, finding a deep-pocketed buyer may be harder than you think.
In short, consider this catalyst highly speculative. Meanwhile, subscriber losses remain a concern, calling into question the sell side's current view that Comcast's earnings could stabilize in the coming year. Until it can fully shake off this perception, err on the side of caution and avoid the effort to bottom-fish Comcast stock.