Shares of Abbott Laboratories (ABT +1.13%) recently plunged after the company announced its fourth-quarter results. Over the trailing 12 months, the stock is down 16%. Some might choose to stay away from Abbott given some recent challenges. However, Abbott's stock still remains attractive, especially for dividend-seeking investors. Here is why.
Abbott's quarterly update
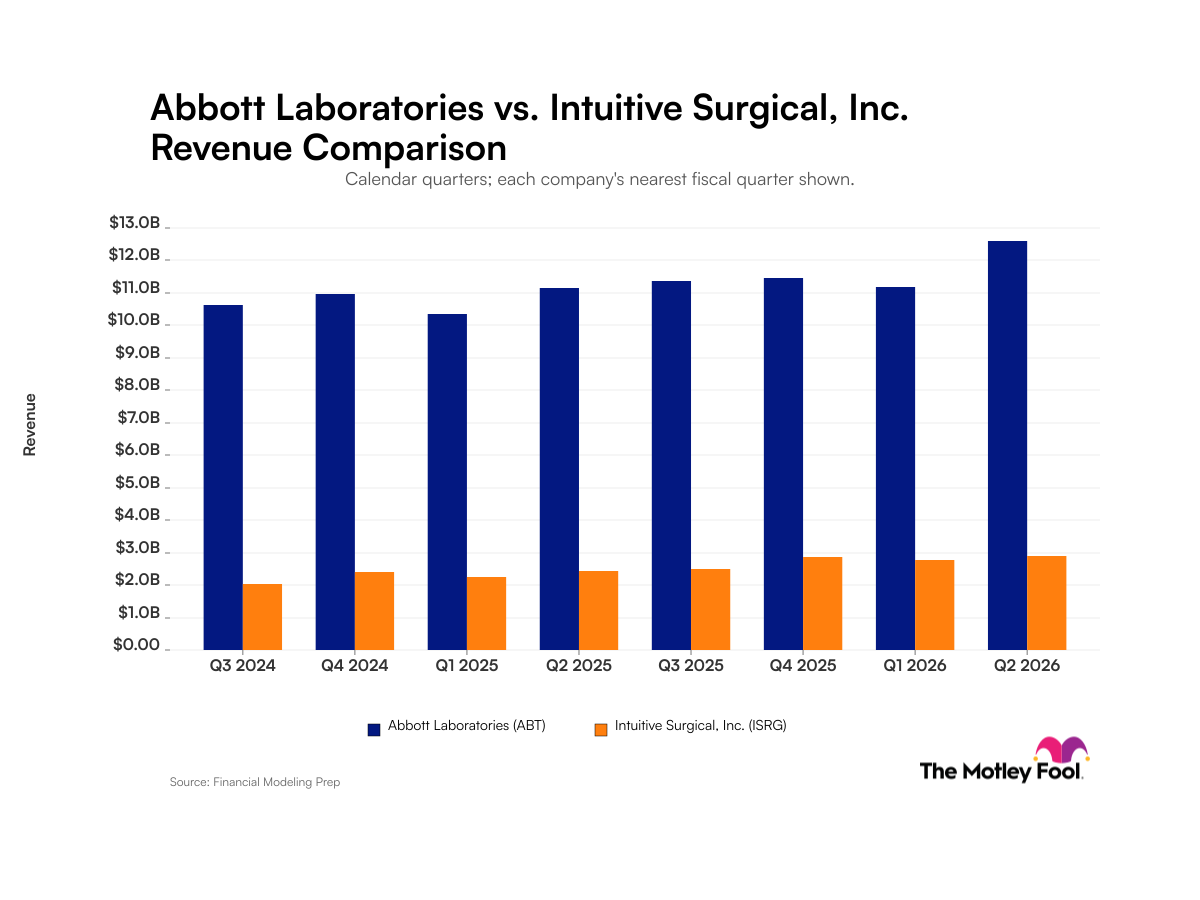
Abbott Laboratories' fourth-quarter top-line growth came up short of expectations. The company's sales were $11.5 billion, up 4.4% compared to the year-ago period. Two of the company's business segments, nutrition and diagnostics, moved in the wrong direction. And to make matters worse, the company's guidance for its fiscal 2026 was not strong either. It's not that surprising, then, that Abbott's shares fell sharply on the heels of its earnings release.
Image source: Getty Images.
Addressing the challenges
It's worth pointing out, though, that Abbott's core medical device business remains strong, delivering 12.3% sales growth in the quarter. This was, once again, driven partly by its diabetes care unit, whose revenue jumped 14.5% year over year. Abbott's structural heart unit also performed pretty well. The medical device giant has plenty of growth avenues in these niches. In diabetes care, Abbott remains a leader in the CGM (continuous glucose monitoring) market thanks to its FreeStyle Libre franchise.
In recent years, it has expanded its lineup, notably because of over-the-counter products such as the Libre Rio, designed for type 2 diabetes patients who aren't on insulin (CGM makers have historically targeted primarily diabetes patients on insulin), and the Lingo, which is for glucose monitoring for people who aren't diabetic. These launches expanded Abbott's addressable market. The CGM space remains deeply underpenetrated, as the company noted a few years ago. So, there could be plenty of growth left ahead for Abbott Laboratories.

NYSE: ABT
Key Data Points
In structural heart, devices such as the MitraClip and TriClip, leaders in their respective niches, should still drive growth for a while. Further, Abbott announced an acquisition last year that will transform its diagnostics business and provide it with another significant growth avenue. The company is buying out cancer diagnostics leader Exact Sciences for about $21 billion in cash.
Exact Sciences markets Cologuard, a leading non-invasive test for colorectal cancer, the second leading cause of cancer death in the world. It has also developed new diagnostic products, including one for the early detection of various cancers. The cancer diagnostics market is growing at a good clip. And with the backing of the larger, richer Abbott Laboratories, Exact Sciences' products could find even greater success.
A top dividend stock
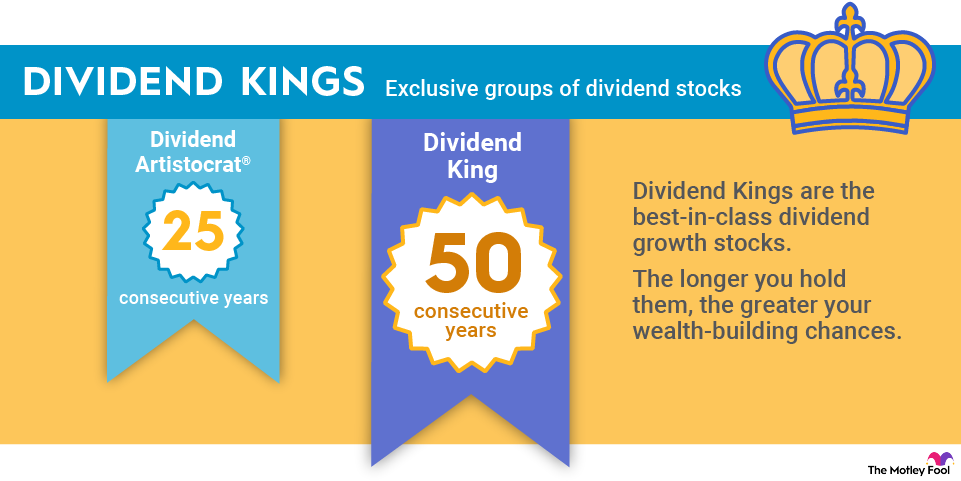
Abbott's prospects remain bright for long-term investors despite the company's recent setbacks. And then there is the healthcare giant's dividend program. The company has increased its payouts for 54 consecutive years, which makes it a Dividend King, or a corporation with a minimum of 50 straight annual dividend hikes. The stock is currently trading at about $106 apiece. Investors with only $150 who want to buy an excellent dividend stock can hardly do better.