If your business is not considered a winner from artificial intelligence (AI), then it is likely severely underperforming the market. Consider Nu Holdings (NU +4.81%). The digital banking giant is down 28% this year and 37% from its 52-week high, while the S&P 500 index is up more than 8% in 2026.
This creates a bargain-buying opportunity for Nu Holdings stock if investors plan to hold for five or more years. Here's why shares of Nu Holdings, parent of Nu Bank, look cheap right now, why management agrees, and what returns could look like for the fast-growing bank during the next five years.

NYSE: NU
Key Data Points
Global expansion plans
The core of Nu Bank's business is in Brazil today, where most adults use one of its digital banking products. With increased revenue per customer, the company should see steady growth in its domestic market in the years ahead, with significant profitability.
Where growth will come from is Mexico, Colombia, the U.S,, and potentially other Latin American nations the bank decides to enter. Mexico is its second-largest market in Latin America, with 15 million active customers and nearly $1 billion in annual revenue. Compared to more than $10 billion in revenue from Brazil, there is still a long runway for Nu Bank to expand its bank, credit card, and lending business in Mexico to build it up to the same size as Brazil, which has a similar-sized economy.
Colombia is a smaller market, but it can still drive growth in the years ahead with rapid customer adoption underway. The long-term growth may come from the U.S., where Nu Bank believes it can bring its digital banking product for lower-income customers from Latin America to serve a sub-section of the population in the world's largest economy. After this, it is likely to enter new Latin American markets such as Chile, Argentina, or Peru.
Total revenue was $16 billion during the last 12 months. If Nu Bank can successfully penetrate most of these large markets in North and South America, its revenue will grow into the tens of billions during the next five years.

Image source: Getty Images.
Profit inflection that is only growing
Earnings should grow even faster than revenue, illustrated by Nu Bank's improving efficiency ratio during the past few years. An efficiency ratio measures overhead costs versus total interest income and fee revenue. The lower the percent, the more efficiently your bank is run.
Nu Bank's efficiency ratio hit a record low of 17.6% last quarter, which is why net income has grown faster than revenue during the past few years. Total net income has increased 4,000% during the past three years to $3.2 billion, far outpacing the 216% revenue growth.
This means that if Nu Bank's revenue doubles during the next five years, its net income could more than triple to $10 billion, making it one of the most profitable banks in the world.
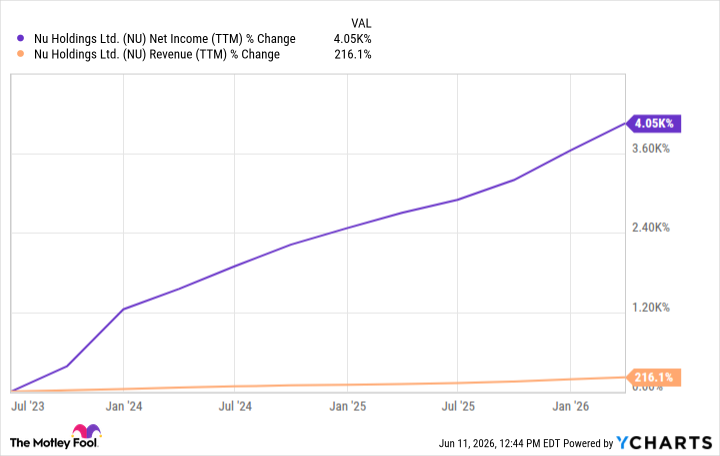
NU Net Income (TTM) data by YCharts
Returning cash to shareholders
Despite this profit inflection, Nu Bank stock has sunk in 2026. Management is going to take advantage of this dislocation through its recently announced $1 billion share repurchase program to reduce shares outstanding and increase earnings per share (EPS).
There may be volatility ahead for Nu Bank due to its ties to Latin American economies, which are historically less stable than the U.S. Of course, there are always risks when making loans to low-income individuals, which powers much of Nu Bank's interest income.
Still, over the long term, Nu Bank has proven it can build a profitable digital bank in Brazil, Mexico, and now in other countries. Net income of $3.2 billion today may grow to $10 billion five years from now if it can keep this superb efficiency ratio. Compared to a market cap of $59 billion, this looks like a low price for investors with the patience to hold for five years or more, meaning the stock should be a multibagger in the years ahead.