Some companies enjoy a far more reliable stream of revenue than others. Financial outfit S&P Global (SPGI +1.20%) is one of these companies. The bulk of its business comes from providing services that Wall Street pays for over and over again, mostly because the industry can't get them anywhere else.
Always in demand
Yes, this is the same company that maintains and licenses the S&P 500 index, plus several other indexes. That's not its biggest business, though. S&P Global's single biggest moneymaker is selling its market and equity (stock) research, or "Market Intelligence," while its second-biggest business is bond ratings.
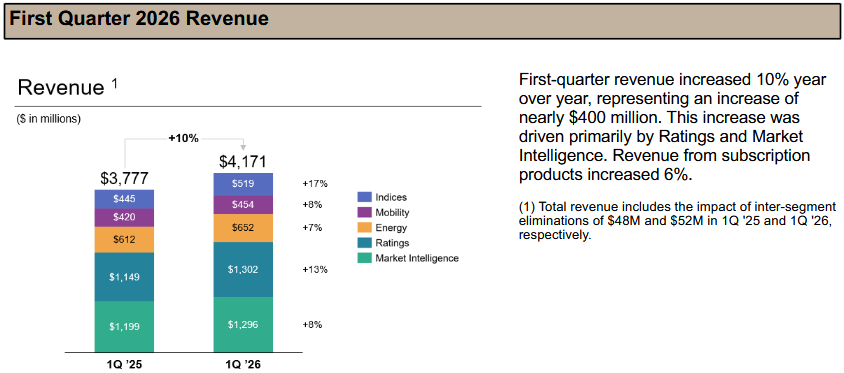
Image source: S&P Global's Q1-2026 investor slide deck.
If you have a brokerage account that offers online access to research reports on individual stocks, you've likely reviewed a report from S&P Global, although you may know it better as Standard & Poor's. And if you've ever checked out a quality rating on a corporate bond or other fixed-income instrument, there's a good chance S&P Global produced it.
Here's the thing: About half of its business is subscription-based, and this business isn't apt to dry up anytime soon, if ever. Investors and institutions always need what it offers, either for themselves or on behalf of their clients. The market doesn't want this research and information from lesser-known or less established suppliers as much as they want it from Standard & Poor's.
Image source: Getty Images.
It's an ideal scenario for a dividend-paying stock. Reliable cash flow means reliable dividend payments. To this end, S&P Global has not only paid a dividend like clockwork for decades now, but it has raised its per-share dividend payment every year for over 50 years.
Changes for the better
Interested investors need to know significant change is coming. Namely, the mobility division that accounted for about 10% of the company's revenue has now been spun off into its own stand-alone business, now trading separately as Mobility Global (MBGL +2.21%). This means this business's numbers will no longer be reported with S&P Global's results, beginning with the quarter ending in September.
S&P Global has also recently divested the geoscience and petroleum engineering software portfolio that was part of its energy division, although this profit center wasn't a particularly big one. In the meantime, its energy arm has launched some new analytics tools powered by artificial intelligence.
None of this restructuring changes the fact that S&P Global is a tollbooth set up right in the middle of Wall Street. It does, however, make the company a slightly more compelling investment prospect, since Mobility's profit margins are slightly below the companywide average.

NYSE: SPGI
Key Data Points
Then there's this: The vast majority of analysts covering this ticker currently rate it as a strong buy, with a consensus target of $501.24, 15% above the stock's present price. That's not a bad way to start out a new position, even if you're also starting out with a relatively weak forward-looking dividend yield of right around 1%. Again, dividend growth has been quite reliable here.