Joby Aviation (JOBY -5.51%) has spent the better part of its life trying to make electric vertical takeoff and landing (eVTOL) aircraft into a real, sustainable business. Now, oddly enough, one of its biggest developments of the year has almost nothing to do with eVTOLs -- at least, not yet.
On Aug. 11, Joby announced that it will acquire defense technology company Resonant Sciences for about $500 million, including about $450 million in cash and $50 million in Joby stock. Resonant, which generated more than $100 million in trailing-12-month revenue, will eventually become Joby’s dedicated defense business. That means the Joby team can continue working on its air taxi service, while the Resonant team works on defense technology, with plenty of potential for cross-pollination between the two sides.
The deal makes Joby a much stronger, more diversified business. But whether it makes Joby a stronger stock is a more complicated question. Let’s take a closer look.

NYSE: JOBY
Key Data Points
Resonant makes Joby a stronger business, but not a safer stock.
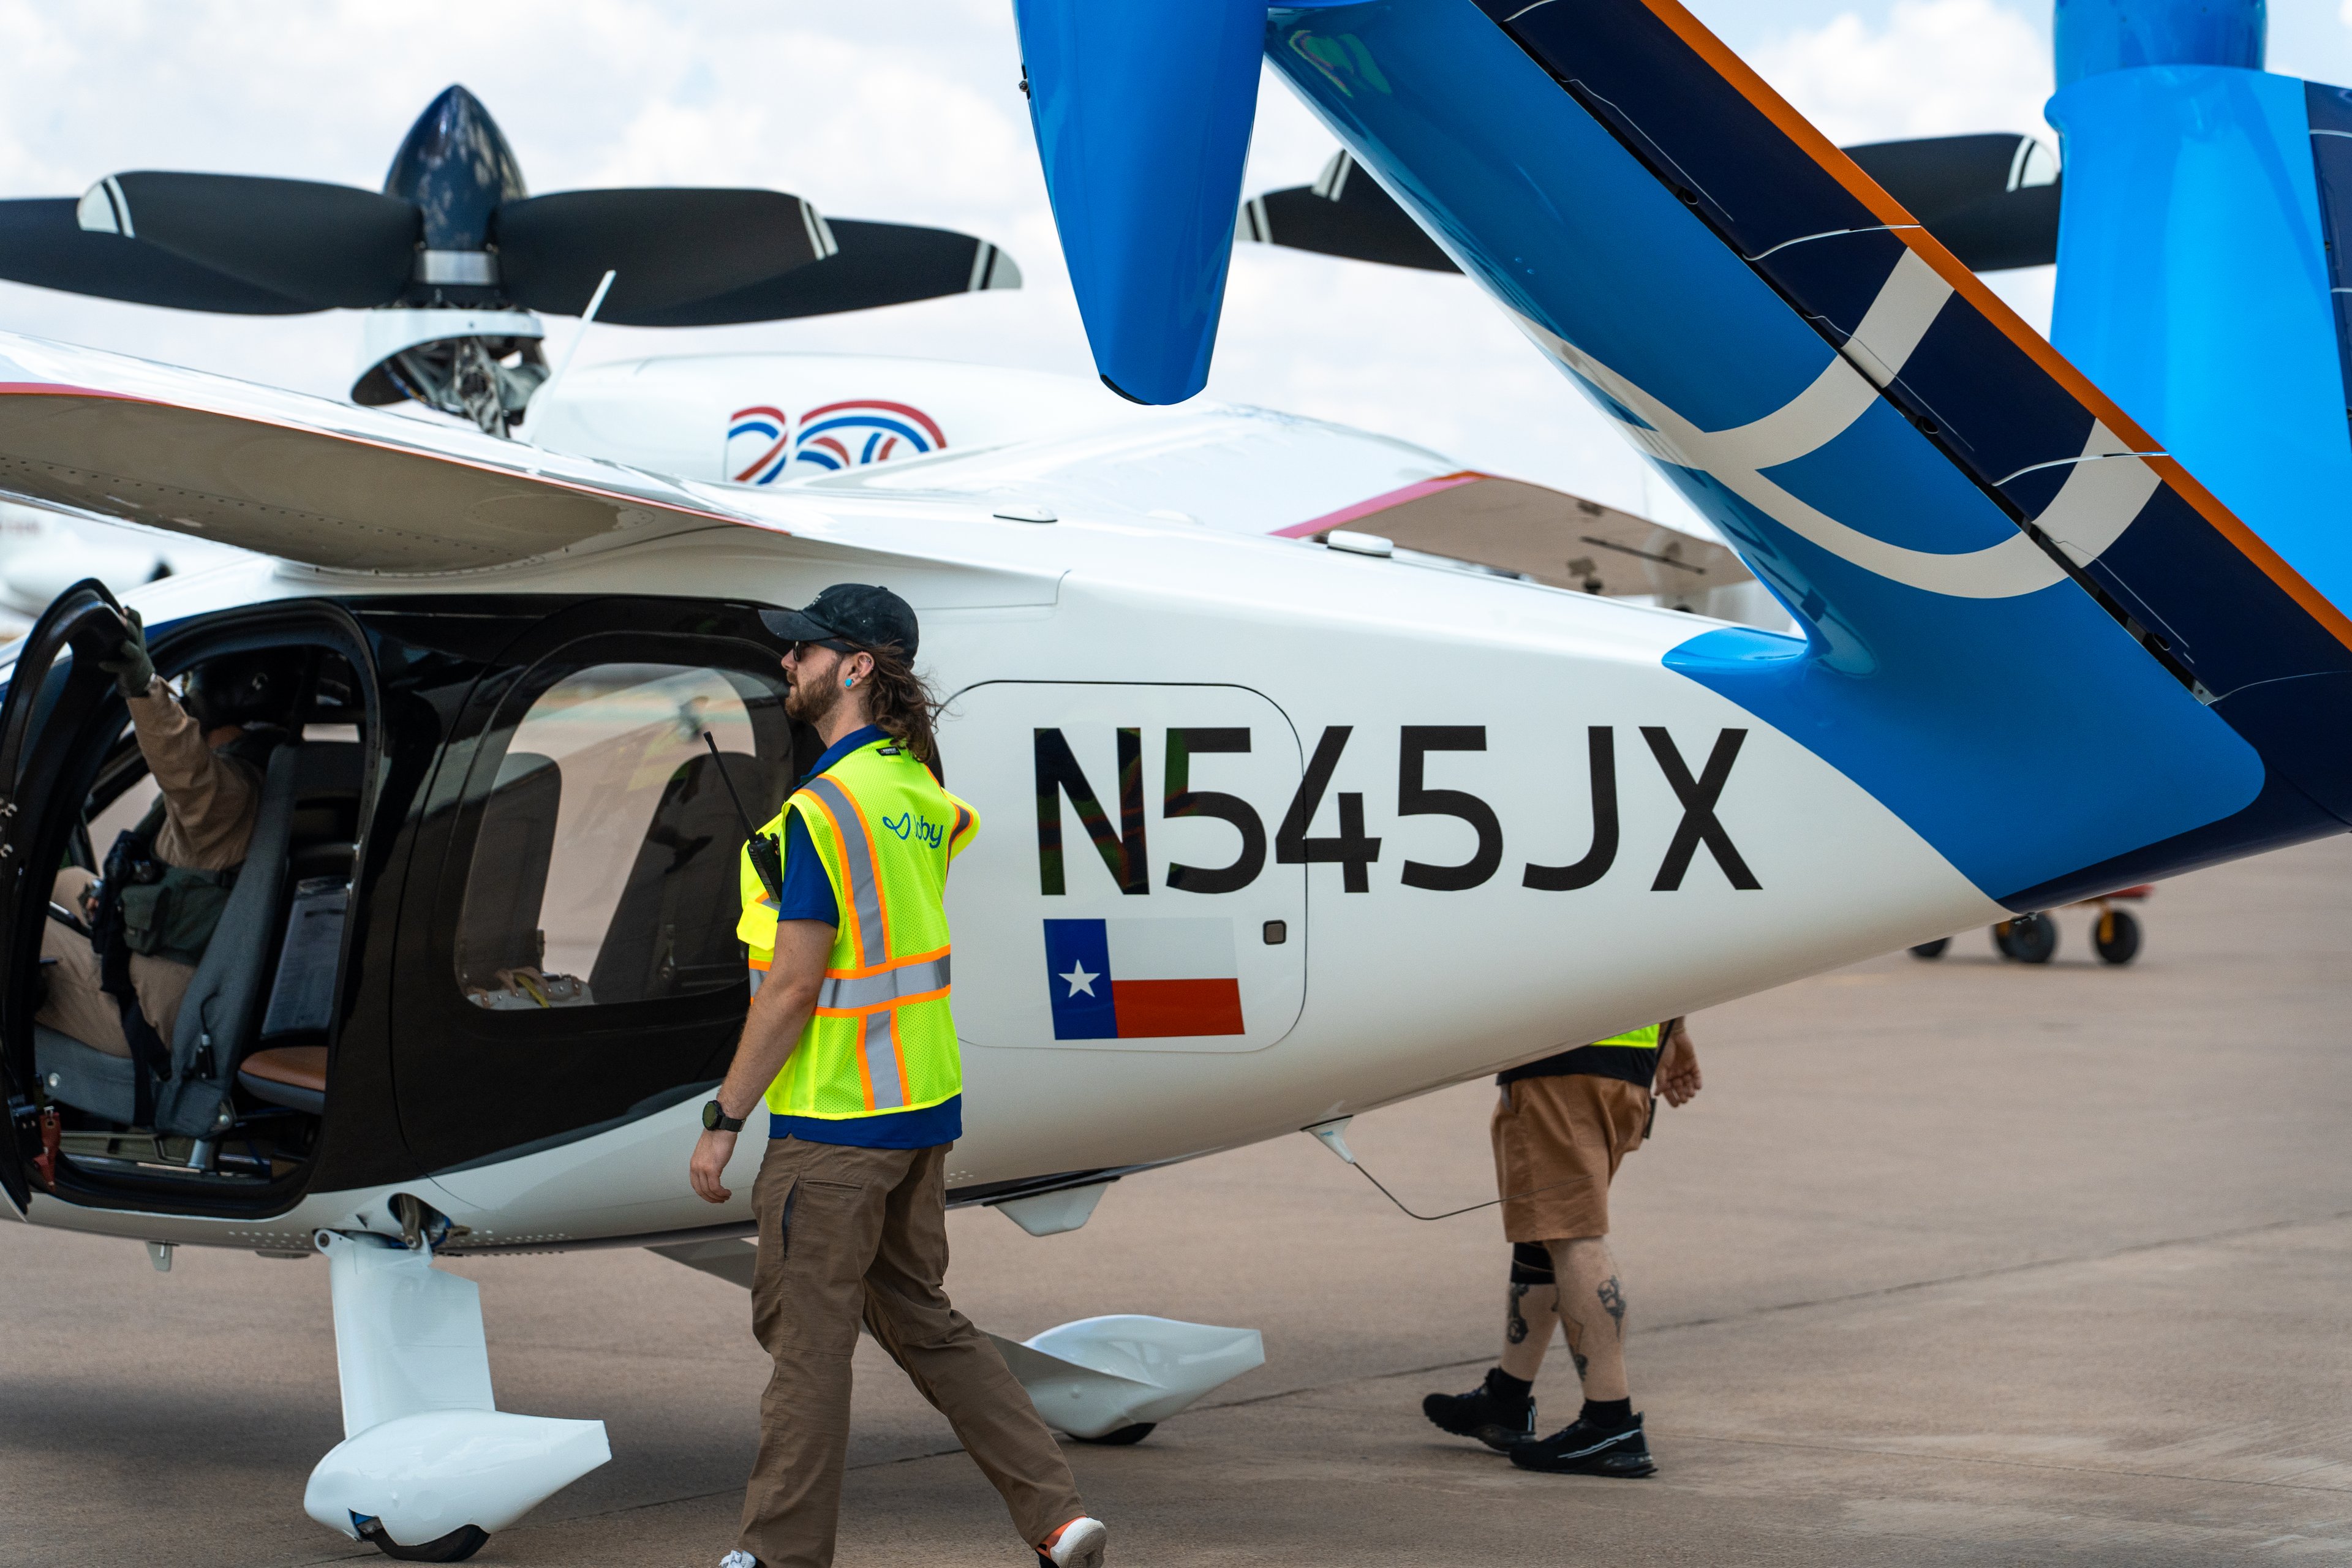
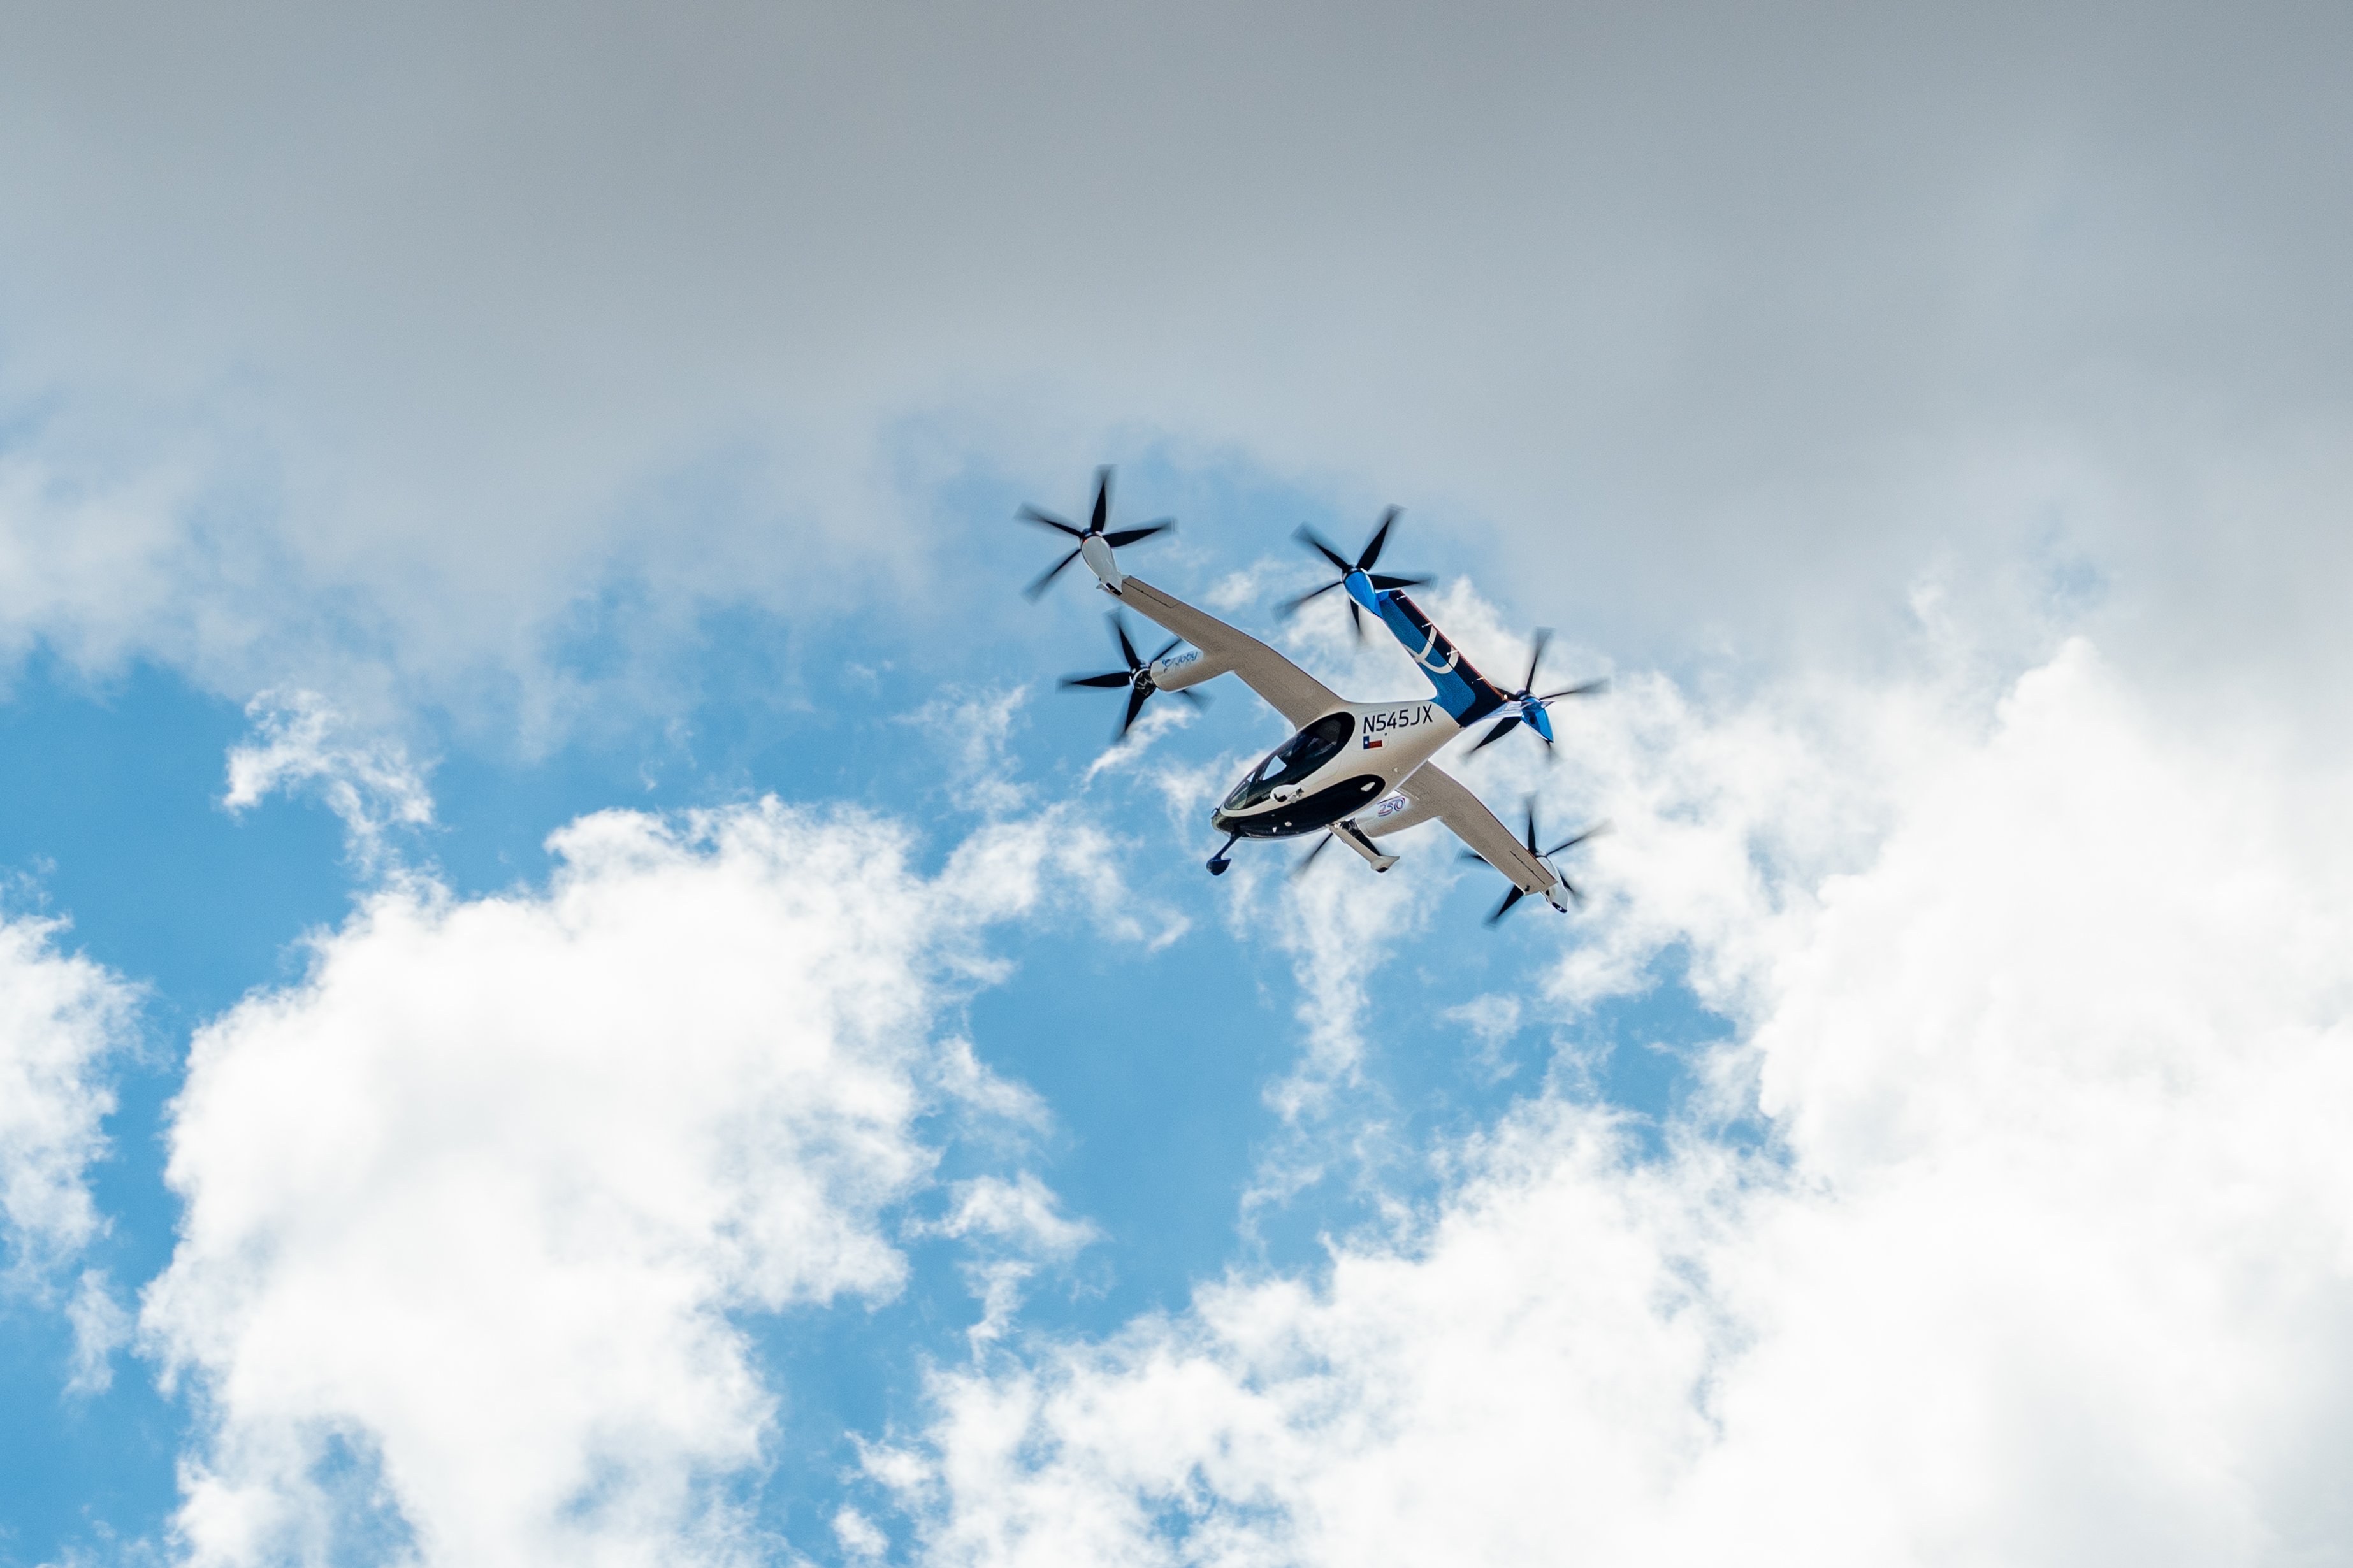
Joby Aviation, as I alluded to above, has been trying to build an electric air taxi company. It is indeed widely considered the frontrunner in the nascent eVTOL industry, due in large part to its lead in flight testing and its progress through the FAA’s type certification process.
Joby used about $318 million in operating cash over the first six months of 2026, while reporting about $63 million over the same period. Much of that revenue comes from Blade Air Mobility, which it acquired in 2025. The company still had a hefty liquidity cushion, about $2.3 billion at the end of June, but it badly needs its revenue base to grow if it wants to avoid further shareholder dilution down the road.

Image source: The Motley Fool.
In this context, the acquisition of Resonant is an A-. It’s an “A,” because it gives Joby a revenue stream tied to a fast-growing business. Resonant has grown its trailing-12-month revenue by roughly 40% year over year, generates positive adjusted EBITDA, and has an established customer base that includes the U.S. government.
It’s an “A-,” and not an “A+,” however, because it’s dedicating a sizable chunk of its liquidity to the acquisition. Paying $450 million in cash would reduce Joby’s total liquidity to about $1.85 billion, all else equal. Still sizable, but it shaves about eight to nine months from Joby’s cash runway, assuming, of course, its recent burn rate stays consistent.
It’s not, however, a bad deal. In fact, I would call it a smart move. Historically, military demand has often subsidized (and accelerated) aviation technologies that later have civilian applications, and Resonant’s defense business could fit into that pattern. Indeed, Morgan Stanley’s (MS +0.00%) eVTOL report, which predicted the global urban air mobility to $9 trillion by 2050, once named “national security” as one of the five main accelerants for urban air.
Does this make Joby a screaming buy?
I don’t think the acquisition makes Joby a screaming buy. Joby, which carries a roughly $8 billion market cap, is still being valued primarily on its commercial air taxi services, which, mind you, haven't yet received FAA type certification. Although the expansion into defense adds revenue Joby didn’t have yesterday, it also adds another layer of risk to the whole enterprise, if only because eight to nine months of cash cushion will go toward it.
After the acquisition, I like Joby stock a little more, but my position hasn’t fundamentally changed: the stock is still, I think, a high-risk, high-reward play on an industry that doesn’t yet exist. Aggressive investors might be interested, but I’d keep my position small until that FAA type certification for its eVTOL is in hand.