Micron Technology and Sandisk have been among the most popular memory stocks on the market, and that's not surprising considering the impressive pace of growth in their revenue and earnings.
The market has duly rewarded their shares for their terrific growth. While Micron stock has surged 242% in 2026, as of this writing, Sandisk has clocked even bigger gains of 588%. However, there is another memory stock that has soared impressively in 2026. Shares of SK Hynix (SKHY +0.94%) have jumped 178% this year on South Korea's KOSPI Composite Index.
The company made its debut on the U.S. stock market a couple of months ago, and it has clocked respectable gains of 27%. The good news for investors is that they can still consider buying SK Hynix, given the potential upside it is likely to deliver over the next three years.
Image source: Getty Images.
SK Hynix's incredible growth is sustainable
SK Hynix reported its second-quarter earnings in July. The company's revenue surged 257% year over year to $54.5 billion. Its operating profit increased by an even more handsome 557% from the year-ago period.

NASDAQ: SKHY
Key Data Points
SK Hynix management noted that the increasing demand for memory from AI data centers played an instrumental role in its phenomenal growth. Importantly, the company expects memory demand to improve in the future due to the proliferation of AI. As a result, it is now witnessing an increase in supply requests from customers.
What's more, SK Hynix is entering into multi-year contracts with customers to supply memory chips. It has 10 such long-term agreements (LTAs) already in place and notes that it is in discussions to enter into more LTAs. Moreover, customers are looking to expand the scope of the existing LTAs.
SK Hynix will therefore continue to benefit from a robust demand environment over the next three years. At the same time, there isn't enough supply available to satisfy the booming memory chip demand. The company estimates that memory wafer demand will exceed supply by 20% through 2030. That's almost in line with equity research provider Citrini Research's estimate of a 25% shortfall in DRAM supply by 2030.
So, SK Hynix's strong earnings power should remain intact over the next three years, paving the way for significant upside in the stock price.
Gauging the stock's upside potential
SK Hynix is expected to deliver solid 20%-plus earnings-per-share growth in 2027 and 2028.
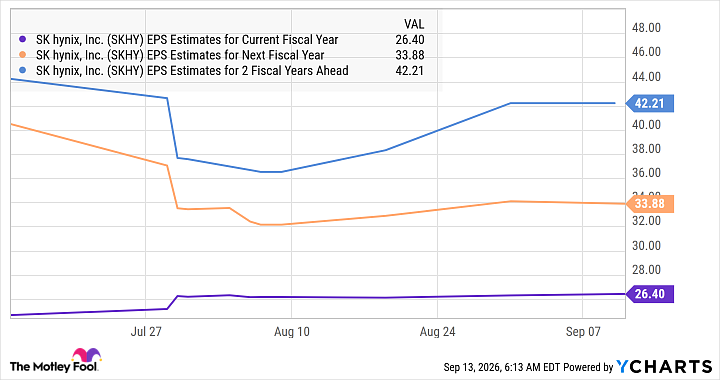
Data by YCharts
However, we have seen that the company's earnings are growing at a significantly faster pace. The strong memory demand and the accompanying supply shortage should help SK Hynix clock stronger earnings growth over the next three years. In fact, analysts expect the company to deliver stronger annual earnings-per-share growth of 86% over the long run, according to YCharts.
However, even if SK Hynix clocks $42.21 in earnings per share in 2028 and trades at even 15 times earnings at that time, a discount to the S&P 500's forward earnings multiple of 21, its stock price could hit $633. That's 233% higher than its current stock price, making this semiconductor stock a no-brainer buy given that it trades at just 12 times earnings.