Micron (MU +5.50%) and Sandisk (SNDK +6.21%) have been two of the best-performing stocks in the S&P 500 (^GSPC +1.14%) so far this year. Sandisk is leading the way with an incredible 550% gain. Micron is in fourth place, up by over 220%. That means both of these stocks have tripled (or more than tripled in Sandisk's case), but I think that's just the beginning. In fact, if you invested $2,500 in each of these stocks, for a total of $5,000, I think that the combined value of those stakes will rise to $15,000 by the time 2028 arrives.
While that may sound far-fetched, the math backs it up, suggesting that these are two of the best investments you could make in the stock market right now.
Image source: Getty Images.
Memory chip demand isn't slowing down anytime soon
The reason these two have done so well in 2026 is that there is no spare memory chip production capacity left. Micron and Sandisk are two of just three big players in this industry, and all of their production is being eaten up by massive demand for additional artificial intelligence computing power. AI processors and servers need heavy volumes of memory to function efficiently, and as a result, there's now a serious shortage of memory, so prices are skyrocketing.
This supply-and-demand imbalance is the culprit behind rising prices for consumer computing hardware, as these devices all require memory chips, too.

NASDAQ: MU
Key Data Points
In this scenario, there's really only one winner: memory chip suppliers. That makes Micron and Sandisk beneficiaries of one of the greatest supply crunches we've ever seen, and they're making a fortune off of it based on simple economic supply-and-demand laws. The price of memory chips will continue to rise until one of three things happens.
First, demand could drop or rising production could catch up to it. I don't see this happening, as there's a heated race among AI firms to build out more data center infrastructure. Meanwhile, memory chip foundries take a few years to build and bring online, and industry experts don't expect new supply to start tilting the market back into balance before 2028 at the earliest.
Second, prices could rise so much that demand at those prices starts to fall. This is the most likely outcome, but it's uncertain what price level could trigger a drop-off in buying.
The last scenario is that the government institutes a price cap on memory to protect consumers. This is the least likely scenario, as data center build-outs are causing this shortage, and data centers aren't the most highly viewed item in society right now.

NASDAQ: SNDK
Key Data Points
So, with the most likely outcome being memory prices continuing to rise until most of the big buyers become unwilling to pay what the manufacturers are asking, Micron and Sandisk are in great shape.
With AI demand still rising, this could lead to incredible years for these two, making them smart buys now.
2027 will be just as strong
Both Micron and Sandisk have entered into their fiscal 2027s -- Micron's started in September and Sandisk's started in July. For this fiscal year, Wall Street analysts once again expect incredible growth from them. For Micron, analysts expect 88% revenue growth. Analysts are a bit more bullish on Sandisk, as they expect 142% revenue growth.
Those are simply incredible growth figures, given the banner years they had in fiscal 2026. However, the stocks are not trading at high valuations.
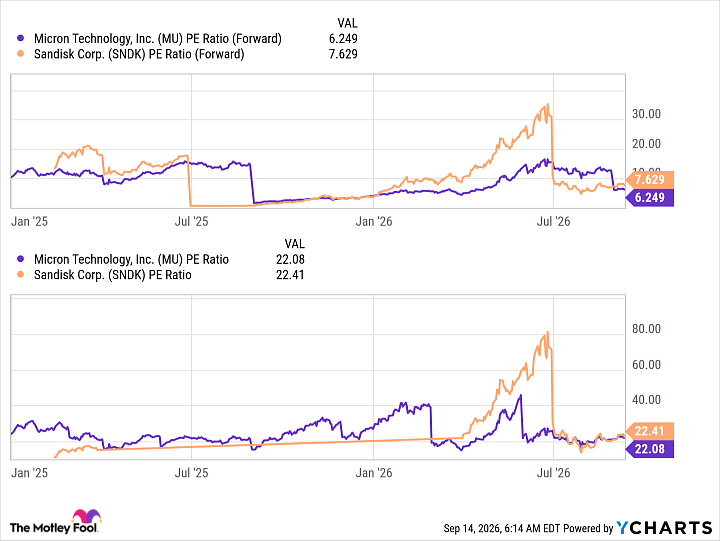
In fact, both Micron and Sandisk trade at price-to-earnings ratios that are far cheaper than their historical levels.
MU PE Ratio (Forward) data by YCharts.
Both companies trade for about 22 times trailing earnings. From a forward earnings perspective, they're trading between 6 and 8 times earnings. If these two hit analysts' consensus projections for earnings, in order for them to continue to trade at 22 times trailing earnings as of the end of their fiscal 2027s, their stock prices would have to triple.
That's not a hard scenario to envision, and analysts have consistently underestimated the growth these two would put up in 2026, so I think they may be being overly conservative about their 2027 forecasts, too. As a result, I think a triple is probably the baseline outlook for Micron and Sandisk over the next year, making them great stocks to consider loading up on now.