Boeing (BA +0.61%) stock presents a rare value in the aerospace sector right now. Commercial aerospace-focused stocks tend to command premium valuations because the market prices in a long-term stream of income coming from a combination of lucrative aftermarket services and the surety of massive commercial aircraft backlogs at Boeing and Airbus.
However, the valuation discount makes it appear attractive to value-oriented investors. Here's why.
Boeing's valuation discount
The table shows price-to-free cash flow (FCF) valuations based on the Wall Street consensus from Visible Alpha.
|
Price to Free Cash Flow |
2025 |
2026 |
2027 |
2028 |
2029 |
2030 |
|---|---|---|---|---|---|---|
|
The Boeing Company |
NM |
66.6x |
27.3x |
17.1x |
13.8x |
11.6x |
|
GE Aerospace |
42.8x |
35.3x |
31.3x |
28.3x |
25.9x |
23.1x |
|
Howmet Aerospace |
58.2x |
46.6x |
38.6x |
32.5x |
28.6x |
26.5x |
|
Hexcel |
37.6x |
33.4x |
25.7x |
21.6x |
18.2x |
16.8x |
|
RTX |
31.3x |
30.6x |
26.1x |
23.0x |
20.5x |
18.7x |
Data source: Visible Alpha. Chart by author.
The clear discount beyond 2028 then leads to an almost philosophical question: If Boeing and Airbus aircraft are the starting point of the commercial aerospace industry and Boeing's current backlog of more than 6,200 airplanes (worth $597 billion) is a large part of the rationale for buying aerospace stocks, why does Boeing deserve such a valuation discount?
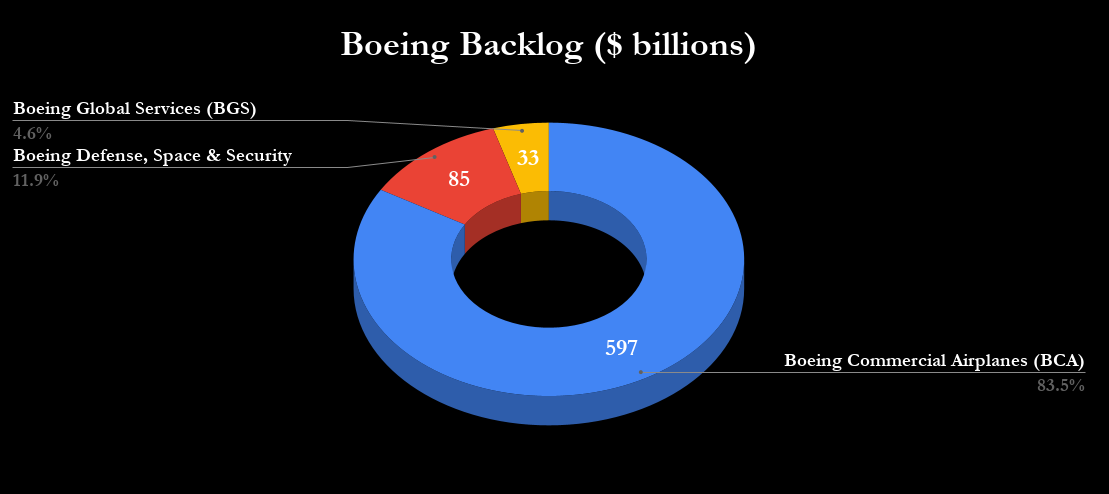
Data source: Boeing presentations. Chart by author.
The answer lies in the much-maligned, high-profile 737 MAX quality issues and groundings, as well as delays in commercial aircraft certifications and massive losses on fixed-price development programs in its defense arm, Boeing Defense, Space & Security (BDS). Simply put, Boeing needs to convince investors that its worst days are behind it and that it can execute to meet the numbers implied by the valuations above for 2028 and beyond.
CEO Kelly Ortberg is turning the company around
The good news is there are signs of progress.
First, having started 2025 with 737 MAX production in the low 30s per month, CEO Kelly Ortberg said in July that Boeing is "now ramping to 47 airplanes per month" and that a production line in Everett, Washington, will be opened to reach 52 per month in the future.
Ortberg recently spoke at a Morgan Stanley conference, saying, "We are not stable yet at 47 a month," which is a little disappointing. On a more positive note, he confirmed that the new production line in Everett is now open. Moreover, Ortberg believes certification on the 737 MAX 10 (an aircraft likely to compete with the hugely successful Airbus A321) is coming very soon.
Image source: Getty Images.
Second, the acquisition of Spirit AeroSystems in December 2025 has derisked its supply chain for fuselages and other components for the 737 MAX, 777, and 787 Dreamliner.
Third, the issues at BDS primarily relate to a few problematic fixed-price development programs (KC-46 Tanker and Air Force One among them), which the company is working through (the rest of the business is profitable). The company is on track to return to profitability at BDS in 2026.
Finally, Boeing's sale of its electric vertical takeoff and landing (eVTOL) business, Wisk, to Archer Aviation helps to focus Boeing on its core business.
A stock to buy?
When you put these things together, it's clear that Ortberg is making progress at Boeing, and the enduring opportunity to execute on its massive backlog underpins the stock's valuation case.