Micron (MU +5.00%) has been a great investment so far in 2026. It's up around 265% this year, but still down about 15% from its all-time high established at the end of June. However, I could see that changing in short order.
Micron reports earnings on Sept. 30, and that date is quickly approaching. The last few times Micron has reported earnings, it has blown expectations out of the water. I'd expect the same from the company this quarter, and that could be the catalyst it needs to send shares skyrocketing to new highs.
Image source: The Motley Fool.
Micron is thriving in today's market conditions
Micron makes memory chips, which are in very short supply right now. The two primary types of memory are DRAM and NAND, and each has its own set of use cases. Regardless of which type of memory you're referring to, it's in short supply due to massive demand from the AI sector. The memory chip market as a whole was not ready for the demand shock that AI has created, and there is a huge shortage of production capacity across the industry.
Simple economic laws dictate that when supply is short and demand is high, prices rise. That's exactly what has happened recently, and Micron and its peers are thriving because of it.
Because there isn't a ton that separates one memory chip product from another, it's practically a commodity. This makes the industry cyclical as well, and that may be the biggest holdup many investors have.
However, with how long this demand curve is expected to last, Micron's cyclical nature may not be as big a concern. Nvidia has repeatedly projected that AI spending will reach $3 trillion to $4 trillion annually by 2030, which is still a major step up from today. For 2027, Nvidia expects the big five AI hyperscalers to spend about $1.3 trillion. Even though that figure doesn't include other AI players, it's still a long way from its 2030 projection.

NASDAQ: MU
Key Data Points
The industry is going to need a lot more memory chips than are available to meet this goal, so Micron and its peers are in a great position for a long-term demand wave. However, the supply crunch won't last forever. Micron estimates that the tightness in the memory chip market will persist beyond 2027, mainly due to the timing of its new production facility openings, which are expected to start production in mid-2027 and 2028.
That will increase the supply, which will get the memory chip market out of a supply-constrained state. However, it could reduce chip prices due to increased supply. This isn't a bad thing per se, as there will still be a very elevated demand curve that will keep Micron extremely profitable during this time frame.
However, that's in the future. Why will Micron skyrocket in a few days?
Micron is dirt cheap
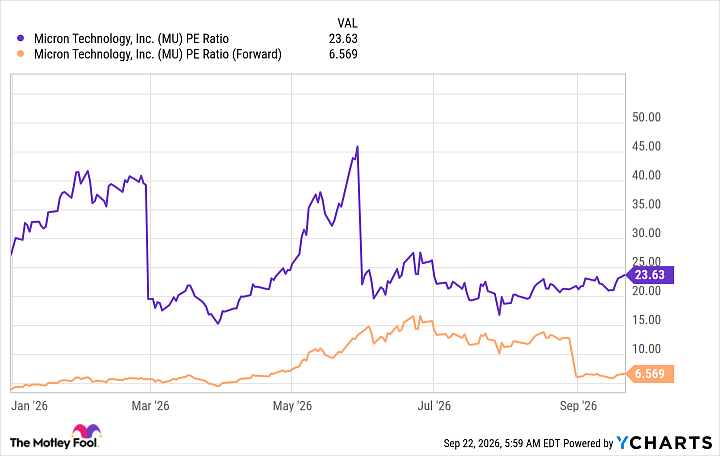
As mentioned above, Micron is a historically cyclical company. As a result, the market doesn't fully respect the company's long-term earnings potential. That's why the stock trades at a dirt cheap price tag of 6.6 times forward earnings.
MU PE Ratio data by YCharts
The market is concerned that this demand won't last, which is why there's a huge mismatch between its trailing earnings valuation of 24 times earnings and its forward earnings valuation. If Micron assures the market that it will be a long time before this cycle is over, it may convince some investors that Micron is here to stay and can produce incredible results over the next few years. That could drive more buyers to the stock, leading to a soaring stock price.
I think that revelation could be coming in just a few days, which makes Micron an excellent stock to buy before its earnings on Sept. 30.