The stock of intelligent power and sensing chip company ON Semiconductor (ON +0.68%) has had a wild ride in 2026. It delivered an exceptional performance, driven by a combination of soaring demand from its fast-growing artificial intelligence (AI) data center market and a cyclical recovery in its core automotive and industrial end markets.
However, the announcement of an agreement to acquire AI edge solutions company Synaptics (SYNA +0.47%) led to a crash in the share price, and the recent investor day presentation didn't reverse it. What's going on and why isn't the market warming to the company's strategic shift?
ON Semiconductor's investor day
A slew of Wall Street analysts lowered their price targets for the stock after the investor day presentation, in which management outlined plans to target a market valued at $213 billion. However, as ever, it's hard to discern if the cuts were in response to the presentation or a lowering of price targets now that the market has corrected the stock so sharply.

NASDAQ: ON
Key Data Points
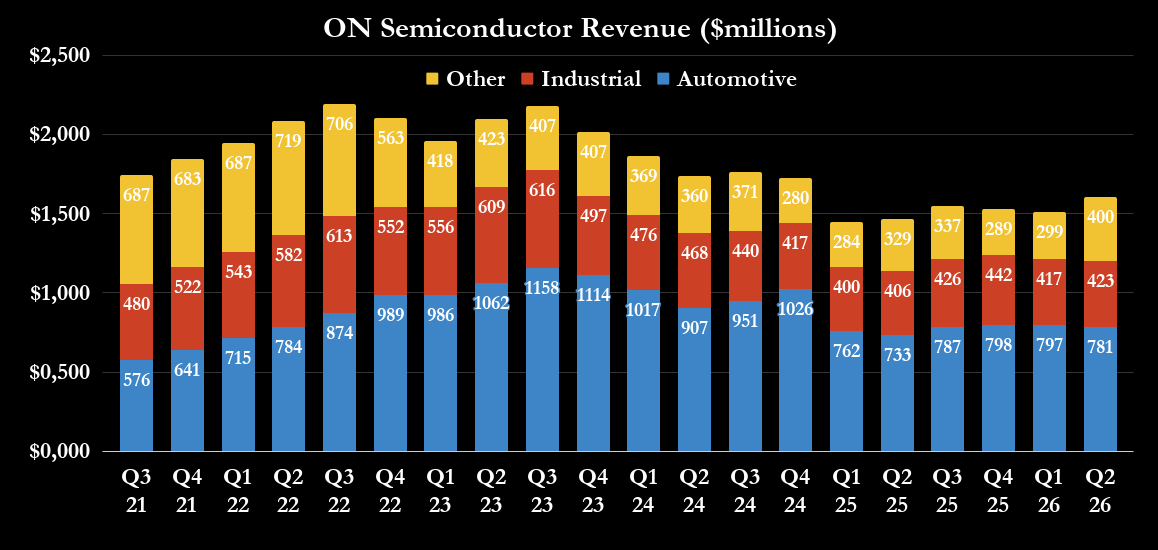
Whatever the case, the market appears to still be treating ON Semiconductor in terms of where it's come from rather than where it's going. In other words, a chip company is exposed to highly cyclical end markets. The sharp rise in the price earlier in the year reflects the cyclical recovery in its end markets, as well as strong growth in its AI data center end market (reported under "other") from which management expects $500 million in revenue this year, with expectations for $1 billion in 2027 and $2.5 billion in 2030.
However, the crash in the share price since the Synaptics announcement indicates the market is not happy with the company's strategic shift from being a component supplier to an integrated technology platform provider.
Image source: Getty Images.
Management aims to capture more value from its end markets by providing power system architectures that are a naturally evolving necessity for physical AI solutions requiring ever-greater power density. These power architectures will, in the words of CEO Hassane El-Khoury during the investor day, link "to a connected compute platform that is at the center," which is where Synaptics solutions will come in and help expand its addressable market from $213 billion to $243 billion.
Clearly, the market is ignoring the strategic shift, or rather, doesn't believe in it.
Data source: ON Semiconductor. Chart by the author.
What management said on investor day
That argument is supported when you look at what management guided toward in the investor day presentation regarding revenue growth (see the table below). Moreover, management forecasts its gross margin will expand from 40.3% in 2026 to 53% in 2030, with gross profit growing at a compound annual growth rate (CAGR) of 22% and operating income at a 30% CAGR over the period.
To apply these metrics to valuations, management expects to generate $3.5 billion in free cash flow (FCF) in 2030. Very conservatively, the business at 20 times FCF would imply a stock price of $179, up from $70 now, with a potential annual return of 26%. And none of these metrics include any assumptions from Synaptics, since the acquisition hasn't been completed yet.
|
ON Semiconductor End Market |
2026 to 2030 Compound Annual Revenue Growth Rate |
|---|---|
|
Automotive |
9% |
|
Industrial |
10% |
|
AI Data Center |
50% |
|
Other |
1% |
|
Total |
12%-14% |
Data source: ON Semiconductor presentations.
What it means to investors
Management's core argument that the increasing need for power density is creating a significant opportunity for ON Semiconductor to capture more value by offering an integrated power architecture is sound. That applies whether it's data centers needing more power for AI racks, EVs needing higher power density for ultra-fast charging, or a range of physical AI products, such as humanoid robots.
However, the market appears worried, either about the company's ability to execute or the traditional cyclicality of its end markets over the near term. The latter is a definite consideration, as seen in the volatility of sales in the first chart. Still, it's incredibly difficult to predict these trends, and the underlying growth driver -- the secular increase in the demand for power density -- is strong.
On that basis, ON Semiconductor remains a highly attractive stock for AI-focused investors with a long-term view.