Micron Technology (MU -1.43%) has more than tripled this year, and the stock's stunning rally is quite deserving when we consider its incredible pace of growth.
Micron stock has soared amid the booming demand for memory chips and the accompanying supply shortage. The good news is that analysts still believe that there is more upside in store for this memory specialist.
Micron's 12-month median price target of $1,600 suggests a 46% jump from current levels. What's more, almost all the analysts covering Micron rate it as a buy. However, I believe Micron could do much better and soar beyond Wall Street's expectations over the next couple of years.
Let's look at the reasons why this high-flying semiconductor stock could double, at least, within the next two years.
Image source: Micron Technology.
Micron's primary catalyst isn't going anywhere
Artificial intelligence (AI) data centers have created a severe shortage of memory chips. This is the reason why Micron has experienced a massive surge in its revenue, margins, and earnings.

NASDAQ: MU
Key Data Points
The company will release its fiscal 2026 Q4 results on Sept. 30, and analysts are expecting a 247% surge in its revenue for the year to $129.9 billion. What's more, Micron's earnings per share are projected to have increased by 787% in fiscal 2026 to $73.52.
Market research firm TrendForce estimates that the memory market's revenue is on track to increase nearly 4x in 2026 to $889 billion. The firm notes that 2028 will be another solid year for the memory industry, with revenue anticipated to increase by 44% to $1.28 trillion. So, Micron's healthy growth is on track to continue for the next year and a half.
Also, the company should continue benefiting from strong memory demand and tight supply in 2028. Counterpoint Research estimates that the memory shortage will persist at least until 2028, while Citi expects the bottleneck to continue until 2031.
Both firms point out that the rising demand for high-bandwidth memory (HBM), used in AI accelerator chips to move enormous amounts of data rapidly, will ensure the shortage persists. HBM consumes 3x the wafer capacity of conventional DRAM. As HBM demand is projected to increase 7x by 2030, according to Bank of America, Micron should continue witnessing a strong demand and pricing environment over the next couple of years.
Here's why the stock could easily double
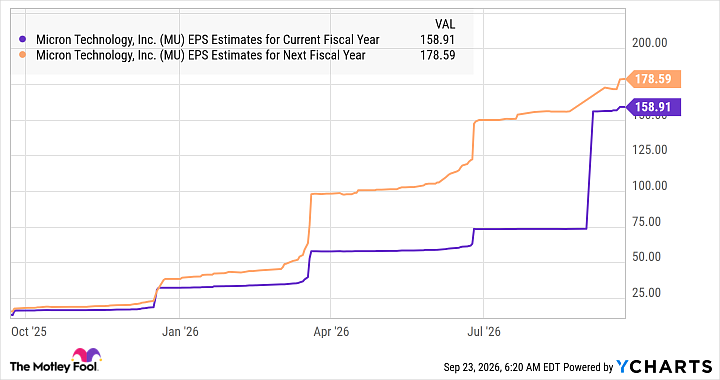
Micron's earnings per share (EPS) will continue climbing higher for the next couple of years.
Data by YCharts
The chart above indicates that its EPS will double in fiscal 2027, followed by a 12% increase in fiscal 2028. However, the company could outpace expectations due to favorable conditions in the memory market. But even if Micron's earnings growth rate slows down in fiscal 2028 and it reports EPS of $178.59, the stock could jump to $3,572 (assuming it trades at 20 times earnings at that time, in line with the S&P 500 index's forward earnings multiple).
That's almost 3.2x of where Micron stock is right now. So, Micron can make investors significantly richer over the next couple of years, which is why it would be a good idea to buy it while it trades at an attractive 6.7 times forward earnings.