Nvidia (NVDA +0.22%) has been one of the market's most popular stocks over the past few years. With a market capitalization of over $5.45 trillion, it's the world's most valuable public company, aided by its 21% gains so far this year (as of Sept. 23).
Despite Nvidia's impressive returns this year, it doesn't compare to Taiwan Semiconductor Manufacturing (TSM -0.12%) (TSMC), which is up over 46%. The semiconductor giant has a lucrative relationship with Nvidia, and right now, its business is capitalizing more than ever.

NYSE: TSM
Key Data Points
TSMC is critical to the tech ecosystem
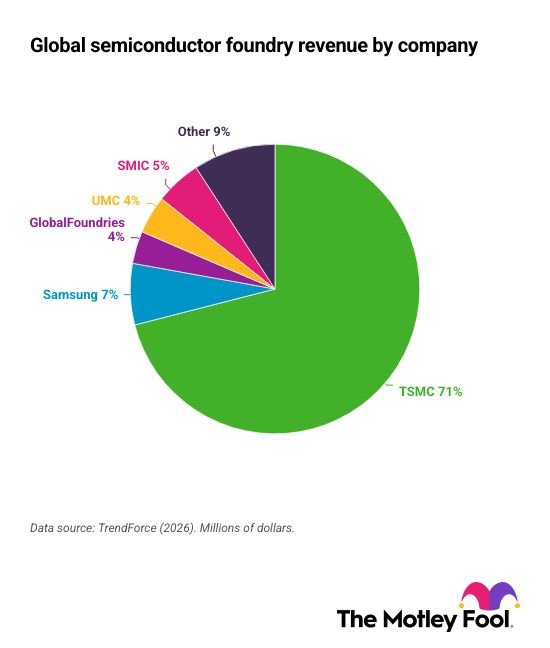
TSMC is the world's largest semiconductor foundry. Its foundry business model means that instead of making chips for general sale, it makes chips for companies' specific products.
For example, Nvidia's GPUs have become critical to the current AI boom (which is largely why the company has become so valuable); however, Nvidia doesn't actually make them. It designs them, and TSMC manufactures and brings them to life.
Manufacturing chips is hard and expensive, and it requires a lot of expertise. That's why companies instead rely on TSMC -- which has been doing it since 1987. TSMC is the go-to manufacturer for Nvidia, Apple, Microsoft, Alphabet, Amazon, and almost every major tech company.
Image source: The Motley Fool.
High demand comes with high pricing power
TSMC's business has thrived for a while, but the current AI arms race has done wonders for it. As companies spend billions to build data centers and other AI infrastructure, demand for TSMC's manufacturing capabilities has grown. This has given TSMC unmatched pricing power and sent profits soaring.
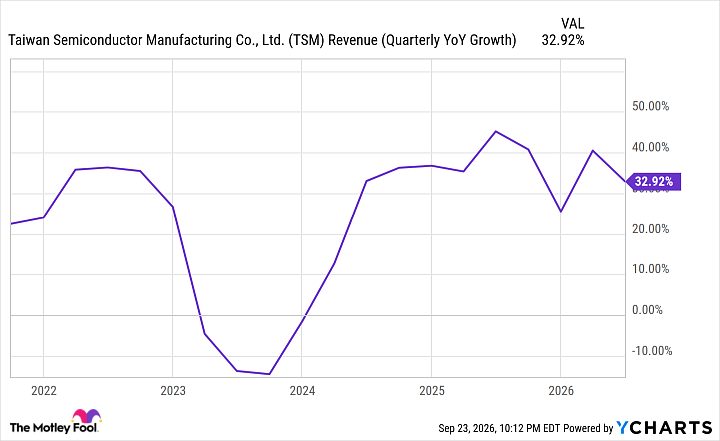
In the second quarter, TSMC's revenue rose 33.7% year over year to $40.2 billion, but more impressive is how much its margins have expanded. Over the past year, its gross margin rose from 58.6% to 67.7%, operating margin from 49.6% to 60.3%, and net profit margin from 42.7% to 55.6%.
TSM Revenue (Quarterly YoY Growth) data by YCharts
TSMC is making more revenue and profit than ever, and that's likely to continue for the next couple of years as the AI infrastructure build-out continues. It expects Q3 revenue between $44.6 billion and $45.8 billion, which would be 34.7% to 38.4% higher than its $33.1 billion in revenue in Q3 2025.
TSMC is a no-brainer buy
Trading at 26.5 times its projected earnings over the next 12 months, TSMC's stock isn't "cheap." However, it's worth the premium for a company that's by far the most dominant in its industry and will likely remain so because of the high barriers to entry.
TSMC is one of my largest holdings, and I plan to continue adding to my stake. Its importance to the tech world, even outside of AI, almost ensures continued long-term success.