Treasuries are considered safe because they are backed by the U.S. government. A "safe" 5% yield, which is where the 10-year Treasury is hovering around today, is pretty enticing if you are worried that stock prices are going to crater. However, bonds have a major shortfall for long-term investors. Here's why I'd rather own out-of-favor Hormel (HRL +0.34%) and its 5.6% yield.
The problem with bonds
To sum up the problem in one word: Inflation. A bond is a loan in which you provide capital and collect interest. But the deal is that when the loan matures, you get your principal back. Inflation will reduce the value of that cash, and the longer the bond, the worse the impact. Meanwhile, the interest you collect is locked in, so inflation slowly erodes the value of the interest you receive as well. Bonds can provide diversification to a portfolio, but they clearly have their own risks, too.
Image source: Getty Images.
Which is why I would prefer to own the food maker Hormel rather than a 10-year Treasury right now. Yes, I'm taking on more near-term risk. But I have the opportunity to benefit from Hormel's business growth over time. To be fair, Hormel hasn't been growing. The business is struggling, and management has been working on a turnaround. That's why Hormel's yield is so high right now.
Hormel has a strong foundation and a great history
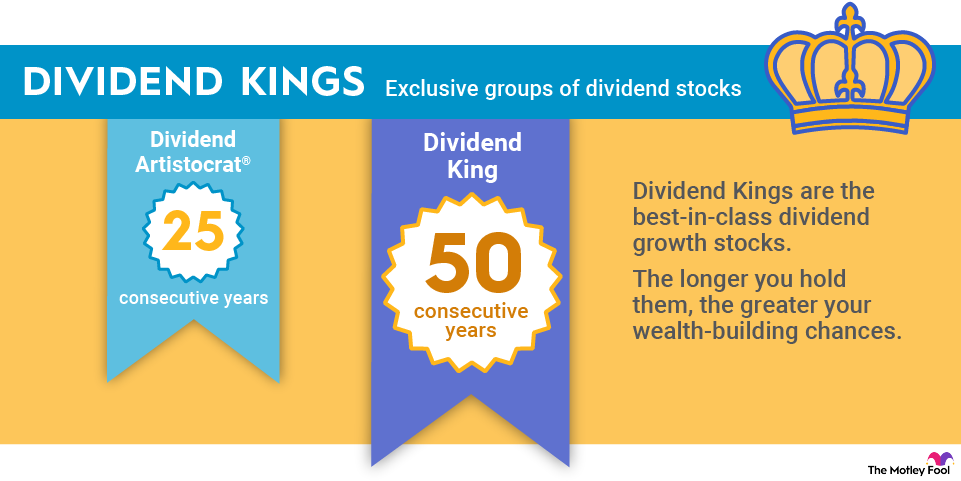
I believe Hormel's yield is ample compensation for the risk I'm taking on. While the company is revamping its business, it is a Dividend King with over 50 annual dividend increases. It has survived difficult times before. As for dividend safety, the company has modest leverage and covers its interest expenses 11x over. The company is operating from a position of financial strength, even if earnings are currently depressed.

NYSE: HRL
Key Data Points
And there's a more unique feature here that appeals to me. The Hormel Foundation controls around 47% of Hormel's stock. The foundation uses the dividends it collects from Hormel to fund its philanthropic efforts. In other words, there is a very large shareholder who wants Hormel to remain a financially prudent business that can continue to support and slowly grow its dividend. That's perfectly aligned with my desires for the business.
My time frame transcends a near-term bear market
Eventually, I expect Hormel's growth to pick up again. And I'm willing to collect what I see as a reliable high-yield while I wait. But the real story is that I'm not thinking in days, weeks, months, or even years. I'm thinking in decades. By the time a 10-year Treasury matures, I expect Hormel's share price to be higher and its dividend to be larger than either is today. With a bond, I'm locked in, and I know my principal and the interest I am collecting won't be worth as much in a decade due to the inexorable impact of inflation.