Artificial intelligence (AI) has been the single biggest driver of this nearly four-year bull market, and as its use expands, more investment opportunities emerge.
The impact is multitiered -- from the chips that process AI tasks to the data centers that house clusters of them and meet the demand for AI computing power; from the infrastructure and networks needed to power data centers and move the information from machine to machine, to the memory hardware that keeps all the data accessible to the servers that require it.
One critical group of companies within the AI universe are the specialists that manufacture and service the equipment that routes the massive electrical supplies required by AI data centers and provides the liquid cooling systems that dissipate the intense heat those powerful processors generate.
The leader in this area is Vertiv Holdings (VRT +1.94%). Vertiv addresses a major potential problem for all data centers and networks that compute AI data. Because so much electricity is required to run high-end data systems, the GPUs and CPUs generate large amounts of heat, as does the supporting power equipment. That heat can slow their processing speeds and shorten the chips' useful lives, if it's not removed efficiently.
For that reason, Vertiv's cooling systems have been in high demand, and its stock price is soaring, up 55% year to date. With that impressive performance behind it, is it still a buy?
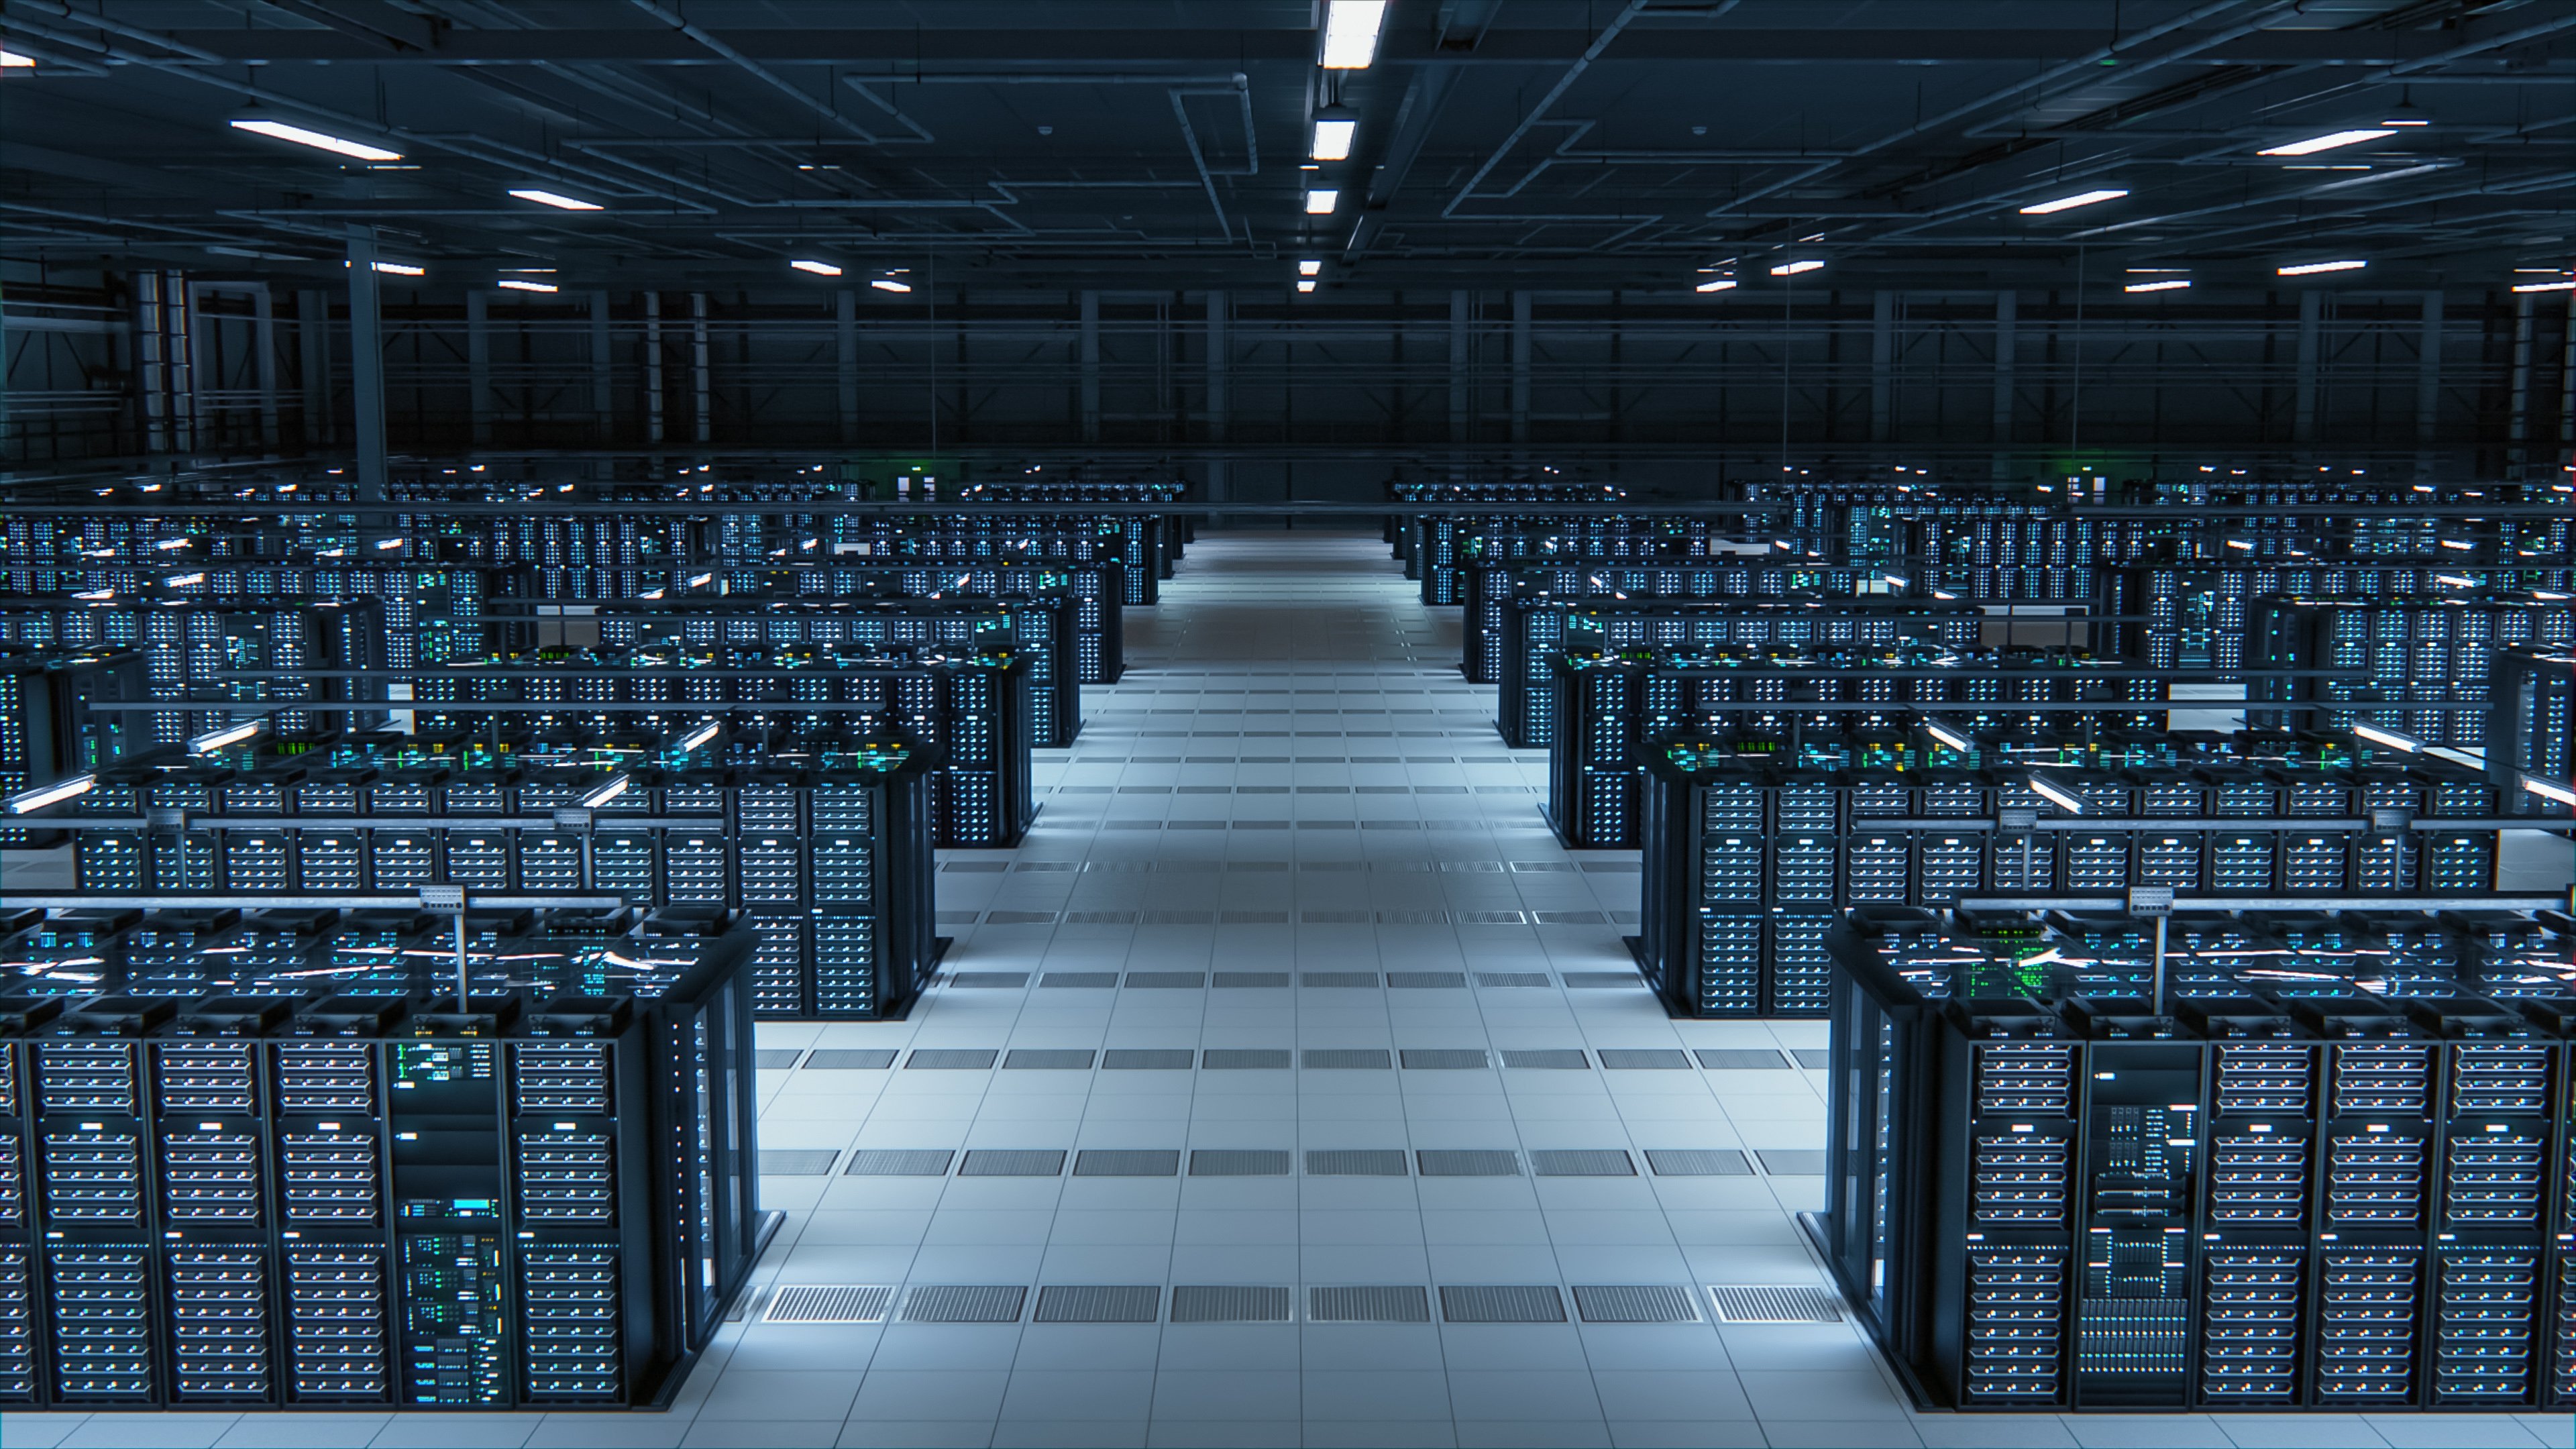
Image source: Getty Images.
Two new acquisitions
Vertiv signed deals for two major acquisitions this month. It agreed to buy UtilityInnovation Group, which makes microgrids that help data centers get more of the power they need. Those microgrids also benefit utilities by taking some of the strain off of regional power grids. The acquisition is expected to be accretive to Vertiv's adjusted earnings in the first quarter after closing.
Last week, Vertiv announced it was acquiring Ireland-based King Environmental, which provides liquid-cooling services and testing for data centers across Europe, the Middle East, and Africa. This will help Vertiv expand its global presence and leadership in the industry.
These expansion moves come after a strong second quarter for Vertiv. In the period, it increased net sales by 24% year over year to $3.3 billion, grew earnings by 53% to $1.27, and increased adjusted EPS by 60% to $1.51. It also boosted its operating cash flow by 241% to $1.1 billion and its free cash flow by 234% to $925 million. The company is making the $1.45 billion UtilityInnovation acquisition with cash, and it had $5.6 billion in liquidity at the end of Q2, so it will remain in a strong cash position after that deal closes.

NYSE: VRT
Key Data Points
A strong buy
Vertiv also projects free cash flow in the range of $2.4 billion to $2.6 billion for 2026, up 32% at the midpoint. When it delivered its Q2 numbers, it also raised its guidance for net sales and earnings for the year. In now expects 37% revenue growth and 60% adjusted earnings growth, driven by a strong project backlog.
It's also worth noting that at Vertiv's investor day in May, management targeted 20% to 22% compound annual revenue growth through 2030.
While there has been meaningful public pushback against data center development across the country, demand for them remains high and the funding continues to materialize, which puts Vertiv in a great spot.
Its shares have dropped in recent months, but now the stock is reasonably valued, with a forward P/E ratio of 27 and a five-year PEG below 1, suggesting that it's a long-term value. As such, Vertiv looks like a strong buy right now.