The artificial intelligence (AI) infrastructure build-out has supercharged the growth of chip designers, foundries, memory manufacturers, and other companies in the semiconductor ecosystem.
This isn't surprising, as semiconductors are the basic hardware layer of AI data centers. Basic AI tasks, such as processing data and storing parameters, wouldn't be possible without chips. So, it is easy to see why the semiconductor sector has boomed in recent years, given its role as the foundational hardware layer of the AI infrastructure ecosystem.
However, running AI tasks using these chips generates a lot of heat. An AI data center rack equipped with high-end graphics cards usually draws 40-100 kilowatts (kW) of power, which is well above the 5-10 kW power draw of a traditional server processor-based rack. Higher power consumption necessitates efficient cooling to enable AI accelerator chips to perform at their full potential.
Inefficient cooling will slow down graphics cards and other AI chips deployed in data centers. So, cooling plays an indispensable role in AI data centers, and investors can capitalize on this critical area by investing in Vertiv Holdings (VRT -2.34%).
Image source: Getty Images.
Data center cooling demand is powering Vertiv's growth
Vertiv offers multiple AI data center solutions, including power systems, server racks, device management, and thermal management. The company offers a comprehensive range of thermal management systems for AI data centers, including liquid-cooling systems, heat rejection systems, rack cooling tools, and thermal control and monitoring systems to increase data center efficiency and performance.

NYSE: VRT
Key Data Points
Vertiv's expansive AI infrastructure portfolio, which includes thermal management systems, explains why the company has been growing at a healthy pace in recent quarters. The company's Q2 revenue increased 24% to $3.27 billion, while adjusted earnings per share (EPS) rose 60% year over year to $1.52.
Importantly, Vertiv increased its full-year guidance due to the strong order inflow for its solutions. The company now expects a 60% increase in EPS this year to $6.70, on a 37% increase in revenue to $14 billion. Management noted on the August earnings call that it has a strong pipeline and expects "another year of robust orders growth."
It is worth noting that Vertiv's order backlog was $15 billion at the end of 2025. Its book-to-bill ratio was 2.9 in Q4 2025, indicating that it was receiving significantly more orders than it was shipping. Management's comments on the previous earnings call suggest that Vertiv continues to receive strong order inflow.
The good news for Vertiv investors is that the data center cooling market is poised to grow at a healthy pace over the long run, which isn't surprising as cooling is now a structural requirement in AI data centers. Grand View Research estimates that the global data center cooling market will clock a compound annual growth rate (CAGR) of 22% between 2026 and 2033, generating $128 billion in revenue by the end of the forecast period.
Vertiv's growth rate suggests that it is gaining share in the data center cooling market. So, the company seems well-positioned to sustain healthy long-term growth amid the secular growth in AI data centers, which explains why analysts have increased their long-term EPS growth expectations.
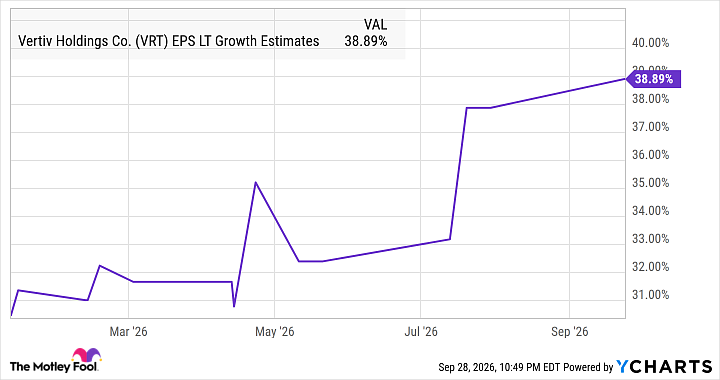
Data by YCharts
The stock could be a winner in the long run
Vertiv stock has jumped 50% in 2026. However, it has lost 35% of its value after reaching a 52-week high on May 14. This sharp pullback allows investors to buy Vertiv at an attractive 28 times forward earnings, which isn't very expensive compared to the Nasdaq-100 index's forward earnings multiple of 24.
Buying the stock at these levels could be a smart long-term move. After all, analysts expect a nice bump in Vertiv's earnings over the next three years.
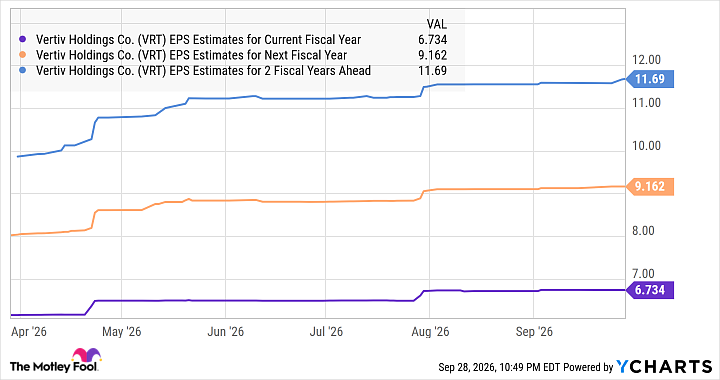
Data by YCharts
We have already seen that Vertiv could achieve 39% annual earnings growth over the long run. Assuming it maintains that rate in 2029 and 2030, its EPS could reach $22.37 in 2030 (using 2028's estimated EPS as the base). If this AI stock trades at 24 times earnings at that time, its stock price could reach $537 in under five years, implying potential upside of 120%.
However, I won't be surprised to see Vertiv delivering bigger gains, as it can outperform analysts' expectations in the long run due to massive investments in AI data centers, which could lead the market to reward it with a premium valuation.